

Within the first two posts of this three-part collection, we mentioned personal market individuals which can be lively in repo markets for profit-making motives. Central banks are additionally lively repo market individuals, however their causes typically differ from these of personal individuals. In at present’s submit, we talk about how central banks use repos to handle liquidity within the monetary system and implement financial coverage.
What Are Central Financial institution Repos and How Are They Used?
Central banks throughout the globe depend on repos to implement financial coverage and help market functioning. Market conference typically defines central financial institution or “public” repo (and reverse repos) from the attitude of the personal counterparty. For instance, within the personal repo market, the counterparty receiving money and offering securities is alleged to be executing a repo. In distinction, when the Federal Reserve receives money and supplies securities, it’s mentioned to be executing a reverse repo.
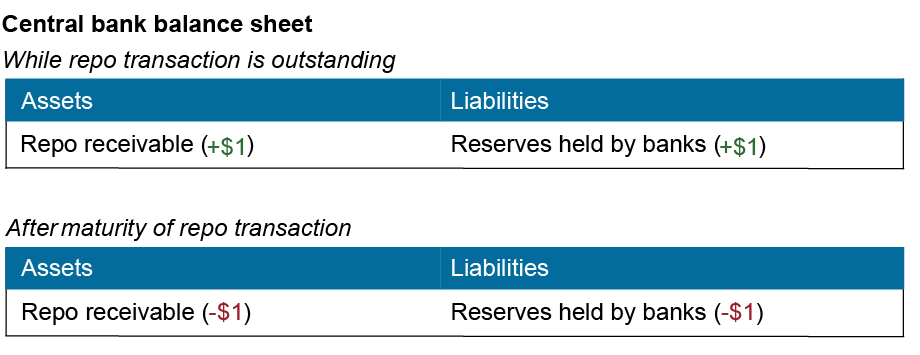
Central banks inject liquidity into the banking system by way of repos by buying securities from monetary establishments (sometimes industrial banks or sellers) and paying with (newly created) reserves. Because the diagram under exhibits, repos end in an enlargement of the steadiness sheet of the central financial institution and a rise in reserves within the banking system. Repos solely present liquidity whereas the transactions are excellent. On the maturity date, the central financial institution returns the securities and receives the reserves again, draining liquidity and shrinking its steadiness sheet.
Repos Inject Liquidity
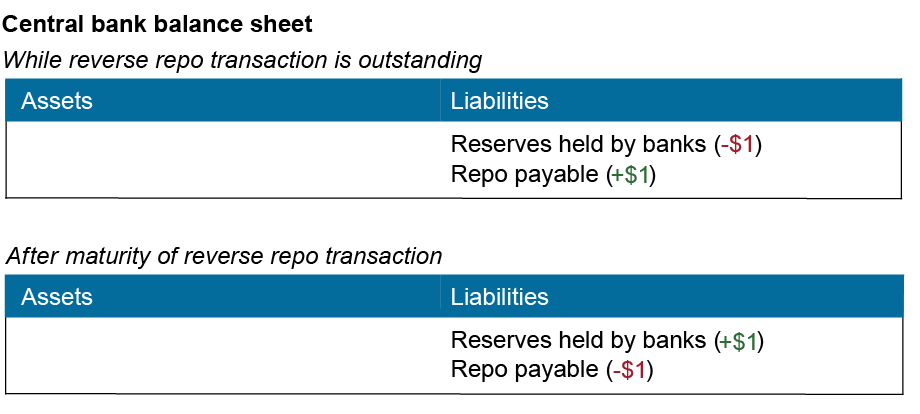
Conversely, central banks drain liquidity by way of reverse repos by promoting securities from their portfolios to monetary establishments. The central financial institution converts the reserves acquired as fee for the securities to a repo payable on its steadiness sheet, altering the composition of the liabilities on its steadiness sheet however not the scale. The flows are reversed on the maturity date, restoring liquidity.
Reverse Repos Drain Liquidity
Like personal repo market individuals, central banks additionally face decisions about eligible collateral, counterparties, fee, and settlement course of for his or her repo and reverse repo transactions.
How Does the Federal Reserve Use Repos and Reverse Repos?
The Fed conducts repo and reverse repo transactions each enterprise day to help its management over short-term rates of interest. Since 2021, when repos transitioned into in a single day standing repo operations (SRPs), the Federal Reserve has carried out each day repos with main sellers and eligible banks to produce liquidity and dampen upward stress on short-term charges. The SRP fee—set by the Federal Open Market Committee (FOMC)—supplies a ceiling on in a single day charges, because it presents eligible counterparties a supply of funding that reduces their incentives to borrow at market charges above the SRP fee. At the moment, these operations happen twice each day, towards high-quality collateral—Treasury, company debt, and company mortgage-backed securities—and decide on the identical day by way of the tri-party repo platform.
The chart under, which features a scrollable bar for detailed inspection, shows the amount of excellent Fed repos from 1918 to 2026, exhibiting how repos have adjusted to the liquidity wants of the banking system. For the reason that international monetary disaster, using repos has been concentrated throughout three episodes when the banking system wanted extra liquidity: in September 2019, after a considerable discount of the Fed steadiness sheet and amid market dislocations and upward stress on cash market charges; in March of 2020, in response to the COVID-19 pandemic and the sprint for money episode; and, extra just lately, in late 2025 following virtually two and a half years of steadiness sheet discount.
The Federal Reserve Begins Utilizing Repos in 1917
Billions of U.S. {dollars}
For Aug 1918–Dec 1935 knowledge: FRASER Information, Low cost Window Operations Repurchase Paper 1942-1958;
For 1936–49 knowledge: FRASER Information, Low cost Window Operations Repurchase Paper 1942-1958;
For 1949–53 knowledge: Banking and Financial Statistics, Desk 10.1;
For 1953–2002 knowledge: Federal Reserve Financial institution of St. Louis FRED database, RAGSHURA, RAAHURA, and RAFAOHURA;
For 2002–current knowledge: Federal Reserve Financial institution of St. Louis FRED database, RATPRA, WORAL, H41RESPPALGTRONWW, H41RESPPALGTRFNWW, RPTMTTLD, and RPONTTLD.
As famous above, along with repos, the Fed additionally makes use of reverse repos to empty liquidity from the banking system. In December 2015, reverse repo operations with main sellers advanced into standing In a single day Reserve Repo (ON RRP) operations. Since then, the Fed has carried out each day reverse repos at a fee set by the FOMC. The ON RRP fee locations a ground below in a single day market charges by providing eligible counterparties an in a single day funding alternative that reduces their incentives to lend at charges under the ON RRP fee. In contrast to earlier reverse repos, which have been executed simply with main sellers, the ON RRP is obtainable to a broader set of counterparties, together with cash market funds, banks, and government-sponsored enterprises. Equally to repo, ON RRP operations contain high-quality collateral and decide on the identical day by way of the tri-party repo platform.
Traditionally, reverse repos have been used much less ceaselessly than repos as a result of the Fed has historically structured its asset holdings to frequently add balances (by way of repo) moderately than drain reserves with reverse repos (or by lowering the everlasting portfolio). Their first use dates to the Nineteen Sixties, half a century after the Fed carried out its first repos (see chart under). The early precursors of reverse repos, referred to as matched-sale purchases, have been launched in 1966, and have been formally changed by reverse repos in December 2002. One notable exception to the modest use of reverse repos occurred through the interval that began in March 2021. As liquidity within the banking system grew from pandemic-related insurance policies, reverse repos steadily elevated, peaking at round $2.5 trillion in early 2023. Utilization then declined steadily because the Fed lowered its steadiness sheet.
The Federal Reserve Begins Utilizing Matched-Sale Purchases in 1966 and Reverse Repos in 2002
Billions of U.S. {dollars}
How Have Federal Reserve Repos Developed?
The origins of the Fed utilizing repos return to November 1917, when the Fed first licensed using repos as an alternative choice to collateralized loans, referred to as advances. On the time, a stamp tax imposed by the Struggle Income Act raised banks’ short-term borrowing prices and restricted the Fed’s means to offer liquidity to banks and help battle finance actions of the U.S. authorities throughout World Struggle I. Federal Reserve Banks created the circumstances to avoid the stamp tax by utilizing repos moderately than short-term advances that required bodily tax stamps. The usage of repos grew to become very talked-about on the time and Fed repo holdings briefly exceeded $1 billion, which represented round 30 % of Fed property in 1918.
Over time, the varieties of establishments licensed to have interaction in repo transactions with the Fed have modified in response to shifting coverage targets and transformations within the monetary system. When repos have been first launched as an alternative choice to financial institution advances, participation was restricted to member banks transacting with their respective regional Federal Reserve Banks (Murau et al. 2025). Subsequently, through the late Nineteen Forties and Fifties, as the aim of repos shifted from offering financial institution liquidity to making sure sufficient funding in cash markets and stopping short-term market disruptions, the eligible counterparties pivoted to main sellers completely (Garbade 2016). At the moment, the Fed conducts repo operations with each main sellers and qualifying banks.
Charges on Federal Reserve repo operations have undergone an identical evolution alongside adjustments in counterparty eligibility. The charges of the preliminary repo operations have been linked to the low cost fee, reflecting the first goal of facilitating financial institution borrowing. In the course of the Fifties, as repos advanced right into a mechanism for supplying markets with extra reserves to handle non permanent shortages and keep away from short-lived pressure, the repo fee grew to become tied to a market fee—particularly, that of Treasury payments (Garbade 2016). At the moment, the speed of Fed repos is set by the FOMC and serves as a device for influencing short-term cash market charges.
Two extra essential options of Fed repo operations are the varieties of collateral accepted and the settlement mechanism used. The collateral accepted in early repo operations included industrial paper, Treasury certificates of indebtedness (coupon-bearing Treasury securities with maturities not exceeding one yr), and Liberty Bonds, which have been particular battle bonds issued to finance U.S. participation in World Struggle I. This collateral composition mirrored the 2 main targets of early repo operations: facilitating financial institution borrowing and supporting wartime financing actions. Thereafter, Treasury securities grew to become the primary acceptable collateral, initially restricted to points with a yield of no more than the issuing fee for one-year Treasury obligations. This maturity constraint was progressively relaxed and ultimately eradicated in 1966.
A serious shift in each collateral and settlement practices occurred in 1999. Anticipating potential monetary market disruptions stemming from Y2K-related liquidity considerations and a constrained provide of Treasury securities, the Fed expanded its eligible collateral to incorporate company debt and mortgage-backed securities. Nevertheless, the Fed lacked the custody infrastructure and valuation experience to handle these new securities on the time. To broaden the pool of collateral, it established its first tri-party custodian preparations with the 2 main clearing banks working on the time—Chase and Financial institution of New York—and carried out its first tri-party repo operation in October. This strategy proved profitable, and by 2000, all Fed repos settled by way of the tri-party preparations.
To Sum Up
Fed repo operations have advanced considerably since their inception in 1917, adapting to altering financial circumstances and coverage targets. At the moment, repos and reverse repos function important instruments for implementing financial coverage and managing liquidity within the monetary system.
Gara Afonso is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Jun-Davinci Choi is a analysis analyst within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Gonzalo Cisternas is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Will Riordan is a capital markets buying and selling advisor within the Federal Reserve Financial institution of New York’s Markets Group.
How one can cite this submit:
Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan, “The Function of Repos in Financial Coverage Implementation,” Federal Reserve Financial institution of New York Liberty Avenue Economics, September 30, 2026, https://doi.org/10.59576/lse.20260930
BibTeX: View |
Disclaimer
The views expressed on this submit are these of the writer(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the writer(s).
