

Inflation appears higher than it did a month in the past, however not as a result of it improved a lot in August. Revisions from the Bureau of Financial Evaluation (BEA) lowered estimates of latest inflation with out materially altering the fast progress in general spending, which continues to be rising too rapidly for inflation to return to the Federal Reserve’s 2 p.c goal. In brief, the Fed nonetheless has work to do.
The Private Consumption Expenditures Worth Index (PCEPI), the Federal Reserve’s most well-liked measure of inflation, rose 0.3 p.c in August, based on new knowledge from the BEA, up from 0.1 p.c in July. The index has risen at an annualized price of three.6 p.c during the last six months and is 3.4 p.c greater than a yr in the past, unchanged from July’s price.
Core PCEPI, which excludes unstable meals and power costs, elevated 0.2 p.c in August, up from 0.1 p.c in July. It has risen at an annualized price of two.7 p.c during the last six months and is 3.0 p.c greater than a yr in the past, additionally unchanged from July.
In August, the BEA reported that costs had risen 3.7 p.c between July 2025 and July 2026. After this week’s annual replace of the nationwide accounts, the BEA now estimates that costs rose simply 3.4 p.c over the identical interval. The obvious enchancment due to this fact displays revisions to earlier knowledge, not a decline within the year-over-year inflation price in August. The revisions mirror greater than the BEA’s common updating of latest estimates. The annual replace included newly out there and revised supply knowledge, improved estimation strategies, and up to date seasonal adjustment elements. Amongst different adjustments, the BEA revised the way it measures costs for portfolio-management companies, authorized companies, and laptop software program.
Because the chart under exhibits, the previous and revised figures monitor one another intently by way of 2025 earlier than starting to diverge this spring. The BEA now estimates that inflation reached 3.8 p.c in Could, quite than the 4.1 p.c reported final month, and that core inflation was 3.0 p.c in July, quite than 3.3 p.c. On the revised knowledge, each headline and core inflation have been unchanged in August.
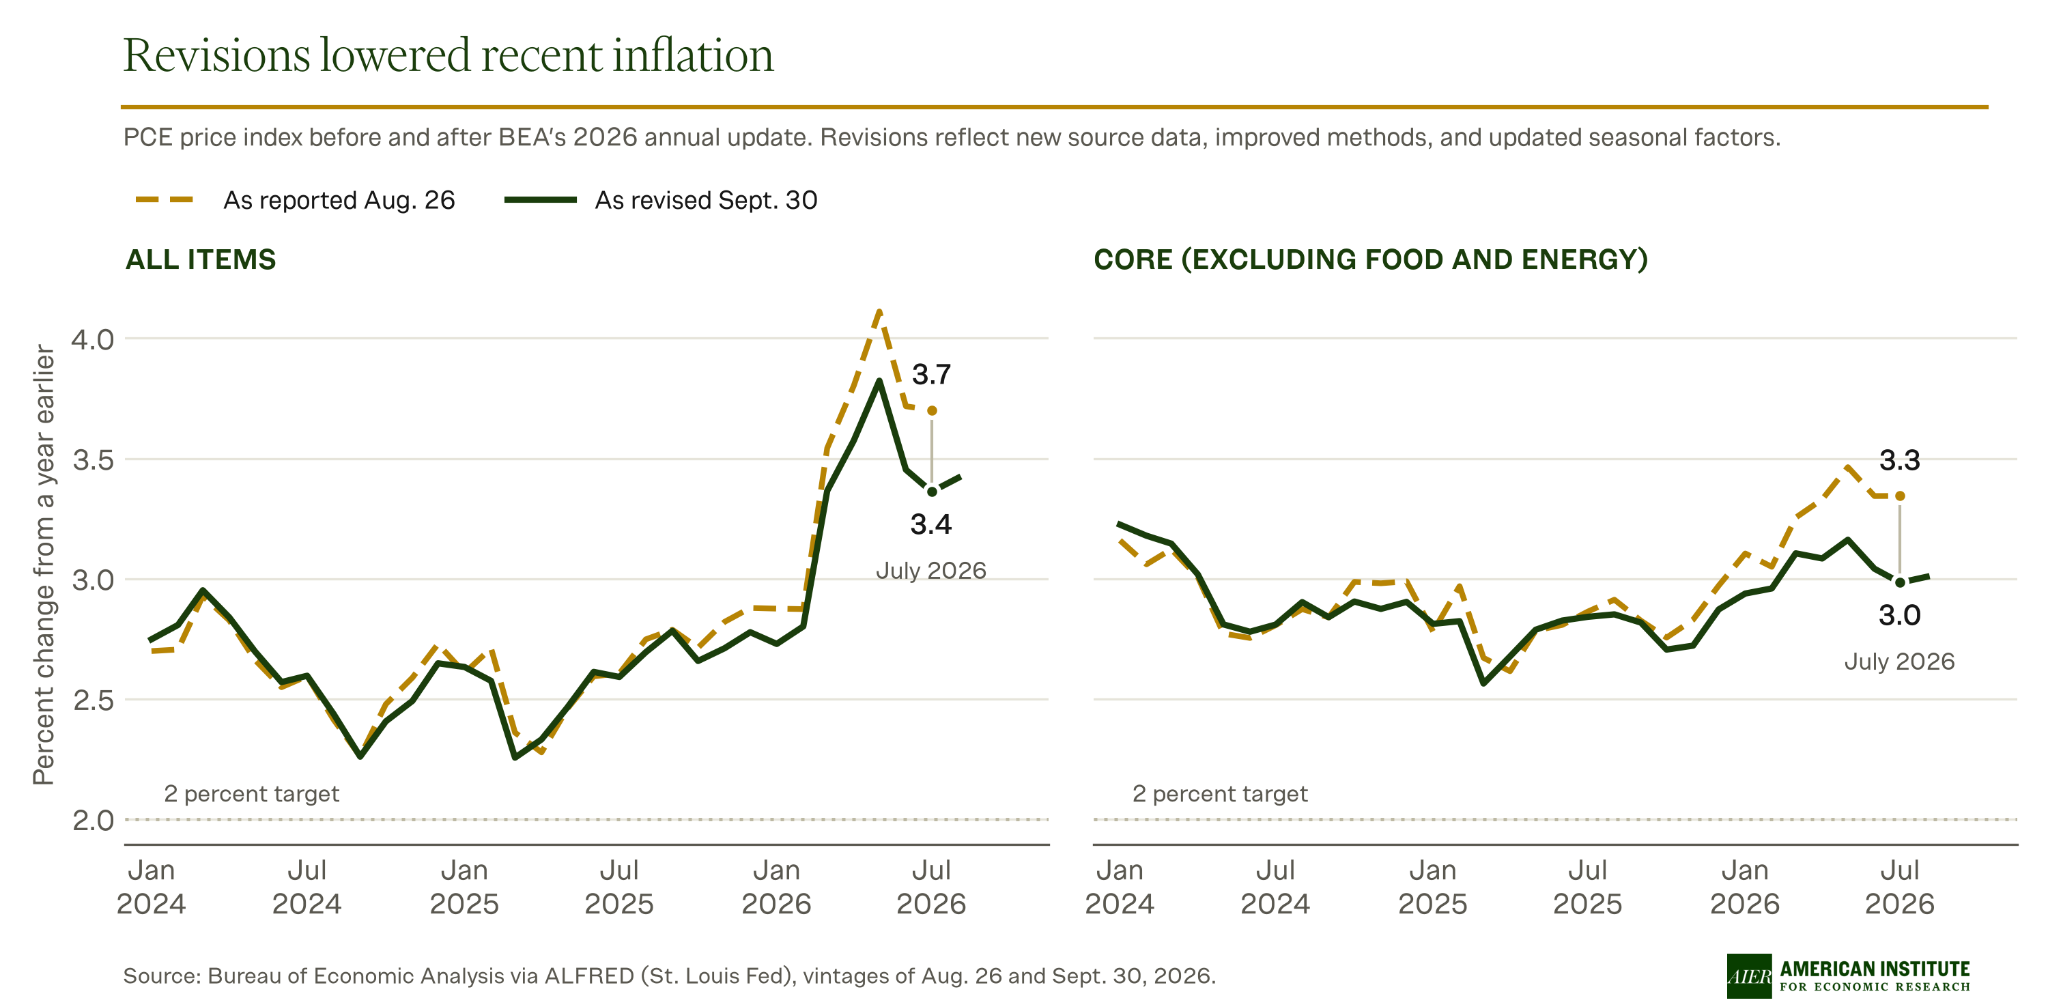
The revisions lowered the extent of latest inflation. They didn’t change its development. Even on the revised knowledge, costs are rising quicker than they have been a yr in the past, when the inflation price was 2.7 p.c. Over the previous three years, each headline and core costs have risen at a median annual price of about 2.9 p.c, above the Fed’s 2-percent goal. That development is why the Fed raised its goal vary for the federal funds price by 1 / 4 level, to three.75 to 4 p.c, at its September assembly. “Inflation stays elevated,” the committee’s assertion mentioned, and the rise “will help a timelier return to the Committee’s 2-percent purpose.”
The development that issues most for the place inflation is headed is in complete spending. Nominal spending, the greenback worth of all ultimate items and companies produced within the financial system, grew 6.3 p.c over the yr ending within the second quarter, based on the third estimate the BEA launched on Wednesday. That’s barely under the 6.6 p.c beforehand reported, however the revision does little to vary the underlying development. Nominal spending progress has exceeded 4 p.c in each year-over-year comparability since early 2021, and has averaged about 5.8 p.c yearly over the previous three years. Extra importantly, it has accelerated lately, rising from 4.8 p.c within the yr ending within the second quarter of 2025 to six.3 p.c over the newest yr.
Nominal spending can not constantly outpace the financial system’s productive capability with out finally resulting in greater inflation. The Fed’s newest Abstract of Financial Projections (SEP) places longer-run actual output progress at 2 p.c per yr. Add the Fed’s 2 p.c inflation goal, and nominal spending ought to develop about 4 p.c per yr over the longer run. As a substitute, nominal spending has grown 6.3 p.c over the previous yr, greater than 2 share factors above that benchmark. At that tempo, nominal spending is rising too quick for inflation to return to 2 p.c, which suggests financial coverage stays too unfastened.
There was progress. Core inflation has risen at an annualized price of two.7 p.c during the last six months, down from 3.9 p.c over the six months ending in Could. And since financial coverage impacts the financial system with a lag, the complete results of the Fed’s September price improve have but to look within the inflation knowledge. However with spending rising this quick, inflation is unlikely to return to 2 p.c with out additional price hikes.
That fast rise in nominal spending ought to form the Fed’s subsequent transfer at its October 27–28 assembly. However markets learn the report in a different way: the downward revisions to latest inflation seemingly diminished the perceived want for additional tightening, contributing to a decline within the odds of an October price improve. These revisions do little to vary the case for tighter coverage. Measured inflation fell by a couple of tenths of a share level, however the development in nominal spending didn’t change.
December’s assembly will carry the Fed’s first Abstract of Financial Projections incorporating the BEA’s revised inflation and spending knowledge. In September, 16 of 18 participants projected at the least yet another improve this yr, and 4 projected two. Decrease inflation figures shouldn’t cause them to reduce whereas general spending within the financial system continues to be working this scorching.
Sadly, the BEA releases third-quarter GDP the day after the Fed’s October assembly ends. If it exhibits nominal spending nonetheless rising nicely above 4 p.c over the previous yr, financial coverage is probably going nonetheless too unfastened. Till that hole closes, the Fed’s inflation battle is something however over.

