

In January 2002, shortly after the launch of the Starbucks Card, Michael Casey was its CFO and he reportedly gave a novel description of how Starbucks would use these funds. In keeping with Allen Eslekin, the unique Starbucks Card program supervisor, Casey was elated: this system represented “a $20 million curiosity free mortgage from our clients” that would cut back their reliance on banks for loans and working money.
In 2019, AIER contributor J.P. Koning reiterated this illustration in his Moneyness weblog. There, he defined that balances on reward playing cards amounted to $1.6 billion and “concurrently operate as a mortgage to Starbucks,” and clients are “offering the corporate with free debt.”
Not all writers agree with this analogy, nonetheless. Patrick McKenzie, who has achieved a deep dive into the economics of reward playing cards, characterizes Starbucks’ technique in a different way. He says that the float mannequin is “not a horrible psychological mannequin” nevertheless it “breaks down within the particulars.” McKenzie is cautious to characterize reward playing cards as a pay as you go steadiness.
Lenders of cash anticipate {dollars} again. Not so with a Starbucks reward card. The phrases for a present card buy make it clear that the steadiness is “nonrefundable” and that it “will not be redeemed for money,” except required by legislation. What’s owed is espresso or different Starbucks merchandise of the holder’s selection at an unsure location someday sooner or later. The corporate’s web site additional explains: “The greenback worth that you just load onto your Starbucks Card is a prepayment for the products and companies of collaborating shops.”
In keeping with their Q3 2026 SEC submitting, Starbucks holds over $1.8 billion in “saved worth card legal responsibility and present portion of deferred income.” Because of this card balances don’t depend as income till clients redeem them. The determine is on the legal responsibility aspect of their steadiness sheet. What Casey known as a $20 million interest-free mortgage in 2002 has grown greater than ninetyfold.
There is a crucial distinction between clients offering a agency with an interest-free mortgage and deferred income. If a buyer needs to mortgage cash to a company, they’ll accomplish that with a bond. Whereas a bond and a pay as you go steadiness each hand an organization cash at this time, that’s the place the similarity ends. Bonds are repaid in greenback items on a date either side comply with at an agreed-upon rate of interest. A saved reward card steadiness is one other matter. It’s redeemed at an unknown time, an unknown location, for principally unknown items.
The economic system of reward playing cards should additionally grapple with one other actuality: misplaced and forgotten playing cards. “Breakage” is the accounting time period for these playing cards which are misplaced behind your kitchen junk drawer or that slid between your bucket seats. There’s a line on Starbucks’ earnings assertion that acknowledges that deferred income doesn’t are available. In FY 2025 it acknowledged over $200 million in misplaced playing cards for its company-operated retailer revenues and one other $22 million by licensed shops. That quantity is then shifted from a legal responsibility and into the income column.
When clients load {dollars} onto reward playing cards, Starbucks estimates that some proportion of these balances received’t be redeemed for espresso after which counts that estimate as income. There’s no price related to this transfer both. If the cardboard isn’t redeemed, there’s no espresso, no cup, no oat milk, and no barista paid to serve non-redeemed espresso. That $222 million was roughly eight p.c of Starbucks’ $2.9 billion in working earnings for that fiscal yr.
What breakage can’t do is produce money. What it may well do is to goose the earnings experiences that shareholders and banks use to evaluate funding and lending choices. In FY 2025, Starbucks’ working money circulation fell by 22 p.c in comparison with the earlier yr. After its capital expenditures, Starbucks paid out $2.77 billion in dividends towards $2.44 billion in free money circulation and had no inventory repurchases.
SEC filings that present a company’s monetary internal workings are detailed and require some understanding of company accounting ideas to discern. One factor that isn’t revealed in any of Starbucks’ findings is what breakage revenues are used to fund. What is for certain is that they aren’t taking preliminary funds on reward playing cards and rising them over time. In a really actual sense, the longer you maintain onto a present card, or it goes undiscovered in your middle console, the much less espresso it’ll purchase.
The Bureau of Labor Statistics (BLS) espresso index stood at 201.8 5 years in the past. At present, it’s at 299.1. When it comes to costs, a pound of floor espresso has surged from $4.73 in September 2021 to $9.33 5 years later. What’s placing about these numbers is that espresso costs have gone down for the reason that outbreak of the battle with Iran. This isn’t a narrative about surging gasoline and transport prices, however one about long-run decreases in buying energy.
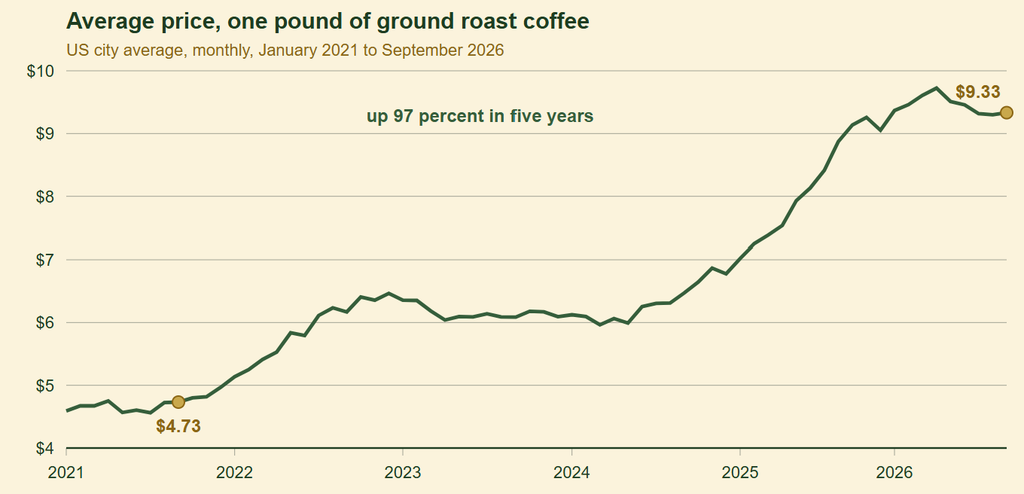
On this inflationary atmosphere, holding a Starbucks reward card topics one to an inflation tax. Pay as you go playing cards expertise a lack of buying energy in the identical manner that holding money balances do. Two years in the past, that $25 reward card could have bought 5 drinks at $5, however now could solely get you 4 at $6.25 every. Starbucks isn’t accountable for the continued worth inflation for all the prices that go into producing a cup of joe. Espresso lovers are getting much less bang for his or her buck and it isn’t primarily because of the Iranian oil shock. This can be a longer-run story of continuous credit score enlargement by the Federal Reserve system and its banks. Each new greenback erodes the worth of these already in your pocket — even these saved on Starbucks reward playing cards.

