

If you happen to’re acquainted with Alternative Worldwide, you already know the facility of microloans. A small quantity of capital may also help an entrepreneur develop a enterprise, enhance their earnings, and alter the trajectory of their household. However the affect doesn’t cease there; loans repaid could be lent out once more, renewing to develop into a possibility for the following household, and the following.
Not each success story begins with a mortgage.
Lengthy earlier than many entrepreneurs entry formal monetary providers, they’re already working exhausting to assist their households, handle unpredictable bills, and pursue targets for the long run. What they usually want first is a protected approach to save, a trusted neighborhood to study alongside, and a possibility to construct monetary abilities and confidence.
For thousands and thousands of individuals world wide, that steppingstone is a financial savings group.
At Alternative, we consider accountable monetary providers start with assembly shoppers the place they’re. For many individuals, meaning constructing financial savings habits, monetary data, and enterprise abilities earlier than taking up bigger monetary commitments. Financial savings teams create house for members to develop these foundations whereas strengthening their monetary resilience.
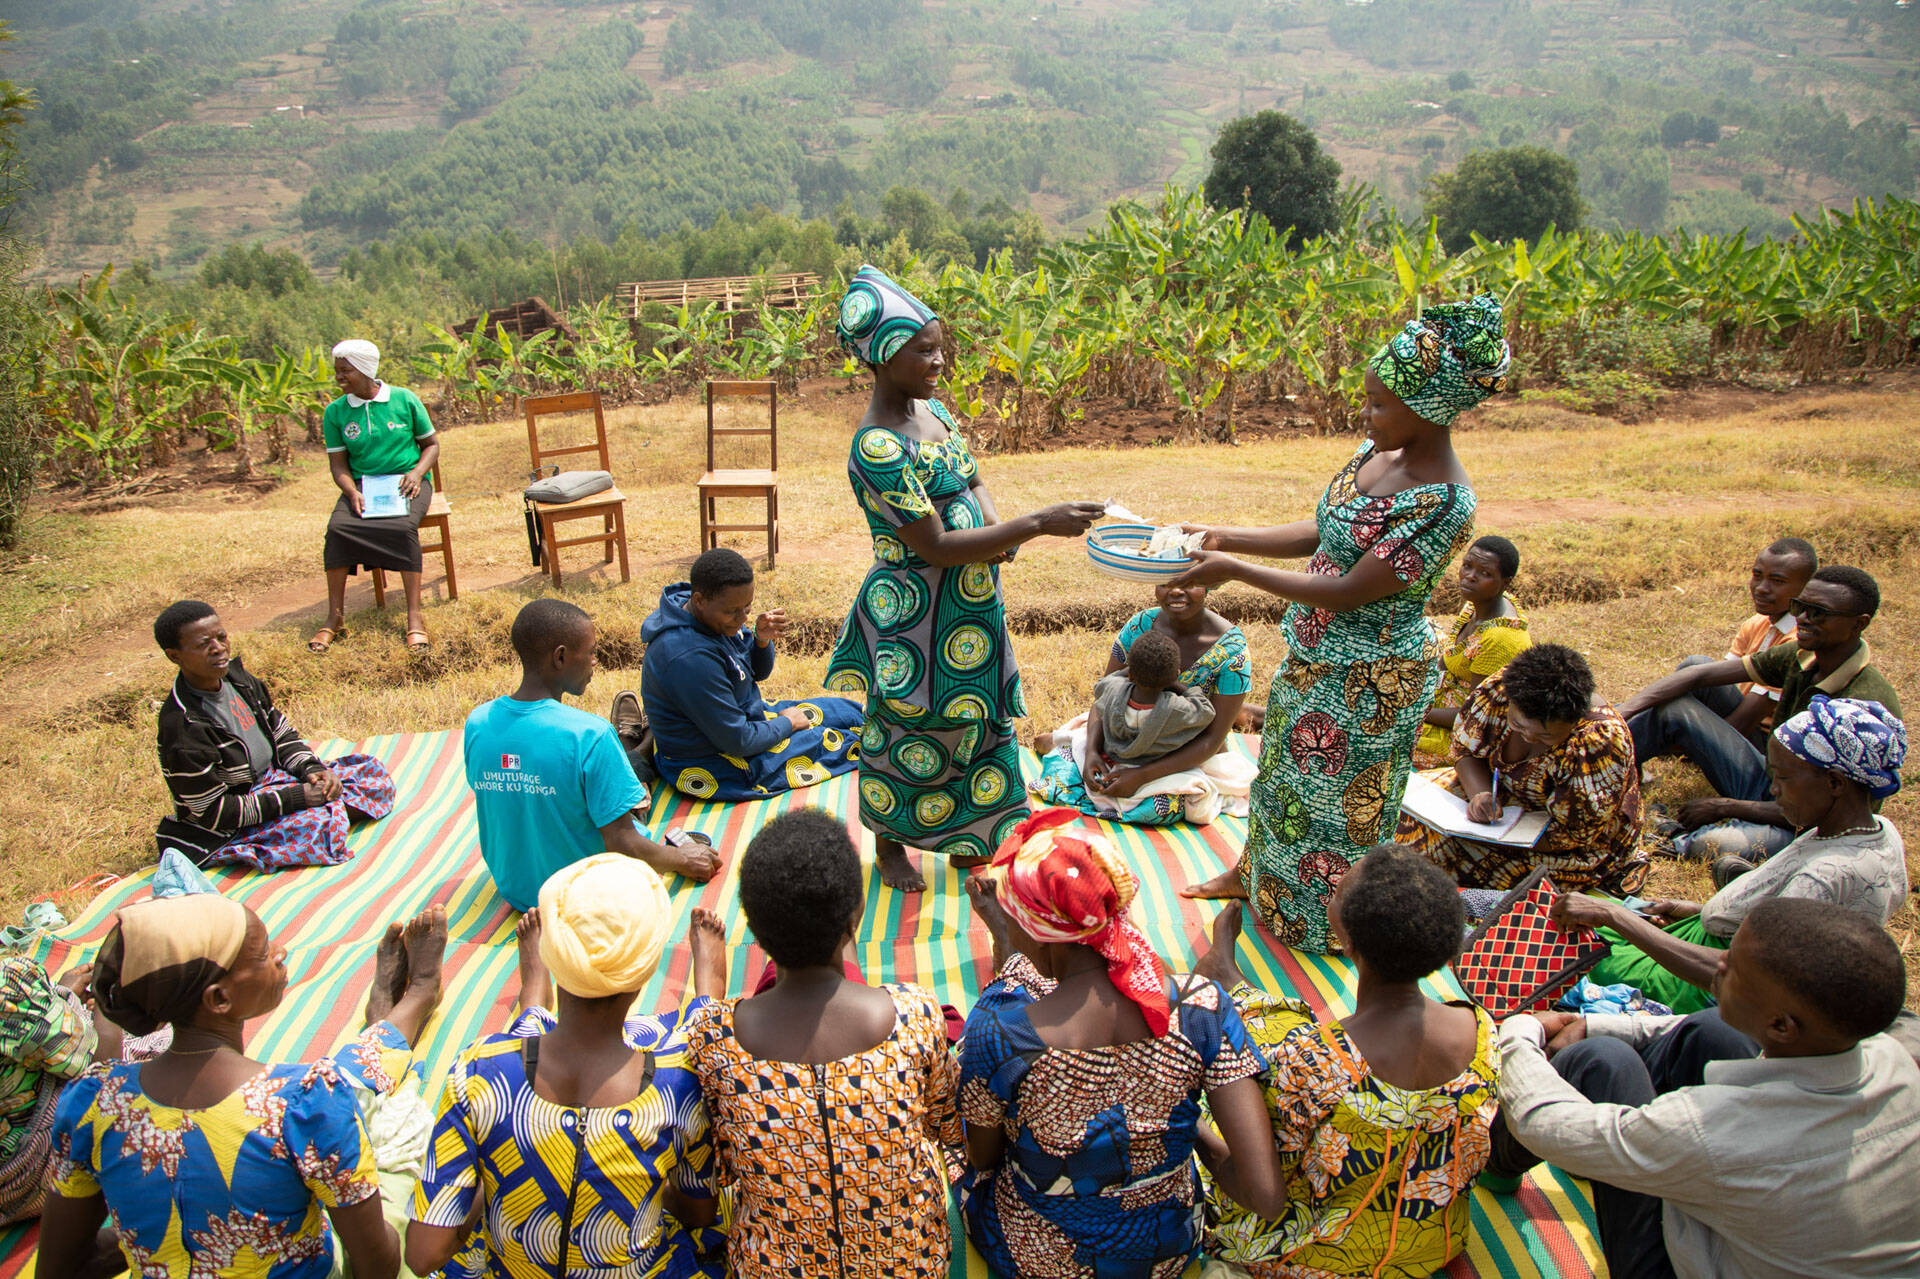
What Is a Financial savings Group?
A financial savings group is a community-based system that permits members to avoid wasting collectively and entry small loans from a shared pool of funds. Recognized by completely different names world wide—generally Village Financial savings and Mortgage Associations (VSLAs), Financial savings and Credit score Cooperative Organizations (SACCOs), or chamas—the idea is easy:
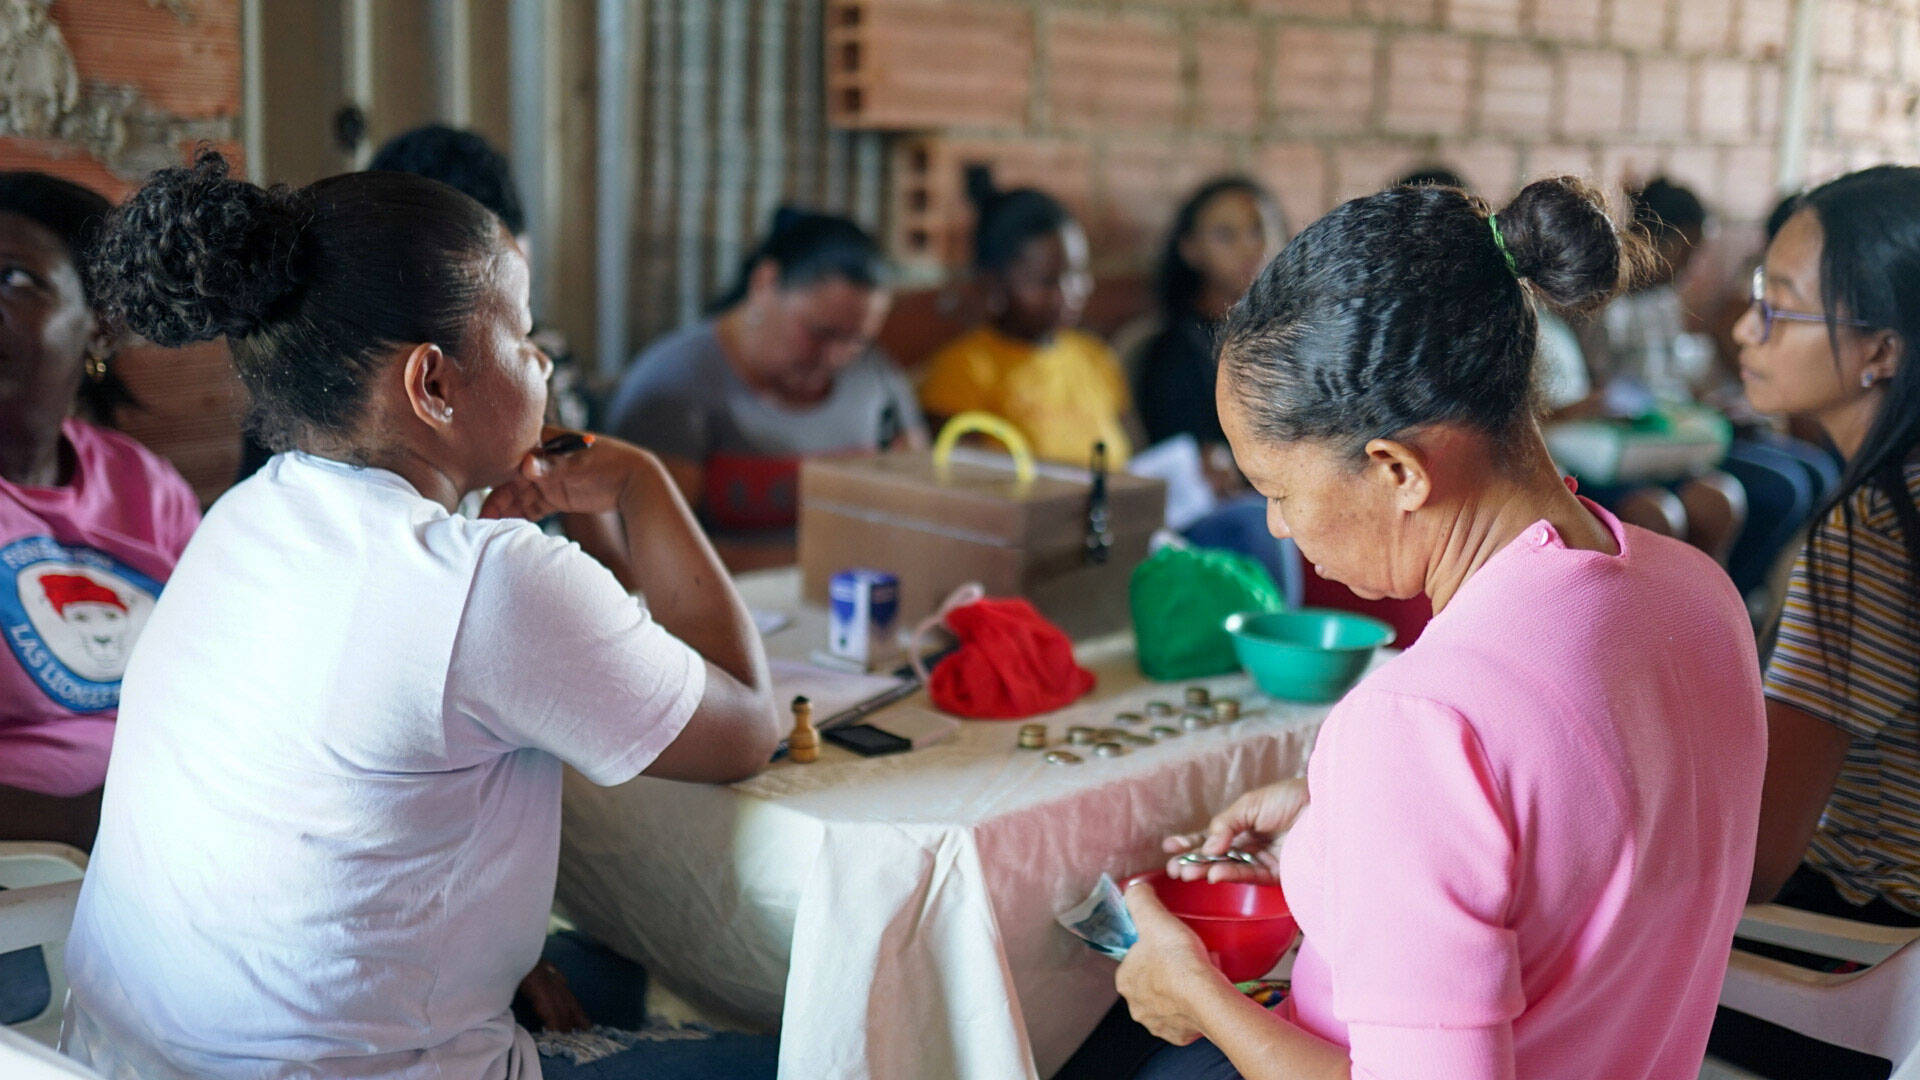
- Members meet weekly and contribute financial savings to a collective fund
- The pooled financial savings present small loans to members to make use of for wants resembling investing of their enterprise, paying faculty charges, or overlaying surprising bills like healthcare prices
- Debtors repay their loans with cheap curiosity
- Typically, on the finish of the yr, members obtain their financial savings again together with a share of the earnings generated by the group’s lending exercise
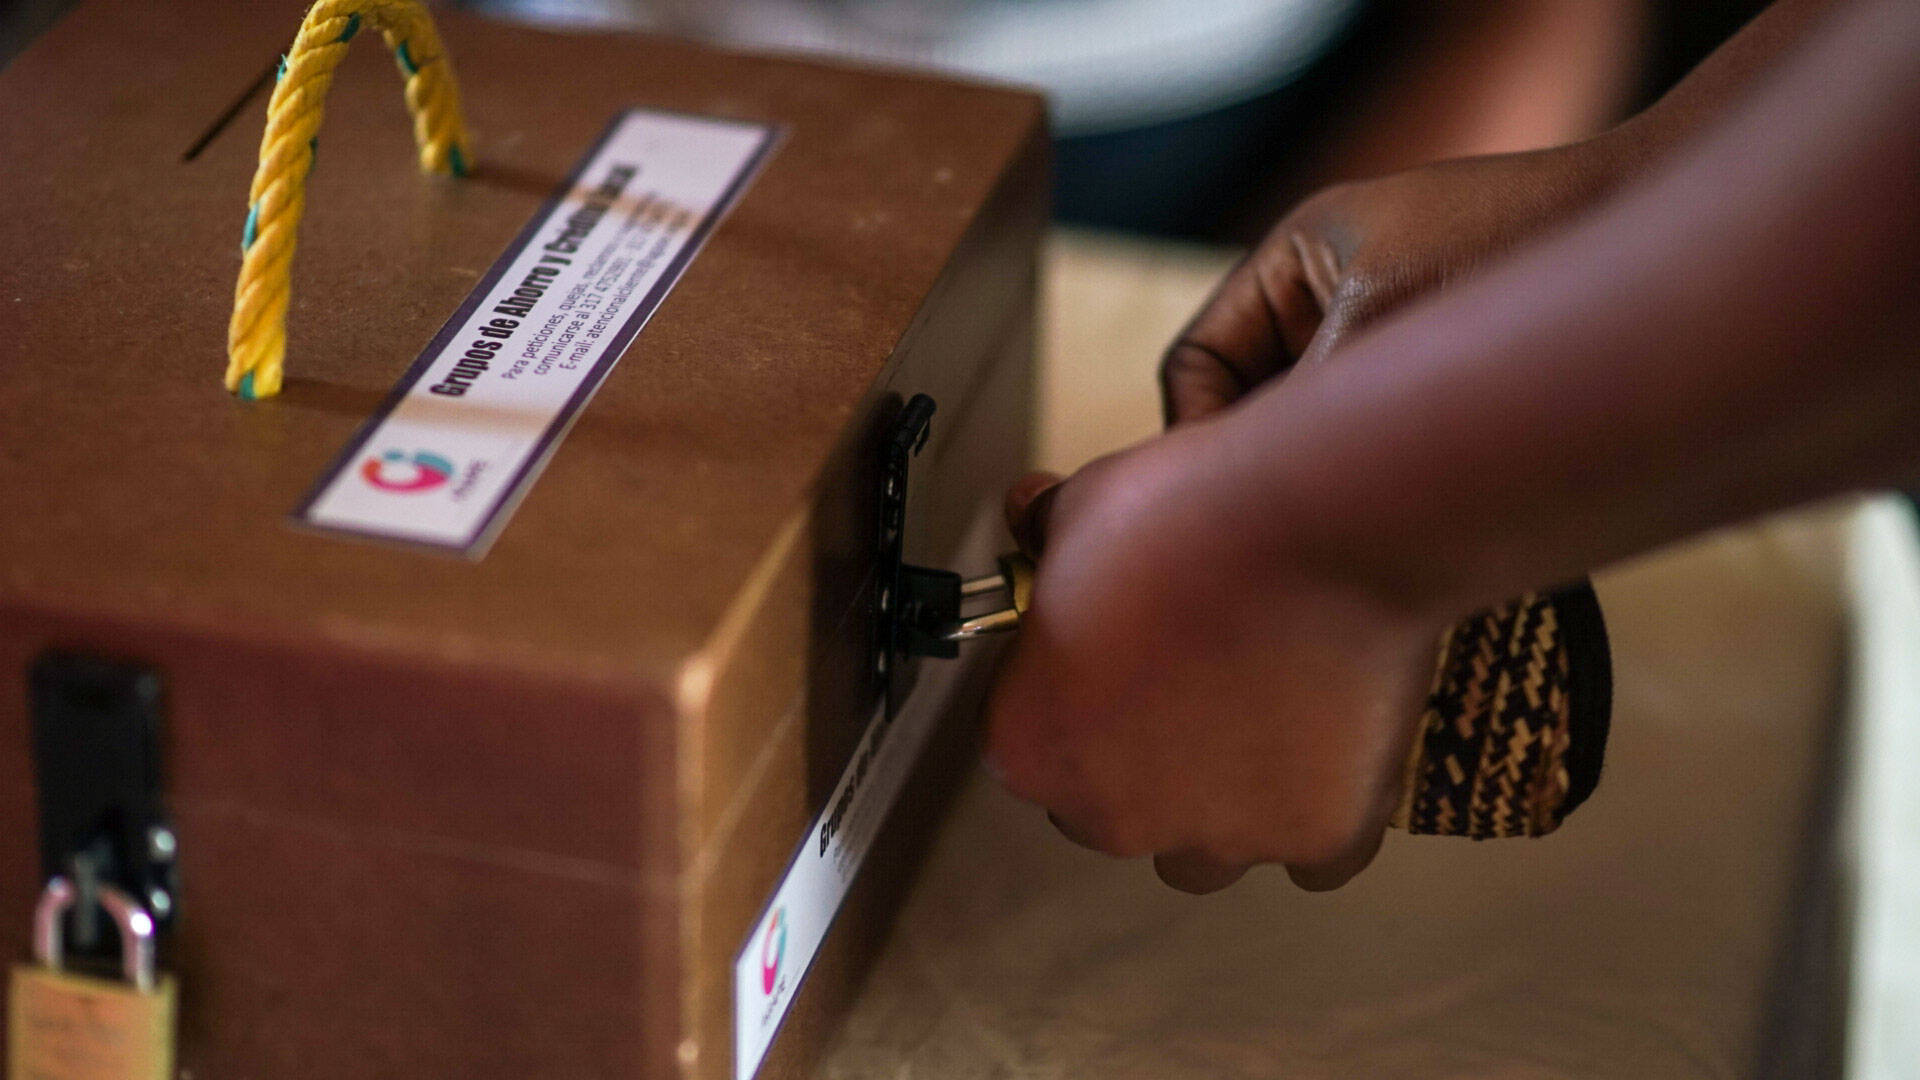
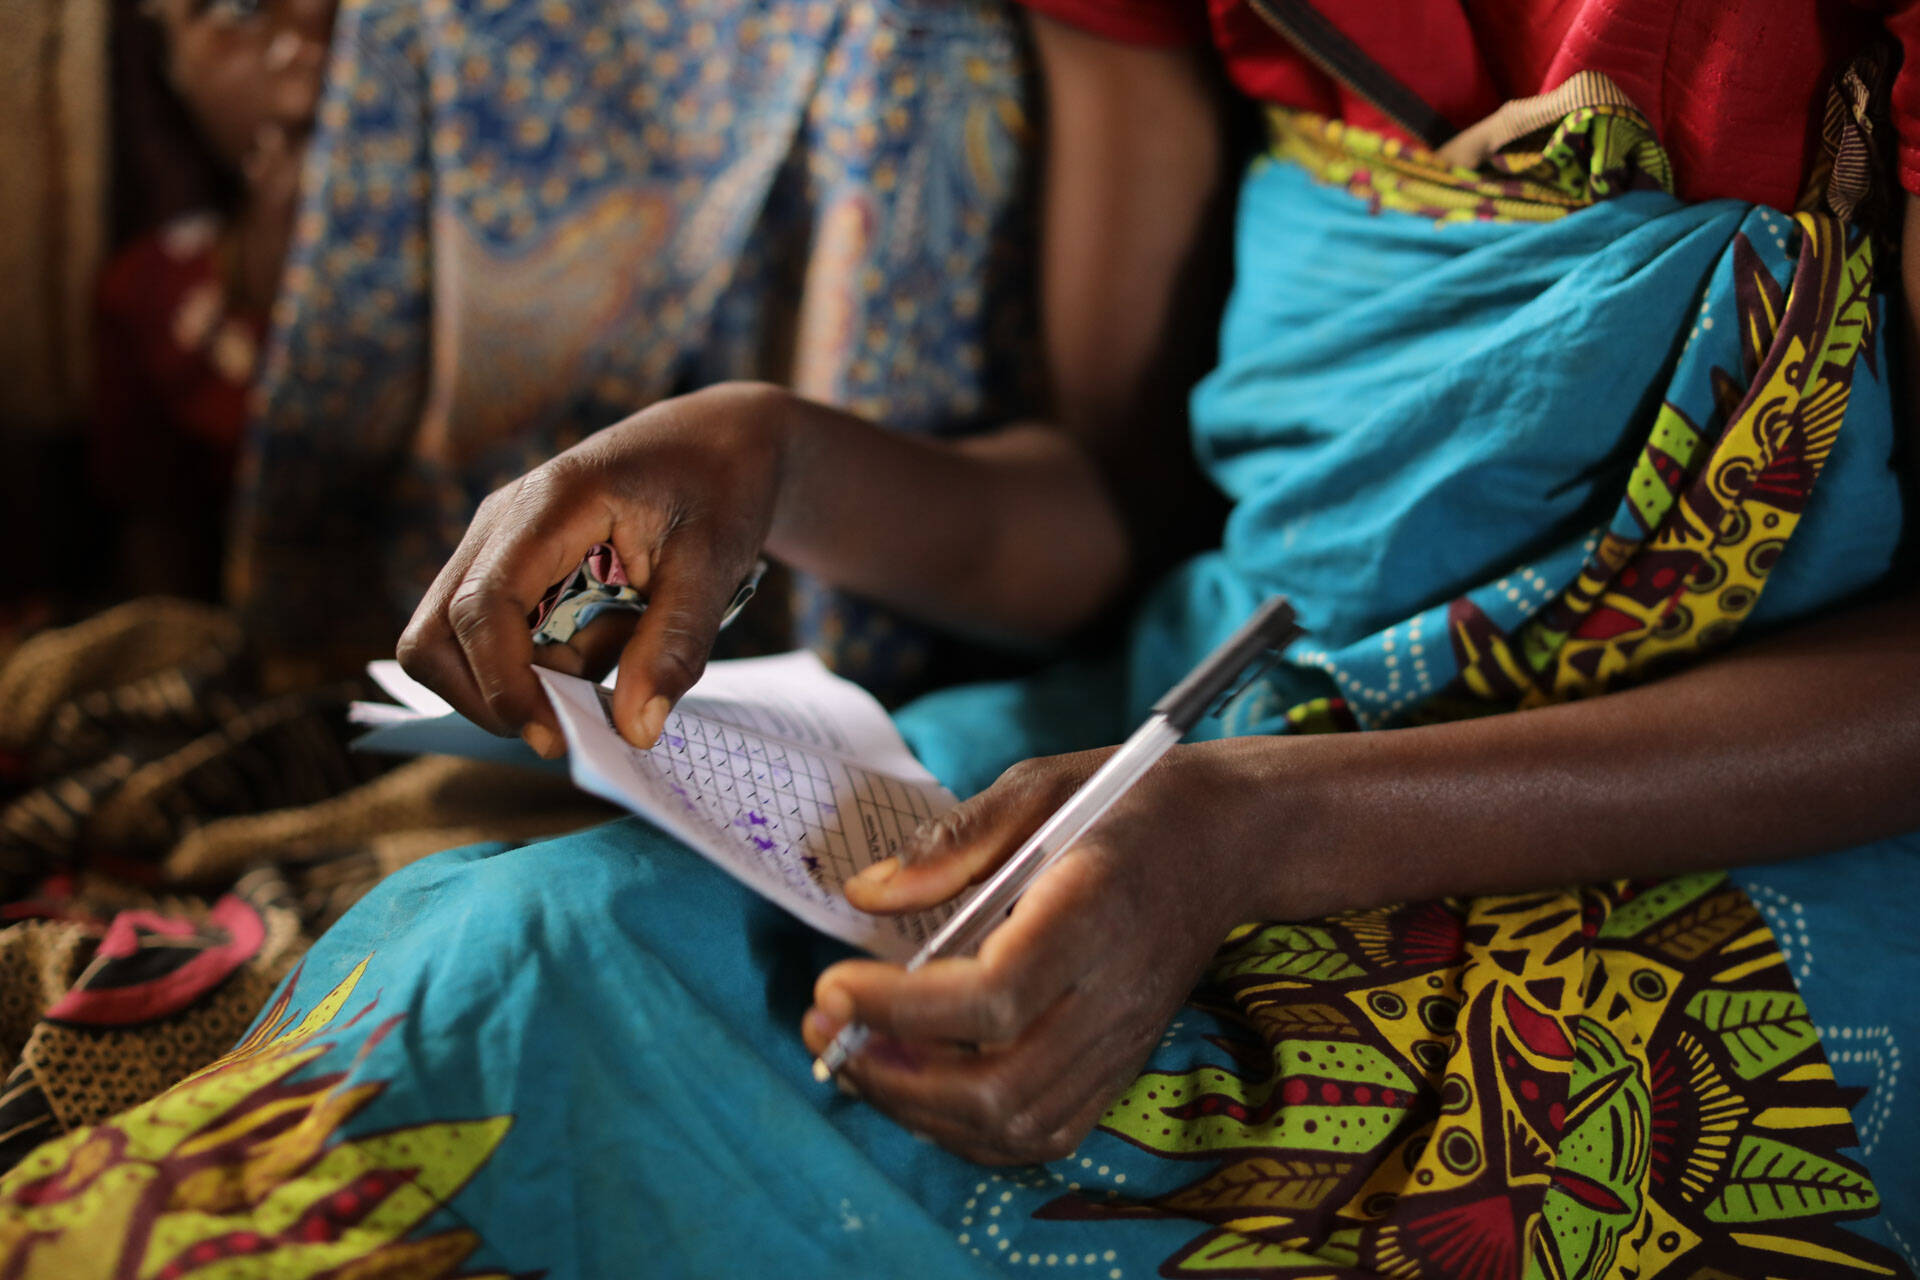
These casual monetary cooperatives function with exceptional self-discipline and accountability. Members create their very own structure, elect leaders, decide rates of interest, and determine how the group will function. To safeguard group funds, many financial savings teams use lockboxes secured by a number of locks, with every key held by a special member. Their success depends upon transparency, belief, and shared duty.
This native autonomy is without doubt one of the causes financial savings teams have efficiently unfold throughout international locations as numerous as Uganda, India, Malawi, Colombia, and past. Reasonably than imposing a single monetary mannequin, folks work collectively to construct a monetary system that displays their very own priorities, realities, and targets.
Do Financial savings Teams Work?
Whereas no single intervention can get rid of poverty, financial savings teams assist households construct monetary resilience, handle threat, and create alternatives for future development.
For households residing in rural areas particularly, conventional banking providers could also be distant, troublesome to entry, or unfamiliar. Revenue might arrive seasonally with their harvests reasonably than month-to-month. Many households are balancing quick wants whereas making an attempt to spend money on their future.
Alternative-supported financial savings group members additionally obtain coaching in monetary literacy, enterprise administration, family budgeting, and agricultural practices. These abilities assist members make knowledgeable selections about their households, farms, and companies.
For shoppers, these abilities could be simply as beneficial as entry to capital itself.
Amongst farmers taking part in Alternative-supported financial savings teams in Malawi, Rwanda, and Uganda:
- 73% elevated their earnings
- 74% reported having the ability to meet an emergency expense
- 85% improved the quantity or high quality of household meals
- 88% reported an improved high quality of life (Alternative Worldwide, 2026)
Related outcomes have been achieved in Colombia, the place Alternative-supported financial savings group members reported elevated financial savings, better confidence, stronger participation in household decision-making, and a rising curiosity in monetary coaching alternatives (Alternative Worldwide, 2024).
By becoming a member of a financial savings group, households can easy earnings fluctuations, higher handle emergency prices, pay faculty charges, spend money on farming and enterprise actions, and face up to surprising monetary shocks.
Why Girls’s Financial savings Teams Are So Highly effective
Whereas financial savings teams profit total communities, they’re particularly necessary for girls.
Globally, girls proceed to face obstacles to accessing formal monetary providers. They’re much less more likely to personal property, have collateral, keep a proper credit score historical past, or safe financing on equal phrases, regardless of proof exhibiting robust compensation charges amongst girls debtors. That is why financial savings teams have develop into an necessary house the place girls working in casual companies can entry capital, strengthen monetary abilities, and develop into leaders of their communities. In Uganda, for instance, girls characterize 66% of group members and 61% of group leaders (Gates Basis, 2024).
The affect reaches past earnings. Financial constraints are the most typical cause for kids to drop out of college. However when girls are invested, they regularly use their earnings to assist their kids’s training, that means extra daughters and sons keep in class (Alternative Worldwide, 2019).
Girls are the important thing to constructing monetary resilience for the entire household.
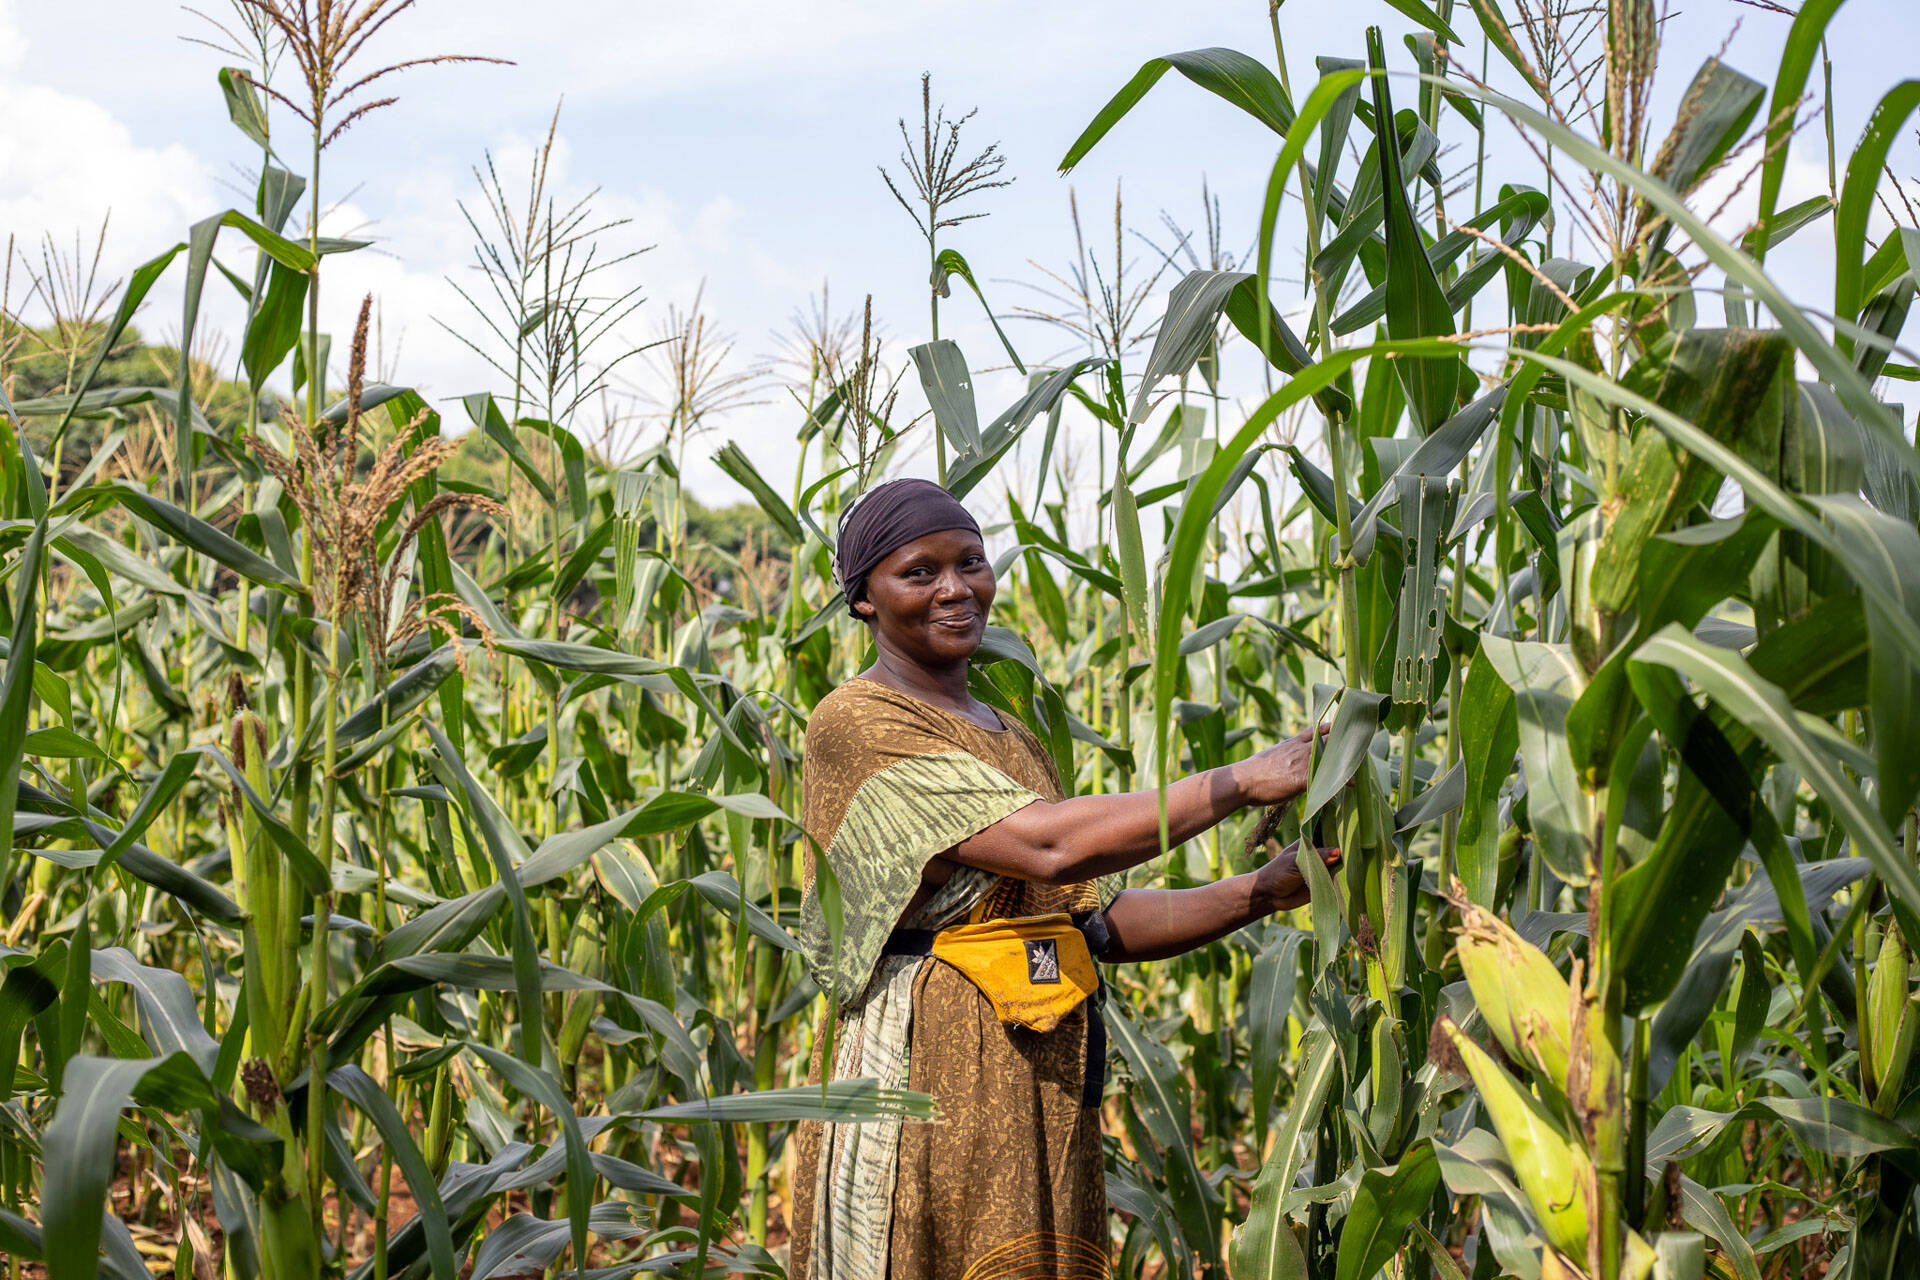
Namulondo’s Story: A Farmer’s Path to Stability
Namulondo, a mom of eight and a small-scale farmer in Uganda, is aware of firsthand how transformative that mixture of financial savings, coaching, and assist could be.
Earlier than becoming a member of her native financial savings group, named “Collectively We Can,” she labored tirelessly to offer for her household. Like many farmers, she relied on agriculture for her livelihood however confronted challenges that restricted her progress. Her maize yields remained low, and paying faculty charges for her kids was usually troublesome.
Becoming a member of a financial savings group opened the door to greater than monetary providers.
By Alternative-supported coaching supplied by a Farmer Assist Agent, Namulondo constructed abilities in farm productiveness and yield enchancment, monetary literacy, enterprise administration, and family planning, together with gender equality. These trainings supplied each sensible instruments and a brand new framework for decision-making on her farm and inside her family.
Making use of improved farming strategies, she shifted her focus from farming extra land to farming extra productively, decreasing her maize plot from three acres to at least one and a half. Her harvest elevated dramatically—from 5 100-kilogram luggage per season to 24. Her farm has since been acknowledged as a mannequin website for different farmers.
She additionally diversified her sources of earnings, including espresso, bananas, and poultry. This strengthens her household’s resilience when climate, costs, or pests create uncertainty, whereas additionally bettering her soil’s well being and farm’s sustainability.
On the similar time, she elevated her weekly financial savings from 2,000 to 10,000 Ugandan shillings and gained entry to capital she might reinvest into her farm and companies.
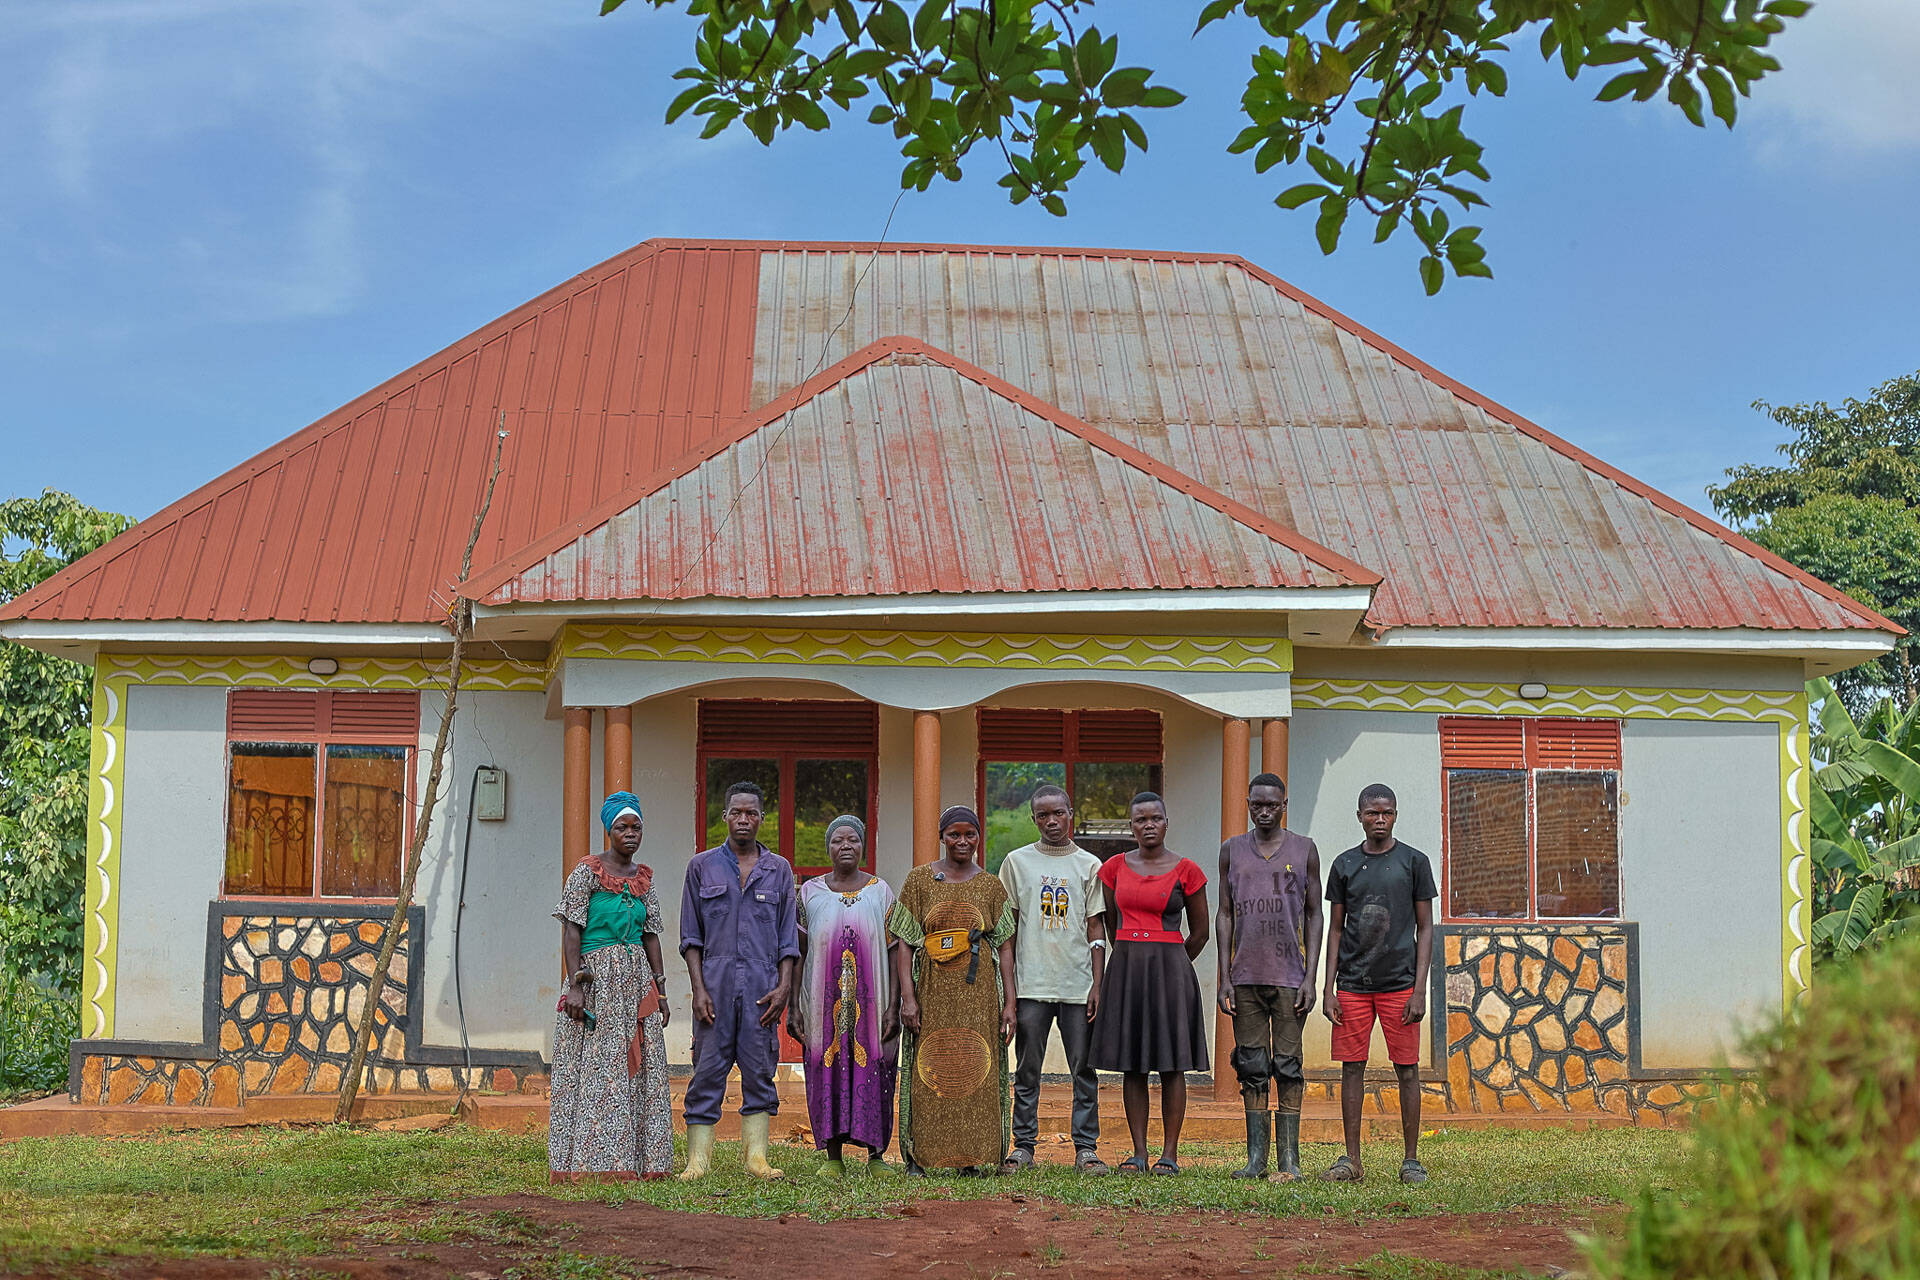
The outcomes prolonged past agriculture. Her kids are attending faculty persistently. Her household has improved their housing and has extra dependable entry to meals and healthcare. She and her husband now make many monetary selections collectively, strengthening long-term planning for his or her future.
Namulondo nonetheless faces challenges. Local weather dangers, altering markets, and enter prices stay realities of smallholder farming. However right this moment she has extra instruments, data, and alternatives to navigate these challenges than she did earlier than.
Her story illustrates an necessary reality: lasting change comes from constructing the talents, confidence, and assets that assist folks make higher selections and construct the futures they envision for themselves.
Financial savings Teams as a Bridge to Formal Finance
Probably the most necessary issues to grasp about financial savings teams is that they don’t seem to be merely an answer for these labeled as “unbankable.” They’re usually step one towards broader monetary inclusion, particularly in communities the place entry to formal monetary providers stays restricted.
A financial savings group is usually the place members first study monetary administration, set up financial savings habits, follow accountable borrowing, and construct information of financial exercise wanted to entry broader monetary providers sooner or later.
As companies develop and monetary wants develop into extra complicated, some members want bigger loans or extra providers than a gaggle can present by itself.
That is the place Alternative helps create pathways to formal monetary inclusion.
When Alternative connects mature financial savings teams with trusted monetary establishments, members can start constructing a monetary id, creating a credit score profile, and accessing new instruments designed to assist enterprise development and family stability.
For a lot of entrepreneurs, particularly girls, this development could make the distinction between working a casual enterprise and constructing a sustainable enterprise.
Challenges and Alternatives Forward
Financial savings teams are highly effective, however they don’t seem to be with out challenges.
Lending is restricted by how a lot a gaggle can collectively save. File-keeping could be time-consuming, and errors can undermine belief. Rural communities may additionally face obstacles resembling distance from monetary establishments, restricted connectivity, and unequal entry to cellular expertise.
At Alternative, we work alongside communities, monetary establishments, governments, and expertise companions to deal with these challenges. For instance, when financial savings teams are linked with trusted banks, they’ll safely deposit their funds into financial savings accounts. Alternative and our monetary establishment companions proceed to work with trade leaders and governments to analysis the very best mannequin for financial savings teams (Alternative Worldwide et al, 2025).
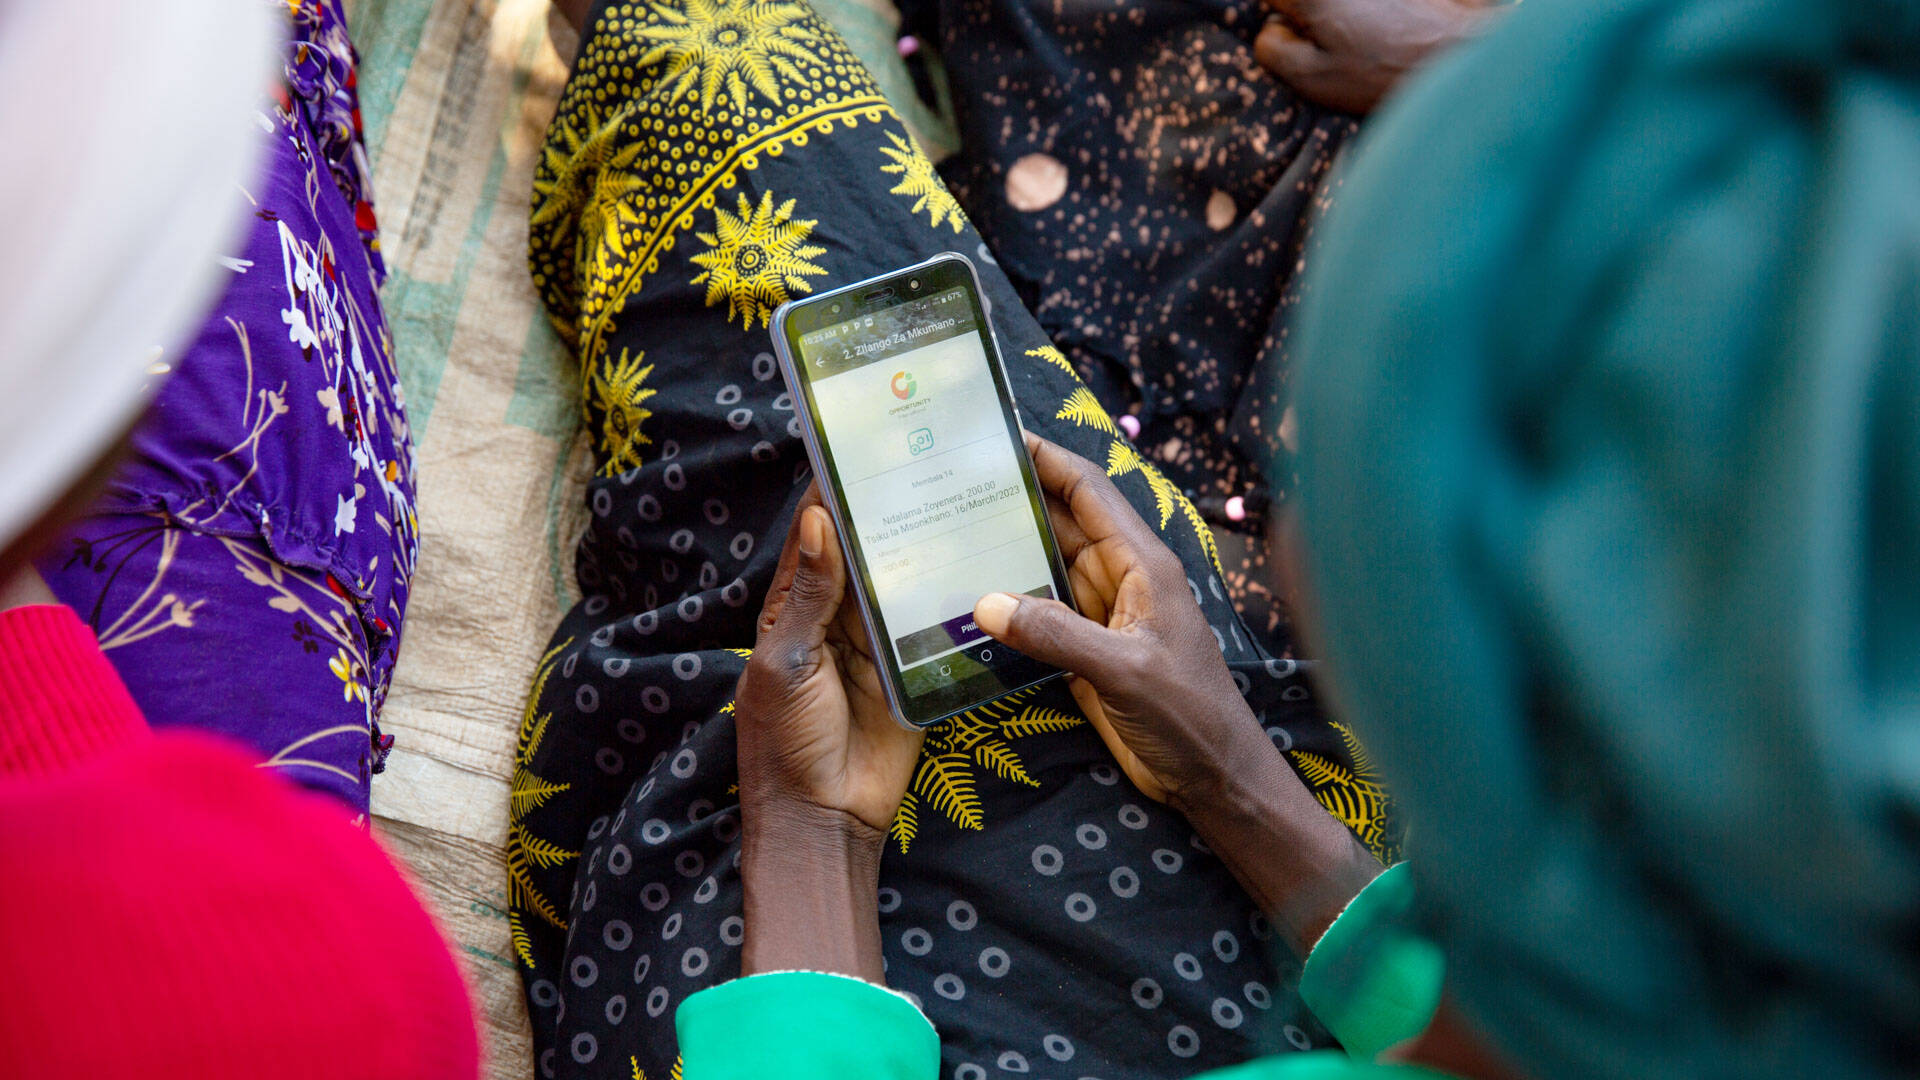
One promising innovation is the digitization of financial savings group information by means of instruments such because the DreamSave app. Early outcomes from Alternative’s DreamSave pilot in seven international locations are encouraging. Amongst 749 financial savings teams representing greater than 16,000 members—70% of whom had been girls:
- 96% of members had been happy with their group’s record-keeping utilizing DreamSave
- Monetary disputes associated to information decreased considerably
- 65% reported shorter assembly instances
- 90% stated they had been keen to contribute towards smartphone and connectivity prices after experiencing the advantages of the platform (Alternative Worldwide, 2025)
Digitization helps teams strengthen transparency, accuracy, and belief whereas making a monetary historical past which will ultimately assist stronger connections to formal monetary establishments. Challenges stay, together with connectivity prices and gender disparities in cell phone possession (Alternative Worldwide et al, 2025). But early outcomes recommend digital instruments work greatest when paired with what issues most: robust native management, trusted relationships, coaching, and neighborhood possession.
From First Financial savings to Lasting Alternative
In the present day, Alternative helps almost 26,000 financial savings teams serving greater than 512,000 members throughout Africa and Latin America (Alternative Worldwide, 2026).
Behind these numbers are lots of of 1000’s of individuals like Namulondo—dad and mom, farmers, and entrepreneurs who’re working every single day to construct stronger futures for his or her households.
We consider monetary inclusion begins with assembly folks the place they’re. Generally meaning a mortgage. Usually, it begins with one thing easier: a financial savings group, a coaching session, or a trusted mentor.
By persevering with to increase financial savings teams, strengthen pathways to formal finance, and spend money on digital and community-based options, we may also help be sure that extra folks—particularly girls and people residing in distant communities—have entry to the alternatives they deserve.
Namulondo’s story reminds us that lasting transformation isn’t a few single mortgage or transaction. It’s constructed over time by means of data, financial savings, and neighborhood.
Assist create pathways to monetary inclusion for girls, farmers, and entrepreneurs world wide. Give the present of alternative at alternative.org/donate
