

One thing uncommon is going on in international bond markets, and it’s extra consequential than the same old swings in yields. Authorities borrowing prices are rising throughout a lot of the developed world. The US 10-year Treasury is approaching 5 %, and the 30-year Treasury yield is at ranges not seen since 2007. “Meltdown” is simply too dramatic a phrase, however the bond market is clearly sending a message. Bond costs fall when buyers demand increased yields, and international buyers clearly wish to be paid extra for lending cash to governments carrying giant money owed, operating persistent deficits, and nonetheless contending with above-target inflation.
Japan is maybe essentially the most placing case. Its 10-year authorities bond yield has moved by means of 3 % after spending most of a technology close to zero, and its 30-year borrowing value has risen above 4 % — a multi-decade excessive. Australia’s 10-year just lately reached 5.16 %. Germany’s 10-year Bund has been buying and selling round 3.3 %, with the 30-year above 3.8 %. Britain, France, and different developed economies are seeing variations of the identical factor. The particulars differ from nation to nation, however the route doesn’t.
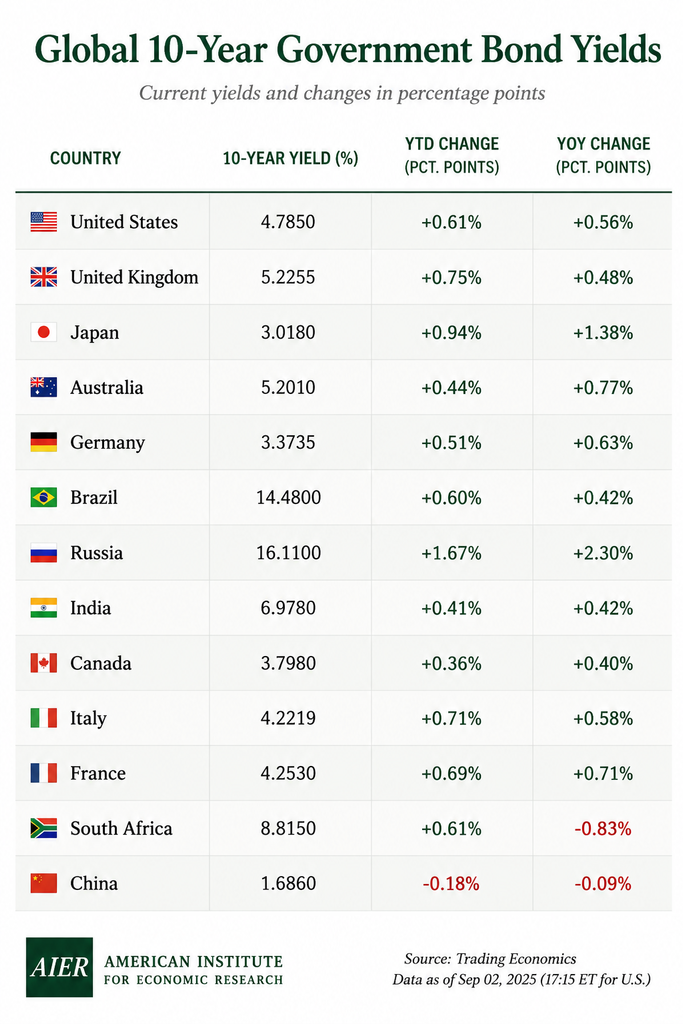
Oil costs and renewed inflation worries are a part of the reason, as is the rising risk that central banks must hold financial coverage restrictive for longer than markets have anticipated. However these are proximate causes. The larger story started a number of years in the past. Governments entered the COVID interval already closely indebted, then responded to the pandemic with monumental fiscal packages supported by terribly straightforward financial coverage. Central banks subsequently found that the ensuing inflation was neither particularly transitory nor straightforward to eradicate. Now, the consequently bigger money owed should be financed and refinanced in markets the place buyers as soon as once more demand compensation for inflation, period, and financial danger.
For america, the arithmetic turns into daunting pretty rapidly. Gross federal debt just lately handed $40 trillion, with roughly $32.3 trillion held by the general public. The weighted-average maturity of marketable Treasury debt is about 71 months, though roughly one-third matures inside the subsequent 12 months. So a 20-basis-point enhance within the 10-year Treasury doesn’t out of the blue reprice $32 trillion of debt. However the authorities doesn’t get to ignore increased charges, both. One thing on the order of $10 trillion of marketable debt should roll over inside a 12 months. In the meantime, Washington continues to borrow a whole lot of billions extra to finance new deficits.
A family analogy is beneficial right here, with one qualification. Think about an unlimited mortgage that resets in items moderately than all of sudden. A house owner with a fixed-rate mortgage doesn’t care very a lot if mortgage charges bounce tomorrow: he cares about when he has to refinance. The US Treasury is continually refinancing: some portion of the federal authorities’s monumental mortgage matures every single day.
We will already see that course of within the numbers. The common rate of interest on interest-bearing Treasury debt was about 3.32 % in January. By July it was roughly 3.45 %. 13 foundation factors seems like market noise, till the principal concerned is measured in tens of trillions of {dollars}.
Utilizing $32.3 trillion of publicly held debt as a tough base, each sustained 5-basis-point enhance within the authorities’s common financing value ultimately means about $16 billion extra in annual curiosity expense. Ten foundation factors means roughly $32 billion; 25 foundation factors, $81 billion; 50 foundation factors, $161 billion. A full share level works out to roughly $323 billion per 12 months — about what the US spends on veterans’ help. These are steady-state figures, not next-year price range estimates, as a result of the present debt has to reprice first. If roughly one-third of the debt rolls over inside twelve months, a 10-basis-point enhance would initially add one thing nearer to $10–11 billion to the annual value of the present debt, earlier than contemplating new borrowing.
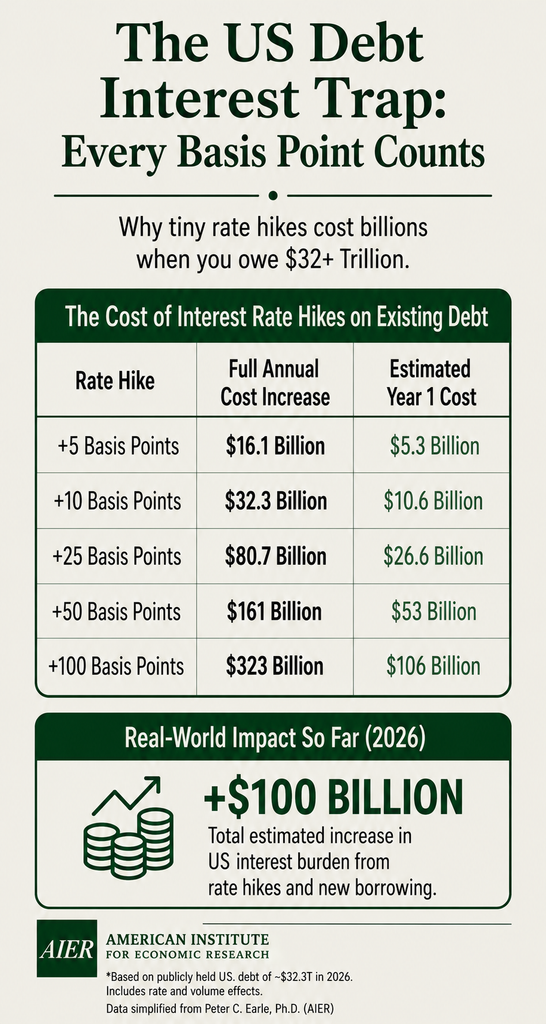
The change since January provides some thought of the dimensions concerned. If the 13-basis-point enhance within the US Treasury’s common rate of interest have been ultimately mirrored throughout right now’s publicly held debt, the annualized enhance could be round $42 billion. However the rate of interest is barely half of the issue: publicly held US Treasury debt has itself grown by roughly $2 trillion. Financing that further principal at round 3.5 % provides one other $65–70 billion yearly. Put the 2 collectively and the rise within the annualized curiosity burden is plausibly already within the neighborhood of $100 billion. That could be a run-rate calculation, not a declare about precise fiscal-year outlays, nevertheless it illustrates what occurs when each the quantity borrowed and the worth of borrowing rise collectively.
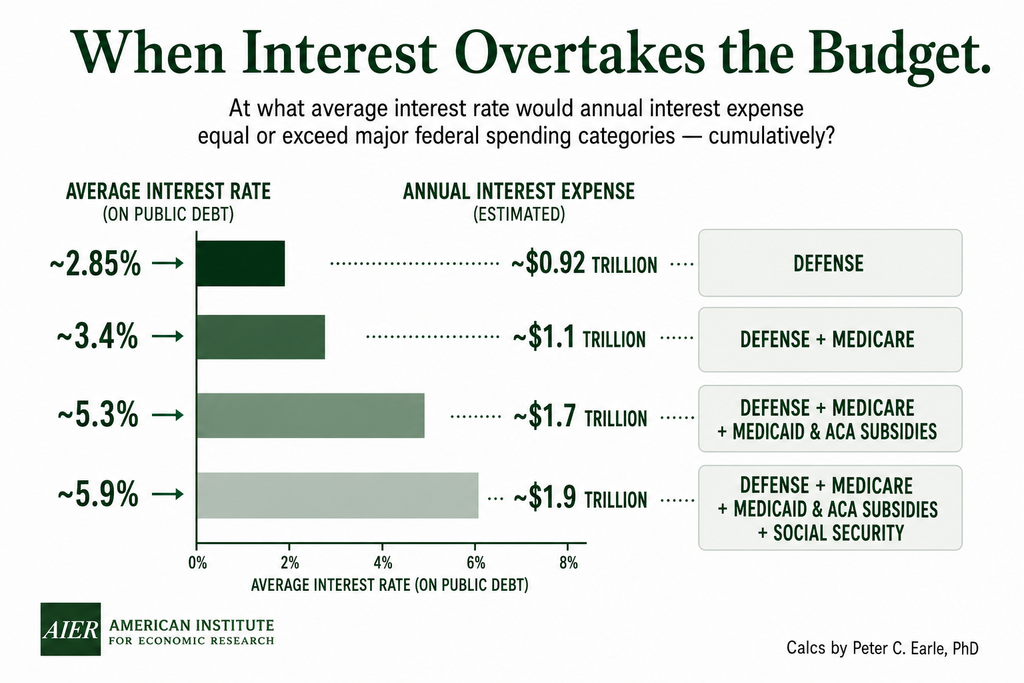
The price range implications are now not theoretical. The US Congressional Funds Workplace (CBO) tasks web federal curiosity expense above $1 trillion in fiscal 2026, in opposition to roughly $898 billion of protection spending. In different phrases, curiosity has already change into bigger than the protection price range. Medicare is roughly $1.1 trillion and Social Safety round $1.7 trillion, with Medicaid and ACA subsidies representing one other substantial expenditure.
There may be one other strategy to visualize the issue. Utilizing the identical $32.3 trillion debt base and intentionally simplified arithmetic, a median financing value round 2.85 % produces an curiosity invoice roughly comparable with protection spending. Elevate the efficient financing value and the curiosity burden turns into comparable with progressively bigger combos of protection, Medicare, Medicaid, and ACA subsidies, and ultimately Social Safety. That is an illustration, not a forecast: Treasury debt matures at totally different occasions, inflation-linked securities complicate the calculation, the federal government receives some curiosity earnings, and the debt inventory is not going to stay at $32.3 trillion. However none of these {qualifications} modifications the fundamental level: with this a lot debt excellent, surprisingly small actions in common financing prices translate into very giant quantities of cash.
That’s what makes the current bond selloff, and consequent rise in yields, important. For years, developed-world governments operated as if monumental debt shares and negligible financing prices may coexist roughly indefinitely. COVID pushed that experiment a lot additional. And with the return of persistent inflation, the worth of cash modified.
Bond markets are actually forcing governments to confront the change in circumstances. Yesterday’s deficit doesn’t disappear when the fiscal 12 months ends; it turns into a part of the debt that must be serviced tomorrow. Rising yields due to this fact work very similar to increased mortgage or bank card charges, besides that governments are refinancing obligations measured in trillions. As extra debt rolls over, the results migrate from buying and selling screens into nationwide budgets. Cash spent servicing the debt is cash that can’t be spent on protection, infrastructure, well being care or Social Safety with out some mixture of elevating taxes, borrowing nonetheless extra, or partaking in monetary parlor tips. Sooner or later, the bond market stops providing commentary on fiscal coverage decisions and begins imposing limits. We seem like approaching, if not on the early levels, of that section.
