

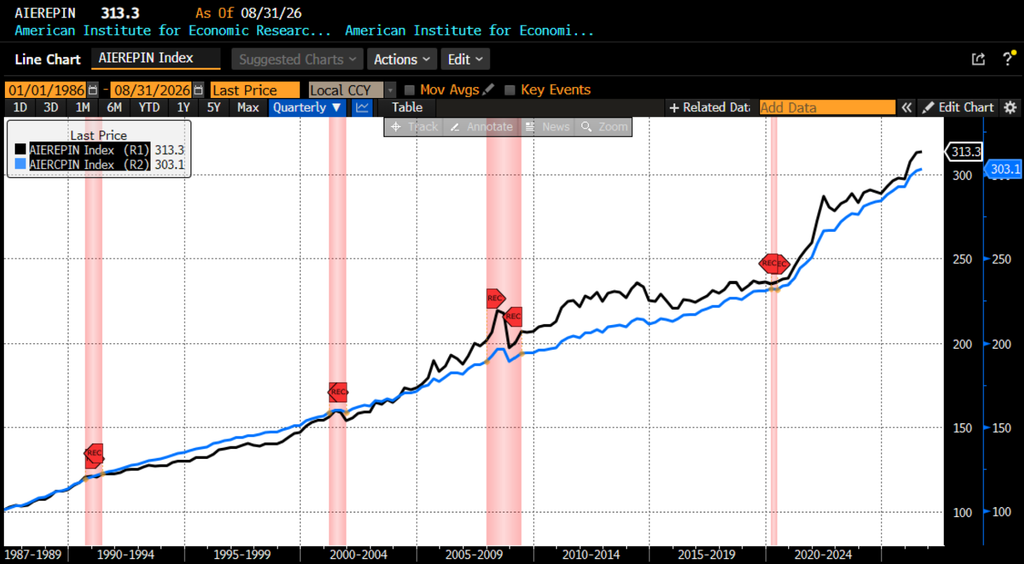
The AIER On a regular basis Value Index (EPI) rose 0.33 p.c in August 2026, reversing two consecutive month-to-month declines and registering its ninth-largest month-to-month advance of the previous two years. The EPI is now up 5.49 p.c yr so far and 5.59 p.c from August 2025, underscoring the persevering with affordability stress going through households regardless of the declines recorded in June and July. Beneath the headline enhance, worth actions have been comparatively balanced: 13 EPI classes turned dearer in August, ten declined, and one was unchanged.
The three largest will increase among the many EPI elements have been leisure studying supplies, up 2.92 p.c; motor gas, up 2.74 p.c; and buy, subscription, and rental of video, up 0.97 p.c. The most important declines occurred in nonprescription medicine, down 1.17 p.c; web companies and digital info suppliers, down 0.70 p.c; and admissions to films, theaters, and live shows, down 0.63 p.c. Due to its comparatively massive weight, motor gas was the principal driver of the general August enhance.
AIER On a regular basis Value Index vs. US Client Value Index (NSA, 1987 = 100)
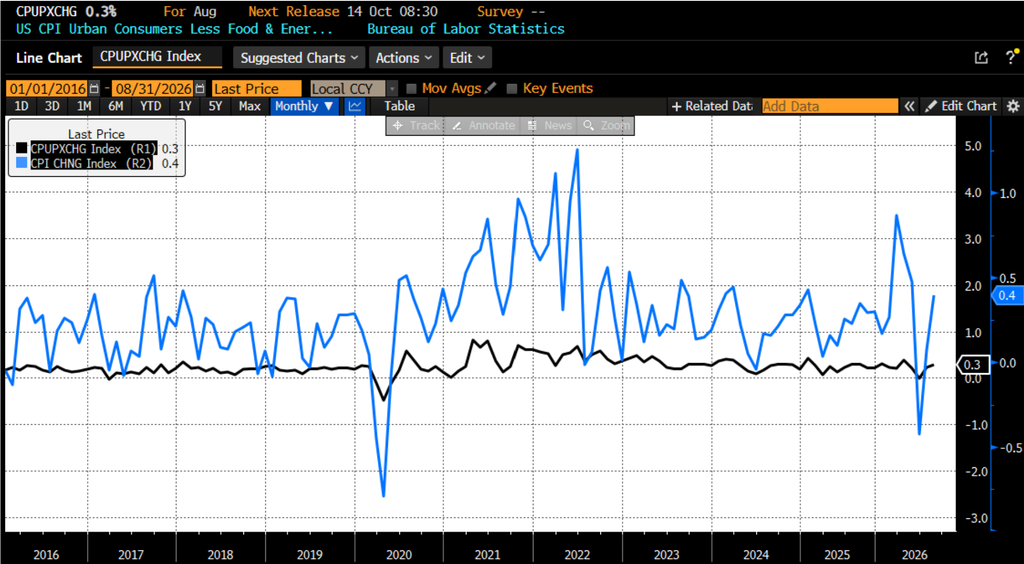
The US Bureau of Labor Statistics launched its August 2026 Client Value Index report on September 11, 2026. Headline CPI rose 0.4 p.c on a seasonally adjusted foundation, accelerating from 0.1 p.c in July. Core CPI, which excludes meals and vitality, rose 0.3 p.c after growing 0.2 p.c in July. The unadjusted headline index superior 0.3 p.c to 334.980.
Each the EPI and headline CPI moved increased in August, however the composition of their will increase differed. Our in-house EPI places better emphasis on items and companies customers purchase most incessantly.
August 2026 US CPI headline and core month-over-month (2016 – current)
Power drove a lot of the enhance in headline CPI. The vitality index climbed 2.1 p.c, reversing July’s 1.5 p.c decline. Gasoline surged 3.9 p.c and accounted for greater than one-third of the general month-to-month CPI enhance. The advance, nonetheless, was not shared throughout all family vitality classes: utility fuel service fell 1.1 p.c whereas electrical energy declined 0.2 p.c. That cut up helps clarify why motor gas dominated the August EPI enhance whilst its broader fuels and utilities element edged decrease.
Shelter rose 0.3 p.c, following unusually small will increase of 0.1 p.c in each June and July. Hire of main residence and homeowners’ equal lease every elevated 0.2 p.c. Lodging away from residence climbed 2.4 p.c, reversing its 2.8 p.c decline in July. Shelter and gasoline due to this fact changed the vitality weak spot and subdued housing prices that had restrained headline CPI the earlier month.
Meals elevated 0.1 p.c, matching its July tempo, whereas meals at residence was unchanged. 4 of the six principal grocery classes registered will increase. Dairy merchandise rose 0.3 p.c, nonalcoholic drinks superior 0.2 p.c, and meats, poultry, fish, and eggs elevated 0.1 p.c, partly reflecting a 2.9 p.c rise in egg costs. The opposite meals at residence class additionally elevated 0.1 p.c. Cereals and bakery merchandise have been unchanged, whereas vegetables and fruit declined 0.4 p.c, their third consecutive month-to-month lower. Lettuce costs fell one other 6.2 p.c after plunging 16.4 p.c in July.
Restaurant costs continued to outpace grocery costs: meals away from residence elevated by 0.3 p.c with full-service meals rising 0.4 p.c as limited-service meals have been unchanged. The distinction between secure grocery costs and one other enhance in dining-out prices was additionally evident within the EPI elements, the place meals at residence slipped fractionally however meals away from residence moved increased.
Core inflation broadened considerably in August. Communication costs jumped 2.3 p.c, airline fares rose 2.7 p.c, and training elevated 0.8 p.c. Used vehicles and vans gained 0.4 p.c, whereas new autos rose 0.3 p.c. Private care and family furnishings and operations additionally elevated. Offsetting declines have been concentrated in medical care and automobile insurance coverage. Medical care fell 0.2 p.c, dental companies dropped 0.6 p.c, and motorized vehicle insurance coverage declined 0.8 p.c. Hospital companies, physicians’ companies, prescribed drugs, attire, and recreation have been unchanged. Total, the figures point out that August’s firmer core studying prolonged past shelter alone, though a number of necessary service classes remained flat or declined.
August 2026 US CPI headline and core year-over-year (2016 – current)
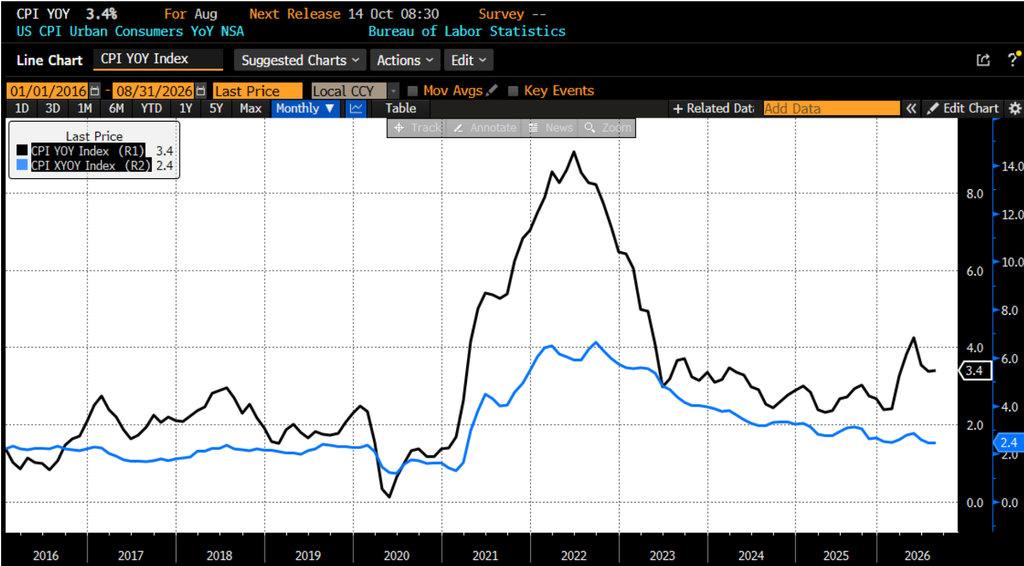
Shifting to the year-over-year benchmarks, in August 2026 headline CPI stood 3.4 p.c above its August 2025 stage, unchanged from the annual fee recorded in July. Core CPI eased from 2.5 p.c to 2.4 p.c, suggesting that the stronger month-to-month studying didn’t but translate into renewed acceleration over an extended horizon. Meals costs elevated 2.7 p.c over the yr, whereas food-at-home rose a extra reasonable 2.2 p.c.
Annual grocery inflation remained extremely uneven. Nonalcoholic drinks elevated 3.7 p.c, vegetables and fruit rose 3.2 p.c, cereals and bakery merchandise superior 2.6 p.c, and different meals at residence gained 2.4 p.c. Meats, poultry, fish, and eggs elevated just one.1 p.c, whereas dairy merchandise fell 0.3 p.c. Meals away from residence rose 3.4 p.c, once more exceeding grocery inflation. Full-service meal costs elevated 3.5 p.c, in contrast with 3.2 p.c for limited-service meals.
The vitality index was 16.3 p.c increased than in August 2026; that’s up from July’s 14.7 p.c fee. Gasoline costs climbed 27.4 p.c, with pure fuel and electrical energy rising a a lot smaller 4.4 p.c and three.8 p.c, respectively. August due to this fact reversed the short-term decline in gasoline whereas widening the hole between annual vitality inflation and the value will increase recorded in most different components of the buyer basket.
Outdoors the meals and vitality classes, inflation remained comparatively contained. Shelter rose 3.0 p.c over the yr, recreation elevated 2.7 p.c, medical care superior 1.6 p.c, and private care rose 3.8 p.c. Airline fares remained the foremost outlier, standing 23.4 p.c above August 2025 ranges. Against this, used vehicles and vans have been down 2.3 p.c, medical care commodities declined 2.7 p.c, and motorized vehicle insurance coverage fell 5.1 p.c. August thus mixed a renewed month-to-month enhance in gasoline and considerably firmer core costs with an annual core inflation fee that continued to ease.
The August 2026 CPI knowledge strengthens the case for a September fee enhance, however not just because one month got here in sizzling. Power clearly issues, and the Center East battle makes gasoline an particularly noisy sign, however worth stress was not confined to gas. That makes it more durable to dismiss the acceleration as an exogenous shock the Fed can safely look by. A central financial institution can fairly ignore a brief oil spike; broader worth stress is one other matter.
The bigger drawback is that the ultimate stage of disinflation could also be stalling above the Fed’s goal. Rate of interest coverage can restrain interest-sensitive sectors with out being sufficiently restrictive to impression the economic system as an entire, significantly if the impartial fee has moved increased. Policymakers ought to moreover not assume that each inconvenient enhance is short-term till confirmed in any other case. Financial coverage works with lengthy and variable lags, and several other August elements might reverse. However the expertise of the previous few years argues in opposition to giving persistent inflation the advantage of the doubt indefinitely.
At this level, inflation expectations make the Fed’s judgment extra consequential. Inflation needn’t develop into spectacularly “unanchored” to trigger financial disruption and hardship. If households and companies progressively start treating one thing nearer to three p.c as regular, they’ll construct it into wage negotiations, contracts, pricing choices, and asset allocation.
Pushing these expectations again down is a significantly dearer activity for the Fed. That creates an disagreeable tradeoff: elevating charges dangers overtightening an economic system already carrying costly credit score; holding regular dangers permitting 2 p.c to develop into an aspiration relatively than a goal. A quarter-point enhance due to this fact seems to be more and more like insurance coverage in opposition to ending the tightening cycle prematurely. A number of subsequent hikes would indicate one thing extra necessary: both the economic system’s nominal equilibrium has shifted upward, or financial coverage was by no means as restrictive as policymakers believed.

