

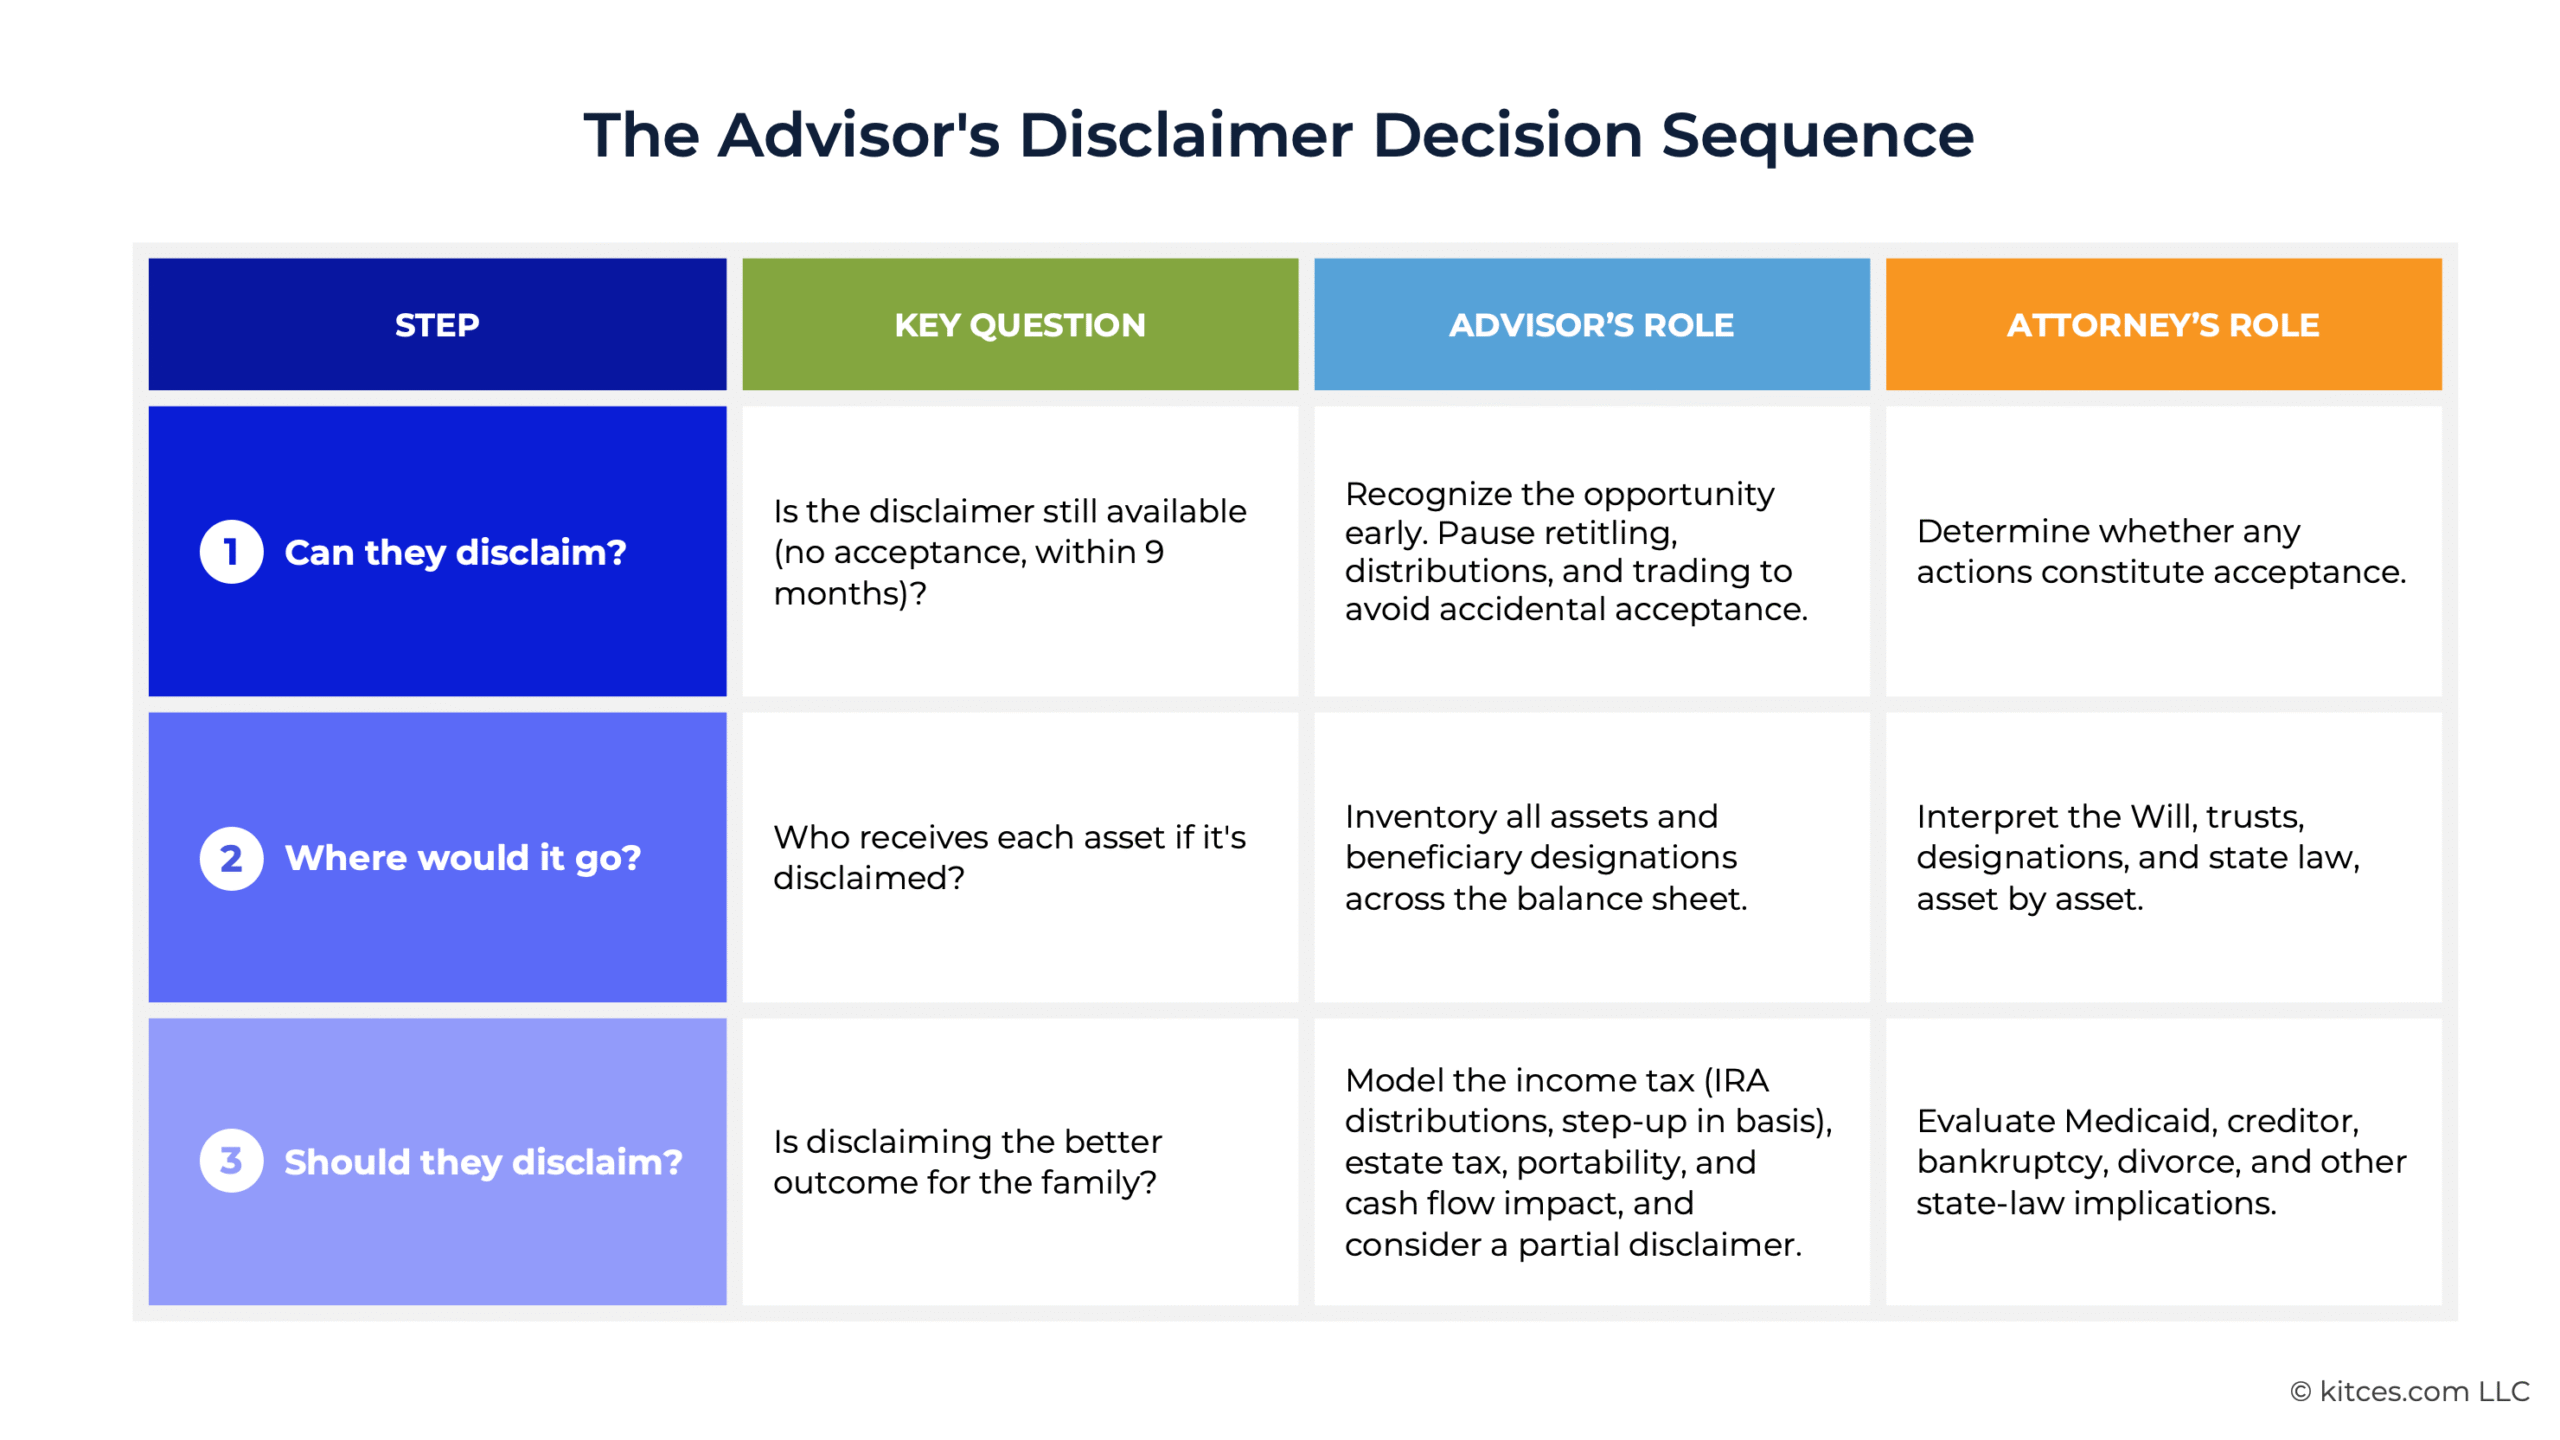
When a consumer sadly passes away, monetary advisors usually leap into motion. Partly it’s merely to offer good service and assist to a grieving household. In lots of instances, there’s additionally a enterprise curiosity to interact with subsequent era heirs and set up or deepen a relationship, within the hopes of constant to serve the household after the demise of the unique consumer. In both case, “proactivity” turns into the guideline of engagement. Besides the truth is that in terms of property planning eventualities, there may be really such factor as being too proactive… as a result of the actions of settling an property and distributing property can unwittingly negate the power of beneficiaries to subsequently have interaction in disclaimer planning.
On this visitor put up, David Haughton, an lawyer and VP of Engagement for Hargrove MSO, explores the advantages of disclaimer planning, and the way the distinctive necessities for executing a professional disclaimer, together with and particularly that the beneficiary not have “accepted” the inheritance, can run instantly opposite to conventional proactive service for property heirs.
The essential precept of executing a disclaimer is pretty simple: a beneficiary can select to not settle for an inheritance, and by doing so in a professional method, is just deemed as by no means having inherited the asset within the first place, permitting it to circulate as an alternative to the following (i.e., contingent) beneficiary. For these dealing with property tax publicity, that is far more interesting than merely receiving the inheritance and re-gifting it to a different beneficiary (and utilizing a portion of their very own lifetime present and property tax exemption). And even for the huge swath of these with out Federal property tax publicity, disclaimer planning can nonetheless be related in eventualities from shifting a pre-tax IRA to somebody with a extra favorable tax price to attract post-death Required Minimal Distributions, to shifting after-tax property to somebody who could obtain higher step-up in foundation remedy sooner or later.
Nonetheless, executing a professional disclaimer has a sequence of 4 very concrete necessities: 1) made in writing; 2) accomplished inside 9 months of the inheritance; 3) achieved earlier than accepting the inheritance; and 4) leads to property passing with out path by the disclaimant. The fourth requirement particularly is vital to acknowledge, as a result of it means the beneficiary can not really dictate the place the property will go, solely that they won’t obtain it… and the unique governing paperwork (e.g., the Will, or belief, or account settlement, or beneficiary designation) as an alternative determines who will obtain as an alternative.
The larger caveat, although, is the threerd requirement of a professional disclaimer: that the property not be accepted. Which is vital, as a result of distributing property to a beneficiary, paying earnings to them, and even the advisor taking motion to promote, liquidate, or in any other case handle the property on the path of the beneficiary, might be deemed acceptance. Such that whereas the usual guidelines for disclaimers enable as much as 9 months for completion, acceptance will instantly finish the time window, which implies advisors proactively making an attempt to interact next-generation heirs can unwittingly terminate the planning alternative.
Because of this, a finest follow for serving to heirs to settle an property is to know and establish as early as potential whether or not disclaimer planning may presumably be related, if solely to keep away from eliminating its potential altogether with “early” settlement of the property. Fortuitously, this doesn’t imply no actions might be taken within the account – the advisor can nonetheless handle at path of a fiduciary (e.g., a trustee) supervising the property. And sometimes advisors have the most effective holistic perspective to know whether or not a disclaimer is a related planning alternative (or not).
Finally, the important thing level is just to acknowledge that as a result of “acceptance” can terminate the window for executing a professional disclaimer, advisors in any other case participating in proactive service to assist a grieving household or to ascertain a relationship with subsequent era heirs should be cautious to not unintentionally finish a disclaimer planning alternative. Particularly recognizing that disclaimers aren’t only a matter of Federal property tax planning (for less than a small subset of ultra-high-net-worth shoppers with property tax publicity); earnings tax penalties, from IRA distributions to step-up in foundation alternatives, imply disclaimer planning has potential for a variety of consumer circumstances. So long as the window stays open lengthy sufficient to decide whether or not it’s proper for any specific inheritor!
 |
And if you wish to go deeper on this matter, hear instantly from the creator on the Monetary Advisor Technician podcast. |


