


Why is it that two debtors who look a lot alike could be provided very completely different charges when making use of for a bank card? In a latest paper, we tackle this query by inspecting how the speed provided modifications when the lender’s funding price falls. Information on 14 million newly issued playing cards present that when a lender’s funding prices decline, the lender passes much less of that decline on to the provide fee when it holds a big market share. That’s, two debtors with related credit score scores and incomes borrowing from the identical lender can see noticeably completely different rates of interest on the bank card they’re making use of for.
Credit score Card Lenders Serve Many Totally different Markets
Bank card lenders don’t compete in a single, undifferentiated nationwide market. They aim gives and design merchandise for specific forms of debtors. Business stories, regulatory steerage, and educational analysis doc segmentation by credit score danger, revenue, card traits, and acquisition channel. A main borrower making use of on-line for a general-purpose, non-co-branded card belongs to a unique market than a subprime borrower accepting a preapproved provide for a general-purpose, co-branded card. The identical lender can have a big share in one among these markets and a small share in one other.
Guided by these documented practices, we outline 960 nationwide markets by combining 4 credit-score teams, card and product sort, acquisition channel, and revenue teams based mostly on the borrower’s ZIP code. In our information, lenders function in about 200 of those markets on common in a given week. Inside every market, we outline a lender’s share as its income relative to whole income in that market.
Charges Monitor Lenders’ Market Place
We start by asking whether or not the charges debtors obtain are associated to their lender’s share of the market. To take action, we use confidential account-level information collected by the Workplace of the Comptroller of the Forex (OCC). The information report annual share charges (APRs) and detailed borrower and card traits for newly issued accounts. We type teams of accounts finely matched on noticed borrower and product traits, reminiscent of revenue, credit score rating, and bank card sort, in order that the accounts inside any group look a lot alike.
The chart under plots the common APR in every group (vertical axis) towards the common market share of the lenders issuing these playing cards (horizontal axis). The relation is clearly optimistic, with a correlation of 54 %: increased lender market shares are related to increased APRs. Within the companion paper, we present this isn’t pushed by variations in traits throughout debtors (for instance, default danger) or throughout banks (for instance, lending prices); market shares stay strongly associated to charges as soon as these traits are accounted for.
Credit score Card Charges Are Tied to a Lenders’ Market Share
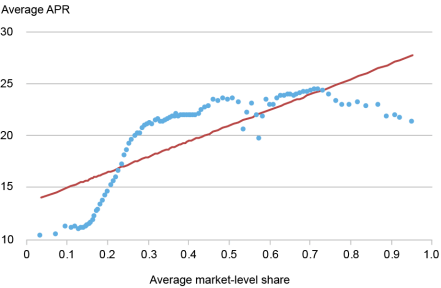
Notes: Every level is a gaggle of accounts matched on revenue, credit score rating, card sort, and different borrower and product traits. The vertical axis is the group’s common APR; the horizontal axis is the common market share of the lenders issuing these playing cards.
Group averages, although, can nonetheless differ for causes apart from market positions. As an illustration, teams range in default danger, and riskier debtors pay the next APR. For that purpose, within the companion paper we study variations in APRs inside every group, the place credit score rating, revenue, and bank card sort are held fastened by development, so variations in charges inside a gaggle can’t be attributed to them. We discover that, even amongst debtors and playing cards that look very related within the information, variations in APRs are bigger when variations in lenders’ market positions are bigger.
Whereas these patterns are suggestive, they continue to be descriptive. Lenders might maintain massive shares in markets that differ in methods we don’t observe, and people variations may additionally have an effect on APRs. We subsequently flip to a extra direct take a look at of lender conduct.
What Occurs When Lenders’ Funding Prices Fall?
Most variable-rate bank card accounts are tied to a contractual benchmark after they’re issued, so modifications in APRs on present accounts are partly mechanical. We as a substitute examine accounts at origination, when the lender chooses the preliminary APR, together with its unfold over that benchmark.
Our baseline evaluation focuses on January 2008 because it had one of many largest unanticipated actions within the federal funds fee. For added occasions by way of 2019, we complement this information with comparable data collected by the Federal Reserve. Collectively, the 2 datasets cowl roughly 14 million newly issued accounts and report their origination dates, APRs, and detailed borrower and card traits.
When an sudden change within the risk-free fee strikes lenders’ price of funds, we examine accounts issued shortly earlier than and shortly after the change. We strip out APR modifications widespread to all of a lender’s markets and regulate for noticed variations in debtors and merchandise, together with credit score rating, revenue, and card sort. What stays is a comparability of the identical lender, across the similar sudden change within the risk-free fee, throughout markets the place its share differs. We confer with the ensuing measure because the adjusted APR.
Take into account a lender that has a big share in a single market however a small share in one other, and suppose the risk-free fee declines by 25 foundation factors. If the lender handed the decline by way of totally in each markets, APRs on newly issued accounts would fall by 25 foundation factors in every. As an alternative, suppose it cuts APRs by 15 foundation factors within the high-share market and by 20 foundation factors within the low-share market. The distinction between these responses measures how a lot much less of the decline is handed by way of the place the lender has a bigger share.
Lenders Go By Much less The place Their Shares Are Bigger
Our clearest proof comes from January 2008, when the federal funds fee fell unexpectedly by 25 foundation factors. We examine how the identical lender adjusts its charges in its high-share markets versus its low-share markets, within the weeks proper across the sudden fed funds fee change. The vertical axis within the chart under exhibits the distinction within the share change in adjusted APRs between markets the place a lender has a big share—outlined as being within the prime 30 % of the distribution of market shares—and that very same lender’s lower-share markets. A damaging worth is proof that adjusted APRs fall by a bigger share within the lender’s lower-share markets than in its high-share markets. The horizontal axis exhibits the variety of weeks (denoted h) earlier than or after the unanticipated fed funds fee motion, with the vertical dotted line being the week of the occasion. So, h=-1 considers playing cards issued one week earlier than the occasion, whereas some extent at week h=1 considers playing cards issued one week after the occasion.
Credit score Card Lenders Go By Much less in Markets The place Their Shares Are Bigger
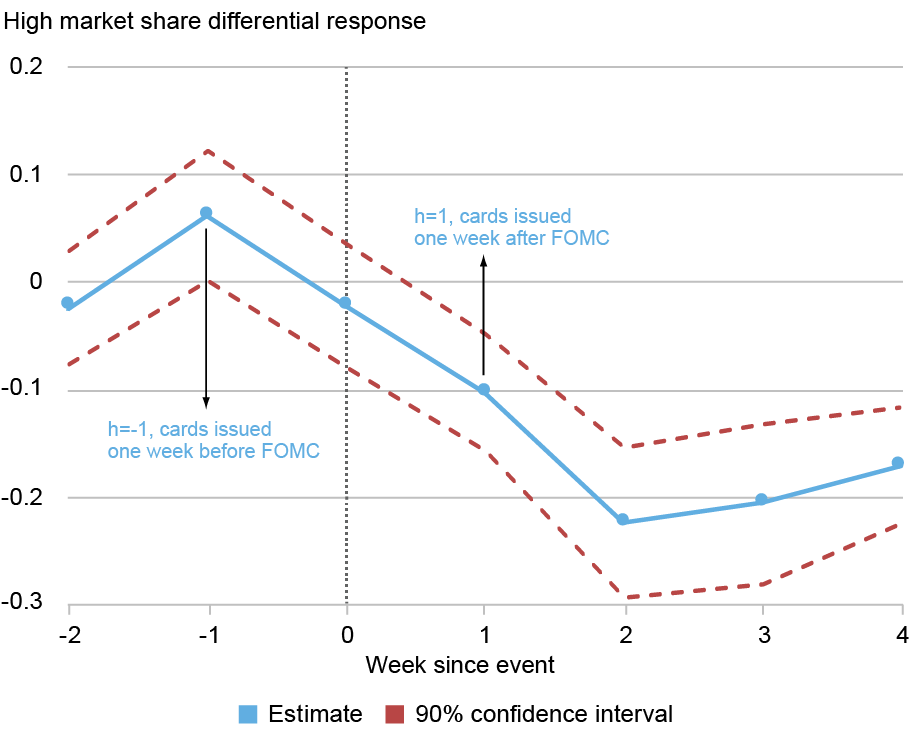
Notes: The chart exhibits the differential response of adjusted APRs on newly issued playing cards in a lender’s high-share markets relative to its lower-share markets. Unfavorable values point out that APRs fall much less in high-share markets. The vertical line marks the sudden change within the risk-free fee. FOMC is Federal Open Market Committee.
The chart exhibits that at two weeks after the Federal Open Market Committee occasion, the pass-through is 20 % decrease in high-share markets than in low-share markets served by the identical lender. To place that in perspective, for a mean adjusted APR of 10 %, the lender would minimize the borrowing fee by 2 share factors much less if it has a excessive share than if it has a low share, per 1 share level change within the risk-free fee.
Put in another way, amongst debtors with related noticed traits taking out related playing cards from the identical lender, these in high-share markets have much less of the decline in funding prices handed by way of to the APR they’re provided. The end result isn’t distinctive to January 2008. It stays sizable after we mix the massive sudden modifications within the risk-free fee over the remainder of 2008. After we embody all qualifying will increase and reduces from 2008 by way of 2019, the estimate is smaller however stays statistically important.
Taking Inventory
Excessive bank card charges, focus, and fee dispersion could also be in line with market energy, however none alone reveals how lenders set costs. We as a substitute examine how the identical lender adjusts APRs throughout its personal markets after a change in its funding prices. We discover that lenders cross by way of much less the place their market shares are bigger, a sample that seems throughout occasions and borrower teams. Debtors with related noticed traits can subsequently obtain completely different APRs from the identical nationwide lender relying on that lender’s share of their specific market.
Kyle Herkenhoff is a marketing consultant on the Federal Reserve Financial institution of Minneapolis and an affiliate professor of economics on the College of Minnesota.

Juan M. Morelli is a analysis economist within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
How one can cite this publish:
Kyle Herkenhoff and Juan M. Morelli, “How Market Place Shapes Credit score Card Curiosity Charges,” Federal Reserve Financial institution of New York Liberty Avenue Economics, November 4, 2026, https://doi.org/10.59576/lse.20261104
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the writer(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the writer(s).
