


The favored picture of a FIRE practitioner is somebody consuming rice and beans, clipping coupons, and driving a automotive older than their children. All luxuries are shunned as a way to develop their wealth as massive as doable to interrupt free sooner. FIRE people are low cost and will get pleasure from life extra critics say.
There’s some fact to it. To retire early, you normally want to save lots of aggressively for 10 to twenty years. Alongside the best way, you develop frugal habits that assist you to recognize extra of what you’ve. You might even begin treating investing as an entertaining expense that motivates you to save lots of much more.
After 10+ years of aggressive frugality and a 50%+ saving charge, it’s extremely onerous to vary your methods when you break away from the company grind. I used to work late till 7pm on a regular basis so I may eat free cafeteria meals. Then I would take some fruits and snacks out so I may save for breakfast the following day. So low cost.
Nonetheless, in the future, you would possibly uncover your monetary habits are a lot totally different from the narrative you have been telling your self for years. As a substitute of pondering you are low cost after FIRE, you are really spending aggressively.
I actually did. And it made me notice a budget FIRE stereotype is usually fallacious.
Simply Purchase The Automobile Already
After I wrote about the hidden price of shopping for a brand new automotive, a reader left a drive-by remark: “Simply purchase the automotive already. You have been speaking about this an excessive amount of.”
That is not occurring. Within the submit, I shared that I scraped the entrance proper facet as a result of I did not see a motorbike rack protruding three toes. My first response wasn’t anger. It was reduction. There is a fantastic feeling in not caring when an 11-year-old automotive will get one other battle scar.
Nonetheless, his remark received me pondering. Am I being overly low cost, or perhaps a little masochistic, by driving an previous automotive with issues when I haven’t got to?
My conclusion isn’t any. The pleasure of not caring whether or not my automotive will get scratched or dinged outweighs the enjoyment of driving one thing new in a bustling metropolis stuffed with accidents. New costly stuff simply offers me extra stress.
Then I checked out my spending on issues that are not mandatory for survival. The whole is much past what a stereotypical low cost FIRE practitioner would spend. And I’ve a sense if you do a spending audit, you will uncover comparable issues.
The Alternative Price Of Early Retirement Is Huge
Right here is the important thing level relevant to ALL individuals who FIRE.
FIRE practitioners depart monumental sums of cash on the desk to do one thing else. From a monetary standpoint, they’re paying an enormous alternative price to sit down on a park bench at 11 a.m. on a Wednesday and browse.
So by default, FIRE practitioners aren’t low cost as soon as they really retire. And the extra they made at their day jobs, the much less low cost they’re, as a result of the chance price is larger.
In 2012, I used to be paid a $250,000 base wage plus a discretionary bonus that ranged from $0 to $500,000. By strolling away, I primarily spent all of it that 12 months to be free from company politics, enterprise journey, shopper stress, and conferences.
Then I spent it once more the following 12 months. And the 12 months after that. Over 14 years, that’s over $3.5 million in forgone base wage alone, earlier than any raises. Add bonuses, and we’re speaking about over $7 million in forgone compensation.
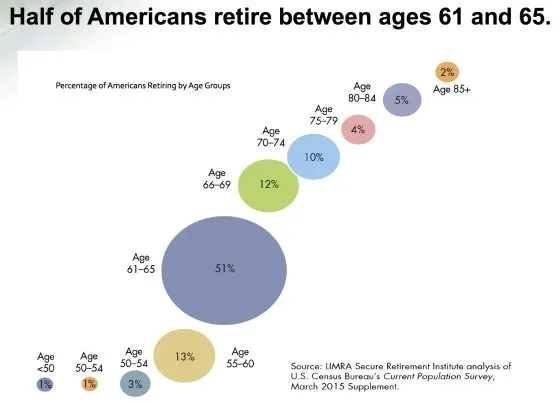
Most individuals are prepared to promote their soul for cash till age 61. Even when their firm is harming society, or may probably kill all of humanity, it may be extraordinarily troublesome to stroll away from a fats payday.
Paying Full Value For Healthcare
And it’s not simply the misplaced paycheck. While you depart, you additionally lose your employer’s backed medical health insurance.
We pay about $3,000 a month for unsubsidized healthcare for our household of 4. That’s $36,000 a 12 months for protection I used to get for a fraction of the worth.
Selecting to not proceed working is among the most costly purchases you may make.
FIRE Practitioners Are Society’s Largest Spenders
So opposite to in style perception, anybody who really takes the leap and FIREs is a giant spender, not an affordable or frugal one.
Conversely, anybody who says they’re FIRE and retains working at a job they dislike for yet another 12 months just isn’t. They’re seemingly simply fooling themselves. As a result of on the finish of the day, your monetary independence quantity just isn’t actual should you do nothing to vary your life.
I hope this elementary level is evident. In the meantime, something a FIRE practitioner spends past the fundamentals essential to survive must also be considered.
Let me share some examples, that are totally different for each FIRE individual. Nonetheless, listed here are seemingly the 2 largest discretionary life bills to think about.
A Home Or Residence You Do not Want
In case you lease or purchase a home that is bigger than a studio for your self and a companion, or a two-bedroom if in case you have a few children, you are spending past what’s mandatory.
Our largest discretionary expense is the home we purchased in 2023. It price about 75% greater than the home we purchased in 2020 firstly of the pandemic.
We did not want one other bed room or two extra bogs. We additionally did not want an enclosed entrance yard for our kids to play exterior safely. Nor did we want a bigger lot with a view of the Golden Gate Bridge.
However I wished it, and I satisfied my spouse it was a good suggestion. She was joyful in our previous home.
We may simply save about $50,000 a 12 months in property taxes, upkeep, and insurance coverage if we had stored our previous home. However the finest time to personal the nicest home you possibly can afford is when you’ve essentially the most heartbeats at residence. As soon as the youngsters are gone, we will all the time downsize.
Anti-cheap FIRE spending: $50,000 a 12 months extra on housing
The Children You Love
Some within the FIRE and private finance neighborhood swear off children as a result of they’re costly and require an incredible period of time, cash, and energy to. Children can crimp the FIRE way of life. You may not journey as freely or do no matter you need on daily basis.
As a substitute of going to meals, issues, and experiences for your self, numerous your passive funding revenue will get sopped up by little people who typically do not understand how good they have it. I get it.
Elevating a toddler in an costly coastal metropolis can simply price $1 million from start by means of age 18. Add one other $400,000 for school in immediately’s {dollars}, and elevating a child can price roughly $1.4 million by means of faculty commencement.
After all, households can spend far much less. Name it “solely” $300,000 by means of age 18, or $500,000 by means of faculty. However that is nonetheless some huge cash going to somebody aside from you.
No person wants children. However many people need children. As soon as we had one, we thought children have been so particular that we had one other. If I may rewind time to age 30, I’d slap myself foolish and shoot for one or two extra. That stated, being an older mother or father has its advantages, resembling extra maturity and monetary means.
Anti-cheap FIRE spending on children dwelling bills resembling meals, clothes, classes, journey: $16,000 / 12 months
Extra Pointless FIRE Bills That Aren’t Low-cost
Residing in a nicer residence and having children aren’t outrageous excesses. Some would argue they’re foundational wishes. We spend extra time at residence than wherever else, and procreating is type of mandatory for the survival of our species.
However FIRE people additionally spend lots on issues which might be completely pointless. Like all issues, there are ranges to this.
Listed here are two extra of mine, which can appear downright wasteful to some. However regardless of my short-term liquidity crunch, I’m not slicing again but, particularly after realizing how onerous it’s to spend cash if you’re previous.
Impartial Grade Faculty Tuition
Considered one of my largest educational regrets just isn’t taking Mandarin extra significantly rising up. I lived in Taipei for 4 years whereas my mother and father have been stationed on the American Institute in Taiwan, and I nonetheless blew it. Then I wasted seven years of Spanish from center faculty by means of highschool.
I’d pay a fortune to be fluent in a second language. So as a substitute, I’m paying a fortune for my children to have the prospect I squandered.
We ship each kids to a language immersion faculty, which prices about $46,000 a 12 months per little one. It’s some huge cash. I’m a product of public highschool, faculty, and enterprise faculty, and I’m nonetheless a believer in public faculties. I typically wonder if we’re making the appropriate name.
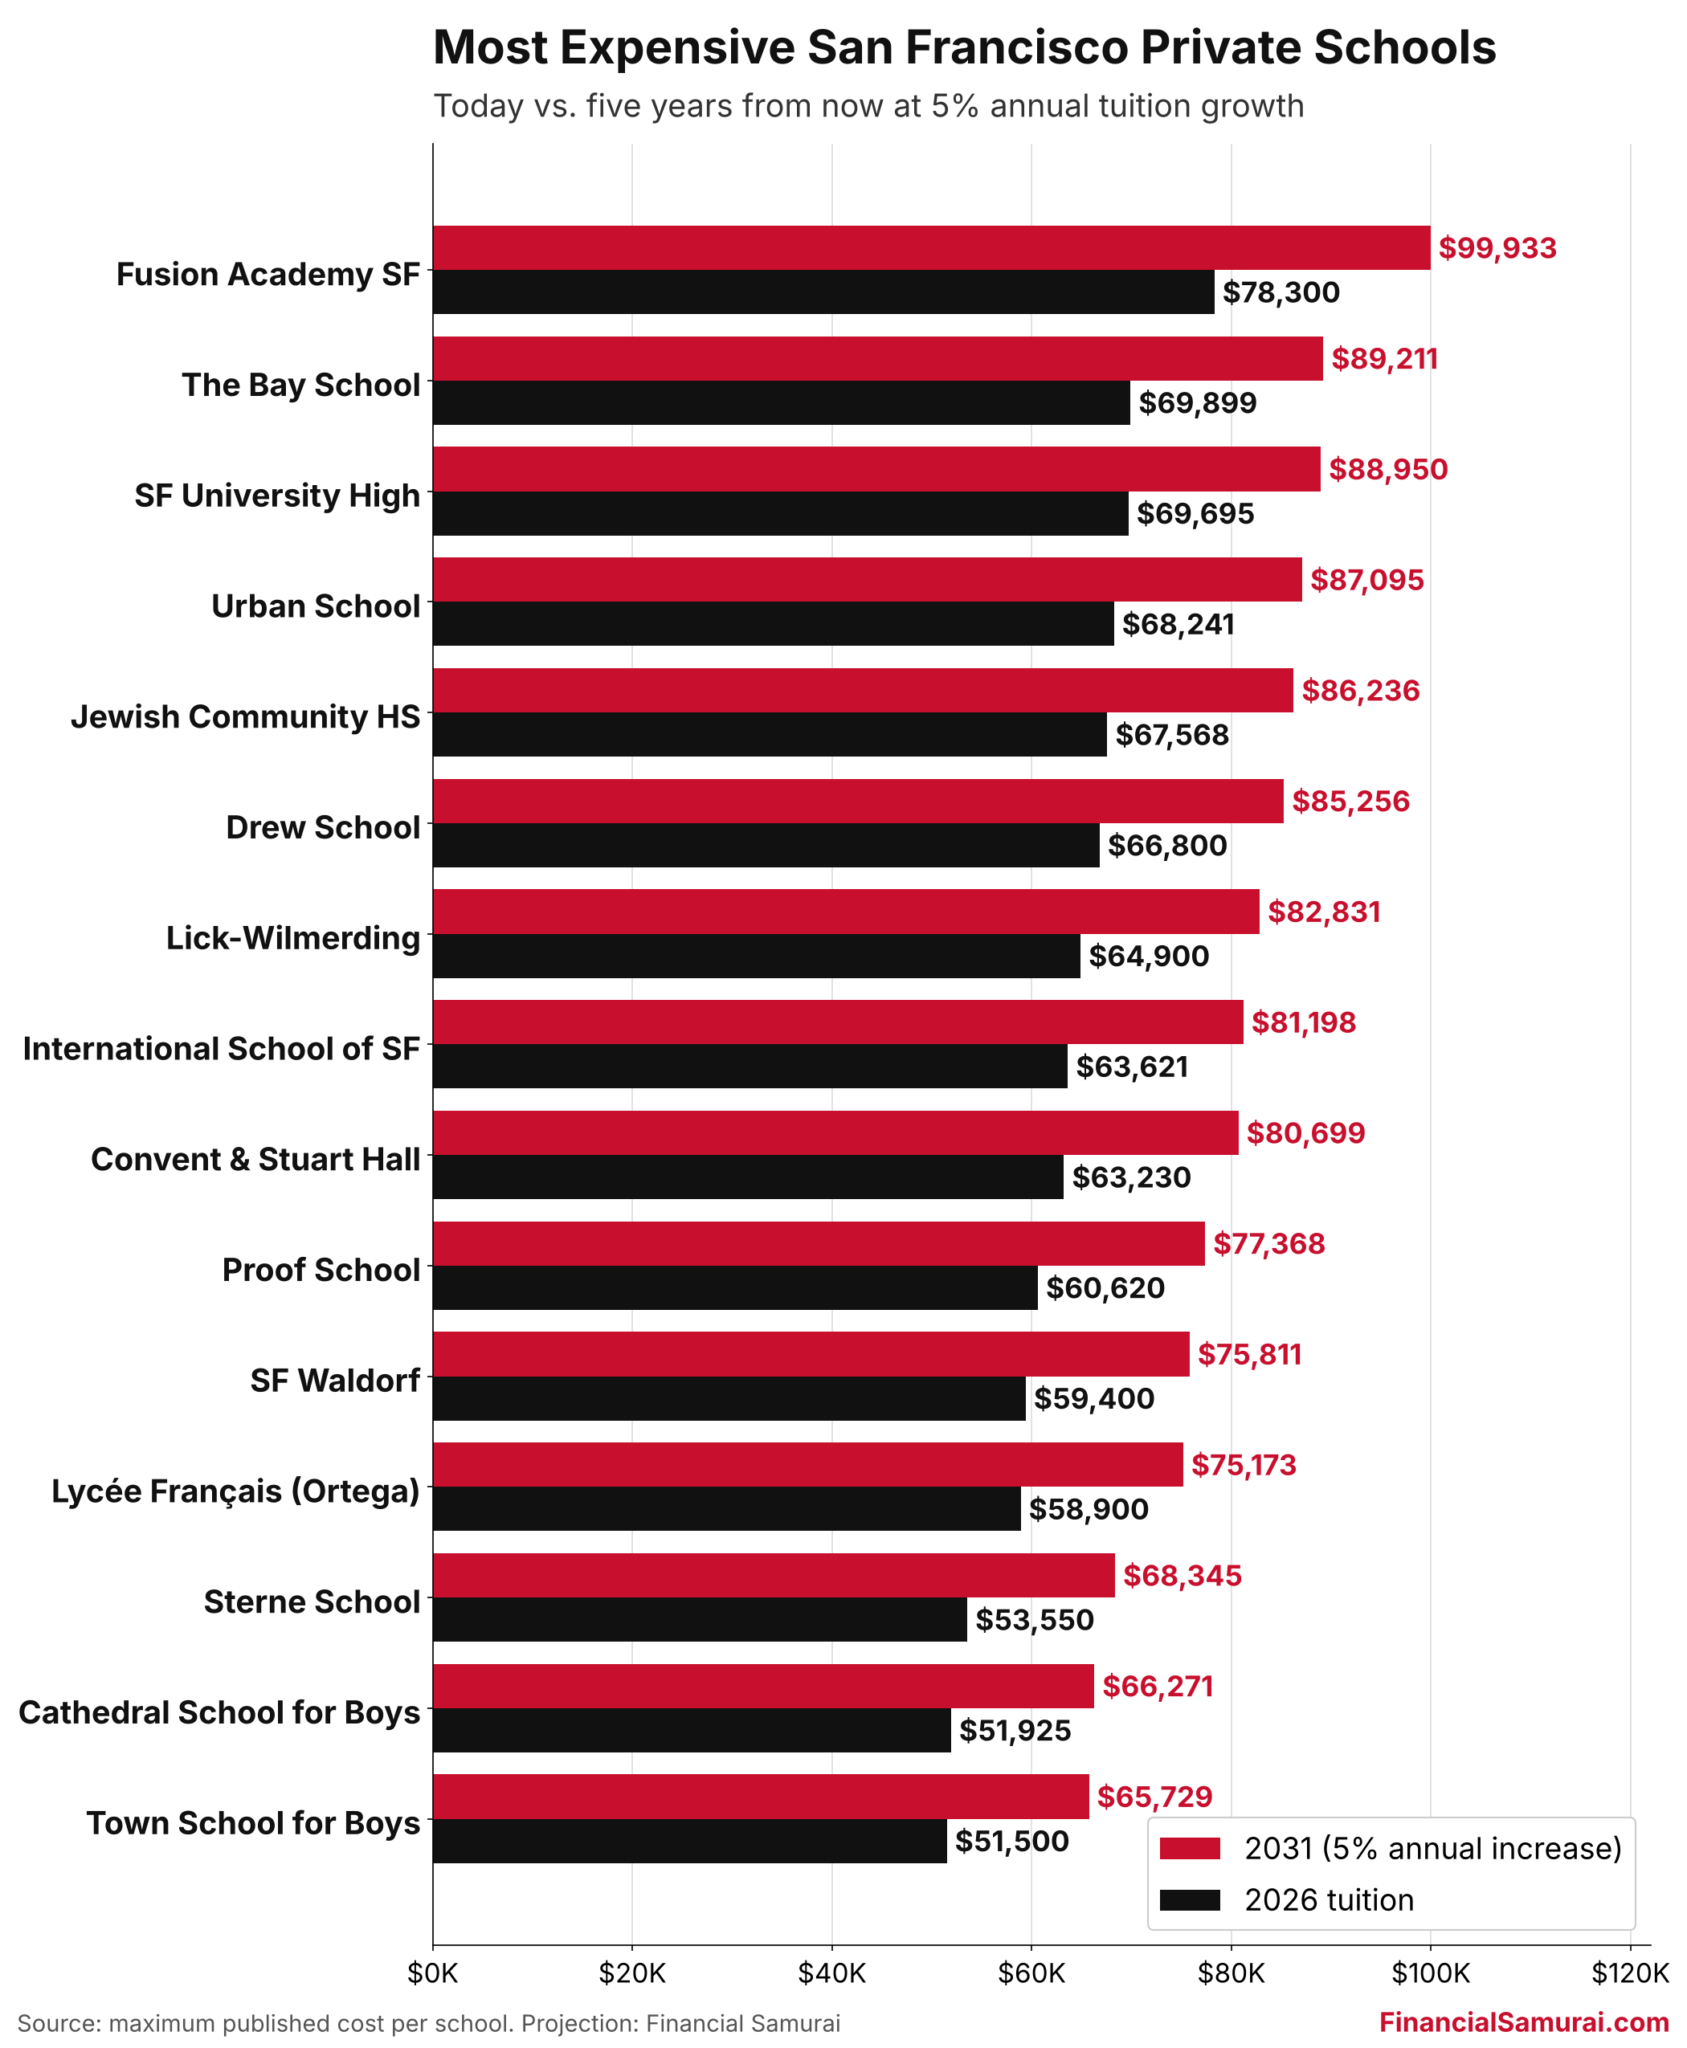
A frugal FIRE mother or father would ship their children to public faculty and hand them a free language app. A very frugal one would possibly even homeschool, which we did for 18 months throughout the pandemic. I can affirm it’s not free. It simply prices you your persistence as a substitute of your cash.
Perhaps this tuition is simply costly remedy for not learning tougher as a child.
Anti-cheap FIRE spending on training: ~$92,000 a 12 months
Ordering Meals Supply That Buys Again Time
Residing in San Francisco, we’re spoiled with nice meals. And since lots of the supply firms began right here, getting it delivered to your door is a breeze.
I like to eat. It is best to see my intestine, which is why I joined a Dad Bod Problem. I additionally love saving time and not slicing my fingers whereas slicing onions.
So we’ve ordered supply a few occasions per week for over 10 years. We may get monetary savings grocery buying and cooking extra. However we’d relatively spend that point elsewhere. Clearly not on the fitness center.
Anti-cheap FIRE spending on further meals: ~$1,000 a month
Including Up The Not-So-Frugal FIRE Tally
This is roughly what our pointless spending seems like annually.
| Discretionary Expense | Estimated Annual Price |
|---|---|
| Nicer home (further property tax and upkeep) | $50,000 |
| Impartial faculty for 2 children | $92,000 |
| Children actions, journey, garments, glasses, healthcare | $16,000 |
| Meals supply and eating places | $12,000 |
| Complete | $170,000 |
Add the $250,000+ in forgone base wage, and we’re spending over $420,000 a 12 months on a way of life that strangers would possibly name low cost. All as a result of I drive an previous automotive.
Right here’s the kicker. Even with all this pointless spending, our excesses nonetheless price lower than the bottom wage I walked away from. And that assumes my base wage by no means went up after 2012, which is unlikely.
Oh, and I haven’t even included my spouse’s forgone wage.
Due to this fact, the mere act of retiring early and giving up a paycheck isn’t low cost. It’s prodigal.
The Low-cost FIRE Narrative Wants Retiring
Positive, I drive an previous automotive and fly economic system. However that’s as a result of I really feel silly shopping for new or paying up for first-class.
The farthest I normally fly is 5 hours to Hawaii. Paying $1,000+ extra for a premium seat feels ridiculous once I match simply high quality in economic system. That’s $200+ an hour for 5 extra inches of legroom and a seat as much as six inches wider. All so I can write a submit, eat a meal, watch a film, and take a nap. Issues I can already do comfortably in coach.
Spending nothing on belongings you don’t care about isn’t low cost. It’s understanding what you worth.
So I’m declaring a budget FIRE narrative useless. FIRE practitioners, particularly the Fats FIRE crowd, are a few of the largest spenders in society. We may maintain grinding to make more cash. However we don’t, as a result of we worth our time extra.
Giving up all that revenue yearly to journey, create, or spend extra time with our kids is dear. However we wouldn’t have it every other approach.
Reader Questions
- In case you added up your forgone wage plus your discretionary spending, how a lot does your model of economic independence actually price annually?
- Which “pointless” expense would you by no means surrender, even when it delayed your early retirement by 5 years?
- Do you assume FIRE practitioners are frugal, or are they merely spending their cash on time as a substitute of issues? Maybe the stereotype refers to people who find themselves Coast FIRE, Barista FIRE, or Lean FIRE as a substitute.
In case your aim is to construct sufficient wealth to purchase your freedom, try my USA Immediately bestseller Millionaire Milestones: Easy Steps To Seven Figures. It’s going to be the simplest and finest private finance e book you will ever learn.
Subscribe to The FS Free Weekly Publication
If somebody forwarded you this submit, be a part of 60,000+ readers and join the free Monetary Samurai e-newsletter right here. It’s also possible to get my posts in your inbox as quickly as they’re printed, ad-free for the primary few hours, right here. I have been writing about FIRE since 2009.

