

The repo market within the U.S. is a mosaic of segments with distinct members and numerous settlement and clearing practices. Why do massive money lenders usually settle their trades by means of a third-party agent? Why does the interdealer market clear by means of a central counterparty? Why do levered buyers favor bilateral trades? Within the second publish of this sequence, we comply with the money because it navigates by means of repo markets to higher perceive the prices and advantages that form the present market constructions.
What’s Distinctive about Repos?
In a repurchase settlement or repo, one occasion sells a safety (ceaselessly U.S. Treasuries) in change for money with the promise to repurchase the safety at a later date (normally the subsequent enterprise day). As we mentioned in yesterday’s publish, members usually use repos to take a position money and earn a return, equally to federal funds or Eurodollar contracts. Nonetheless, repo markets are considerably bigger than different short-term cash markets: For instance, day by day whole quantity throughout the federal funds, Eurodollar, and chosen deposit markets hovers round $200 billion, whereas current estimates of the measurement of repo markets within the U.S. exceed $13 trillion. What makes repo contracts distinctive?
The position of collateral is a key function distinguishing repos from many different cash market transactions. The presence of collateral expands the motives for getting into repo transactions, attracting a broader set of members. As an example, hedge funds might enter a repo to safe particular securities, whereas cash market funds (MMFs) see the securities as a way to scale back the danger of their funding.
Taken collectively, the richness of counterparties and motives incentivizes customization within the execution, clearing, and settlement of repo contracts. Concretely, members not solely consider the phrases of the transaction itself (for instance, the speed, maturity, kind of collateral, and haircut), additionally they assess the processes concerned within the verification of the commerce particulars (clearing) and the ultimate switch of the possession of securities from the vendor to the client in change for money, together with valuation, margining, and custody providers (settlement). These processes contain prices arising from operational, authorized, and counterparty dangers. As members cope with these prices in another way, a number of repo segments have emerged, in reflection of how numerous entities consider these trade-offs. We describe these market preparations subsequent.
Intermediation Is Key in Repo Markets
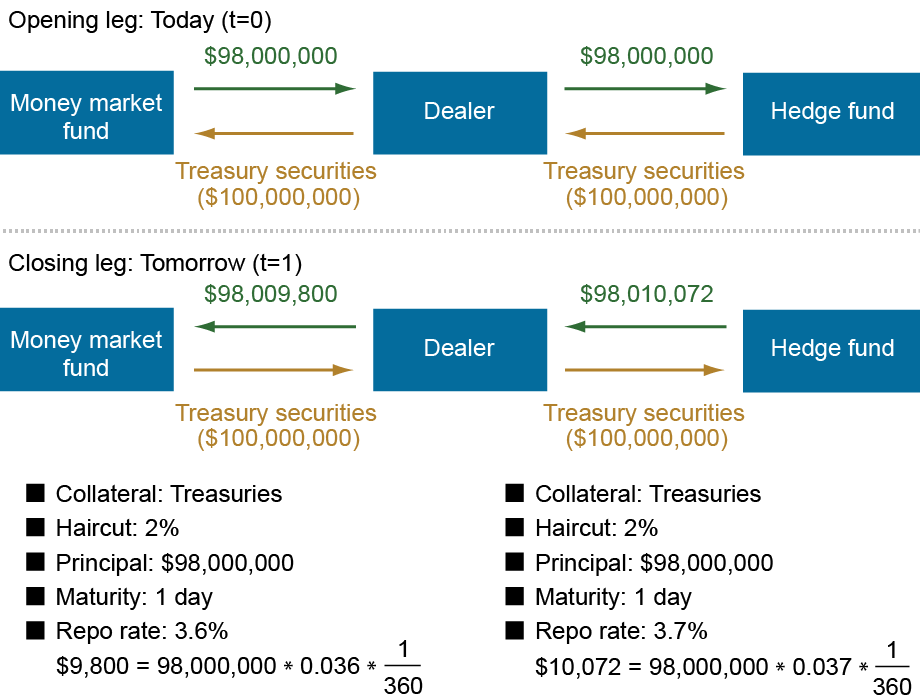
How do debtors and lenders discover appropriate counterparties in an over-the-counter market with many distinct units of members and buying and selling motives? Repo markets have addressed this query by means of the emergence of sellers who act as intermediaries between the last word debtors and lenders. Sellers are the hubs by means of which repo markets stream: they create worth by intermediating money and collateral in change for compensation for counterparty, collateral, and, to a lesser extent, maturity transformation danger (OFR 2024). As an example, because the stylized diagram under exhibits, a vendor might enter a repo—borrowing money—with a extra creditworthy counterparty (for instance, a authorities MMF) and enter a reverse repo—lending money—with a riskier one (for instance, a levered hedge fund), incomes the distinction in charges (a ten basis-point unfold on this instance) for intermediating between the last word borrower and lender.
Sellers Play a Essential Position in Intermediating Money and Securities
Sellers additionally make markets for collateral by supplying securities counterparties are in search of and by accepting securities counterparties wish to borrow money in opposition to. Their significance can’t be understated: current estimates calculate that in late 2024 sellers borrowed and lent $3.7 trillion and $3.4 trillion per day (Hempel, Kahn, and Shephard 2025).
To handle short-term liquidity, redistribute and supply collateral, and finance safety inventories, sellers additionally actively transact amongst themselves in an interdealer market. Most interdealer trades clear by means of a central counterparty which turns into the counterparty to each commerce. Within the U.S., the Fastened Revenue Clearing Company (FICC) at the moment ensures most Treasury repo trades within the interdealer market. A key advantage of central clearing is the larger alternative for netting of positions, which reduces stability sheet prices and expands vendor intermediation capability. As well as, central clearing offers sellers with anonymity on their trades and reduces counterparty danger. These advantages, nevertheless, don’t come free of charge, as they require contributing to a default fund and better margining (see Neal 2024 and Copeland and Kahn 2024). By June 2027, the Securities and Change Fee (SEC) would require central clearing of U.S. Treasury-collateralized repos the place not less than one counterparty is a direct member of a registered clearing company (2023 SEC rule).
Observe the Money
Money usually enters repo markets by means of cash-rich buyers similar to MMFs searching for a short-term secured funding. Sellers intermediate the funds, immediately or by means of the interdealer market, and lend to money debtors, usually hedge funds in search of to lever their funding methods. Having mentioned the interdealer section, we subsequent focus available on the market constructions of the segments the place the funds originate and finish of their journey from money lenders to final debtors.
From Lenders to Sellers
The primary money lenders in repo are MMFs. Repos supply MMFs a versatile funding to handle consumer redemptions that additionally meets regulatory necessities on asset composition: SEC Rule 2a-7 restricts MMF investments to holdings of high-quality, short-term debt securities. Authorities MMFs, which account for over 80 p.c of whole U.S. MMF property as of March 2026, are additional restricted to investing in money, U.S. authorities securities, and repos backed by U.S. authorities securities. Presently, most transactions between MMFs and sellers are usually not centrally cleared. Sellers are extra prepared to forgo the advantages of central clearing for these transactions as a result of MMFs supply a aggressive, deep, dependable supply of funding.
The settlement of repo transactions entails a number of duties together with collateral valuation, margining, collateral administration, and custodial providers. As MMFs are usually not considering taking possession of particular collateral, they usually make investments on the whole collateral repos and depend on a clearing financial institution (at the moment, Financial institution of New York Mellon) to settle transactions on its books as a substitute of bearing the prices of organising again places of work for collateral administration. This section of the market, the place the events outsource to an agent the collateral administration to settle repo, is named the tri-party repo market. In distinction to the centrally cleared interdealer market, tri-party repo doesn’t rework the counterparty danger between the client and vendor, as a result of Financial institution of New York Mellon acts solely as an agent and never as a counterparty (see TMPG 2022).
Whereas this lender-to-dealer section traditionally has not been centrally cleared, MMF lending within the centrally cleared section has elevated sharply over the previous three years, reaching nearly 40 p.c of MMF repo exercise in 2026:Q1 (see chart under). This migration is in keeping with the advantages of central clearing outweighing the extra prices for sellers.
Fast Progress of Centrally Cleared Lender-to-Supplier Repo
Be aware: The chart exhibits MMFs’ non-public repo quantity by kind of clearing.
From Sellers to Debtors
As mentioned in yesterday’s publish, repo is a necessary device for hedge funds to spice up their returns. Sellers are the primary money lenders to hedge funds within the repo market, with hedge funds’ excellent repo quantity reaching $3 trillion in 2025:This fall. On this section, particular securities play a vital position and repos settle bilaterally, in distinction to the lender-to-dealer section that largely settles by means of a 3rd occasion.
A key consideration behind the bilateral selection is that hedge funds make use of extremely levered fixed-income methods (such because the cash-futures foundation commerce). As such, these methods require each versatile entry to collateral and price effectivity to profitably exploit small worth differentials. The bilateral section offers hedge funds extra flexibility alongside the primary dimension relative to the tri-party section, the place the collateral stays with the clearing financial institution. Relating to the second, haircuts are usually decrease on this section: 75 p.c of all Treasury repo trades within the bilateral section which are non-centrally cleared have a zero haircut (OFR 2023). Sellers can nonetheless discover engaging the non-centrally cleared market as a result of there could possibly be alternatives for releasing stability sheet area by means of so-called “netted packages.” For instance, one other kind of hedge fund technique entails using a reverse repo to buy an inexpensive “off-the-run” safety and a repo to supply an “on-the-run” safety for a brief place. This mixture of a repo and a reverse repo with the identical counterparty and tenor and comparable collateral could possibly be eligible for stability sheet netting with out the involvement of a central counterparty and due to this fact is well-suited to be executed through a netted bundle.
In keeping with the pattern in the direction of central clearing, the subsequent chart illustrates that an growing quantity of repo between hedge funds and sellers has centrally cleared over the previous three years, from 8 p.c in early 2021 to 30 p.c in late 2025. Current evaluation exhibits that this exercise tends to extend on quarter-ends when sellers’ stability sheets are extra constrained (OFR 2026).
Substantial Improve in Centrally Cleared Supplier-to-Borrower Repo
Be aware: The chart exhibits the overall non-public repo quantity and the centrally cleared quantity within the dealer-to-borrower section.
To Sum Up
The assorted microstructures of repo segments noticed within the U.S. mirror how a heterogeneous set of members consider the trade-offs concerned in repo transactions in another way. Prices associated to the settlement of securities led to the emergence of tri-party repo; stability sheet prices favor central clearing; in the meantime, inventive contracting—similar to netted packages—mitigates prices in bilateral, non-centrally cleared repos.
Gara Afonso is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Jun-Davinci Choi is a analysis analyst within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Gonzalo Cisternas is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Will Riordan is a capital markets buying and selling advisor within the Federal Reserve Financial institution of New York’s Markets Group.
The right way to cite this publish:
Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan, “Observe the Money! Microstructure of Repo Markets,” Federal Reserve Financial institution of New York Liberty Avenue Economics, September 29, 2026, https://doi.org/10.59576/lse.20260929
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the creator(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the creator(s).
