

It’s well-known that financial coverage impacts corporations’ funding selections. However which corporations are essentially the most aware of adjustments in rates of interest? And does this responsiveness range over time? The literature has given various solutions to this query, specializing in traits resembling agency measurement, age, and monetary place, and largely finding out these traits in isolation. On this publish primarily based on a latest Workers Report, we discover how funding responsiveness to financial coverage adjustments throughout corporations and over time. We discover that funding by most corporations in most time durations responds little to financial coverage. For some corporations in some durations, nevertheless, funding may be very aware of adjustments in rates of interest. Whereas these cases of sturdy sensitivity correlate with a number of agency traits, there’s substantial variation that can’t simply be linked to particular traits of corporations. Our findings subsequently underscore the significance of contemplating all the distribution of funding responses fairly than specializing in the common impact.
How Companies’ Funding Responds to Modifications in Financial Coverage
Our evaluation revisits a burgeoning literature that estimates how firm-level funding responds to financial coverage surprises. Specifically, we construct on influential work by Ottonello and Winberry (2020). Financial coverage surprises are measured as adjustments within the federal funds price implied by federal funds futures in a slim window round financial coverage bulletins. Funding is the expansion price within the capital inventory measured at a quarterly frequency for every publicly listed agency in Compustat. The literature has sometimes studied heterogeneity in funding responses by interacting financial surprises in a regression framework with a selected agency attribute, resembling measurement, age, or a specific monetary variable.
We observe a unique method. As a substitute of choosing a given doable driver of heterogeneity ex ante, we search to characterize all the unconditional distribution of responses of funding to financial coverage (which we abbreviate as RIMP). Importantly, this method is agnostic to what drives the RIMP, though we go on to discover the relative significance of a number of drivers after estimating the RIMP. In apply, we estimate a clustering regression framework that optimally teams every agency in every time interval as a excessive or low responder primarily based on how its funding responds to financial coverage. Particulars of the process may be present in our Workers Report.
Our estimates ship a RIMP distribution, which we plot within the chart beneath. Within the overwhelming majority of quarters and for many corporations, funding responds little to adjustments in financial coverage. This sensitivity, nevertheless, shouldn’t be zero. Certainly, all corporations nonetheless reduce funding when rates of interest improve, as witnessed by the detrimental values within the horizontal axis of the chart. In just a few cases, funding drops considerably within the face of an rate of interest hike. For about 5 % of all corporations and quarters, a financial shock that raises the federal funds price by 1 proportion level induces a 4 proportion level drop within the development price of capital.
Most Companies in Most Time Durations Reply Little to Financial Coverage Modifications; Some Reply Strongly
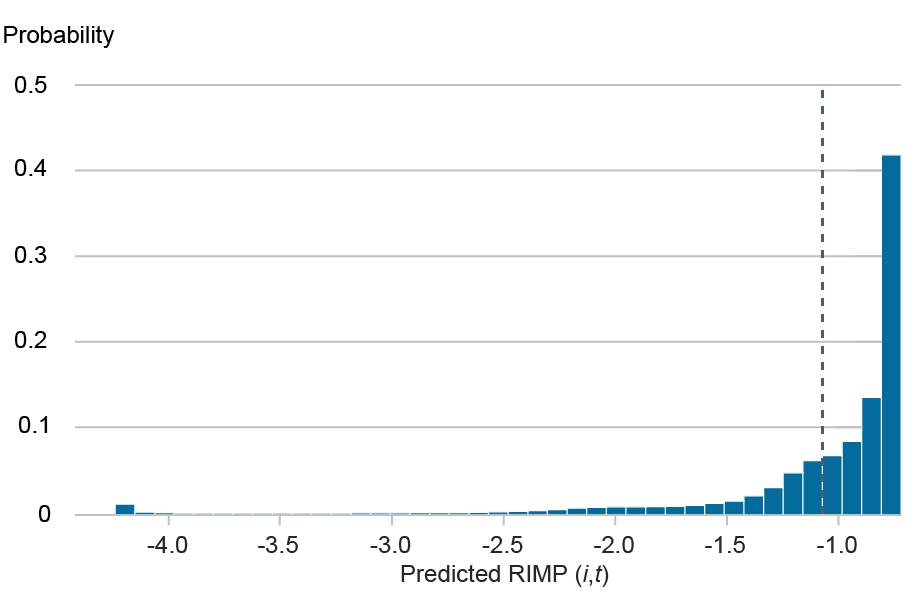
Notes: The chart plots the anticipated response of funding to financial coverage (RIMP) on the firm-quarter degree. The vertical dashed line marks the homogeneous RIMP.
Which Companies Reply the Most?
Having estimated the RIMP distribution, we are able to dig deeper into what makes a agency’s, or a given quarter’s, funding very aware of financial shocks. We decompose the variance of responses into three elements: (everlasting) agency variation, mixture time variation, and firm-specific time variation. As we present within the chart beneath, little or no of the general variation within the RIMP is frequent to all corporations. A bigger, however nonetheless restricted, share is defined by everlasting variations throughout corporations. It follows that many of the variation within the RIMP is inside corporations over time. Which means that a particular agency’s funding can reply considerably to a financial shock in a given quarter, however that very same agency may be comparatively unresponsive for a number of quarters thereafter.
A lot of the Variation in Companies’ Sensitivity to Curiosity-Price Surprises Is Inside Companies over Time
Share of RIMP variation (%)
Word: The chart decomposes the response of funding to financial coverage (RIMP) into everlasting variations throughout corporations, mixture variation over time, and within-firm variation over time.
Our method additionally permits us to research which agency traits are a very powerful determinants of the funding responsiveness to financial shocks. For example, Gertler and Gilchrist (1994) discover that small corporations are extra responsive, whereas Cloyne et al. (2024) level at younger corporations. Within the chart beneath, we mission our estimated RIMP on every of those two traits and ensure each findings. Actually, we additionally discover that the traits work together, as we present within the paper: small and younger corporations have essentially the most detrimental RIMP (in different phrases, they reduce funding essentially the most when confronted with a financial tightening).
Small Companies and Younger Companies Reduce Funding the Most When Confronted with an Curiosity Price Hike
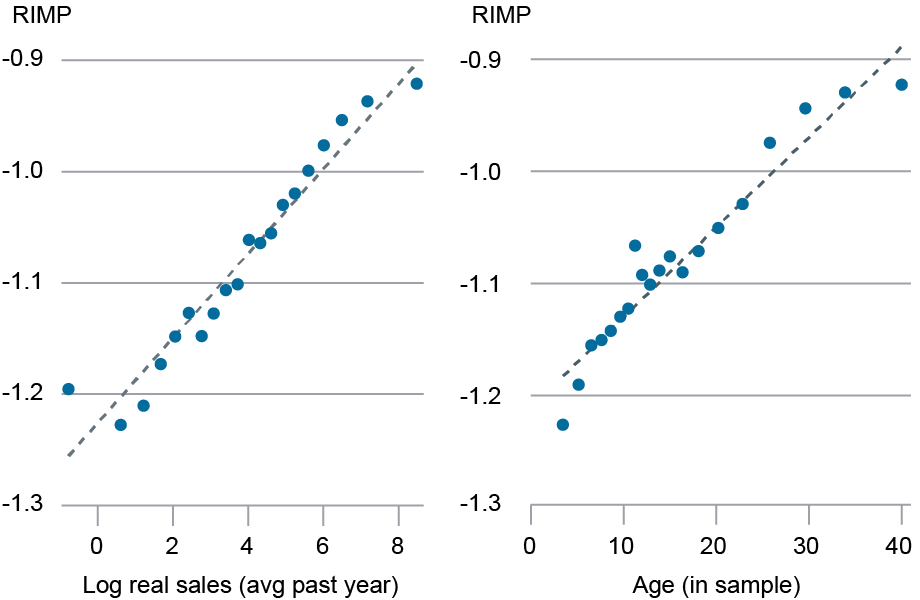
Notes: The chart presents binscatter plots through which the anticipated response of funding to financial coverage (RIMP) is plotted towards measurement (left panel, the log of common actual gross sales over the previous 4 quarters) and age (proper panel, outlined as years within the pattern). Dashed traces point out fitted linear regressions.
Within the Workers Report, we discover a number of different drivers studied within the literature. For example, we discover that corporations with shorter debt maturity are extra delicate to financial coverage. We additionally spotlight different drivers that may point out the significance of behavioral mechanisms. For instance, perceptions of low cost charges and the price of capital are correlated with the RIMP. Furthermore, corporations that report being extra optimistic reduce funding much less in response to an rate of interest hike.
Importantly, all of those traits could have an effect on funding responsiveness collectively and can seemingly work together. Our method permits us to review this multidimensionality instantly. Whereas we discover that a number of traits predict funding responses, a lot of the general variation within the RIMP stays unexplained.
Conclusion
We’ve offered new empirical proof on how funding responds to adjustments in financial coverage. Whereas all corporations reduce funding when confronted with an rate of interest hike, most regulate little whereas just a few corporations reply so much. This excessive sensitivity seems to be transient: a given agency is aware of a financial shock in a given quarter, however then responds little thereafter. A number of agency traits predict funding responses. For example, small and younger corporations look like essentially the most delicate to financial coverage adjustments. Our method permits us to review this heterogeneity in a complete method: we discover that a number of agency drivers matter concurrently and that a lot of the funding responsiveness is pushed by unobservable components.
Thomas Drechsel is an affiliate analysis professor within the Economics Division at Johns Hopkins College.
Daniel Lewis is an affiliate professor within the Division of Economics at College School London.1

Davide Melcangi is an financial analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Laura Pilossoph is an affiliate professor of economics at Duke College.
1 Disclosure assertion for Daniel Lewis: In the course of the previous three years, I acquired consultancy charges exceeding the disclosure threshold below the AEA Disclosure Coverage from Banque de France, a probably celebration with respect to the subject material of this text. The consultancy relationship didn’t have an effect on the design, evaluation, interpretation, or reporting of the analysis. The celebration had no proper to overview this analysis.
The way to cite this publish:
Thomas Drechsel, Daniel Lewis, Davide Melcangi, and Laura Pilossoph, “Agency Heterogeneity and the Response of Funding to Financial Coverage,” Federal Reserve Financial institution of New York Liberty Road Economics, October 7, 2026, https://doi.org/10.59576/lse.20261007
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the writer(s) and don’t essentially replicate the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the writer(s).
