

From the Nice Recession till 2019, U.S. labor productiveness progress disenchanted. Nonfarm-business output per hour grew about 1 p.c a yr from 2010 to 2019, down from 3 p.c within the late Nineteen Nineties. This slowdown was particularly pronounced in manufacturing, and it coincided with a slowdown within the progress of income per employee amongst public corporations. Nonetheless, since 2019, progress has picked as much as twice the 2010s price, round 2 p.c. On this submit, I take advantage of information from corporations’ 10-Okay filings to unpack this current acceleration. I first present that the acceleration seems in public corporations’ income per employee, then doc how the positive aspects went into revenue margins, and at last, what agency traits predicted vital revenue margin will increase. The rise in revenue margins is according to ongoing declines within the labor share of output.
Agency Productiveness, 2019–2025
This piece research U.S. Compustat corporations throughout each manufacturing and providers over 2010–2025, damaged into two durations: 2010–2019 and 2019–2025. I drop agriculture, utilities, finance, actual property, and public administration, because of the recognized challenges of productiveness measurement in these industries.
Nonfarm-business output per hour grew 1.0 p.c a yr from 2010 to 2019 and a couple of.2 p.c a yr from 2019 to 2025. In Compustat, I discover a related qualitative progress acceleration. Actual income per employee—gross sales deflated by business output costs, divided by employment—traces the identical flip, from 0.7 p.c to 2.2 p.c a yr over the identical time durations.
The chart beneath illustrates this pattern, displaying that each income per employee amongst public corporations and output per hour are accelerating within the current interval. Throughout all datasets, the labor productiveness uptick is actual.
Labor Productiveness and Agency Income Per Employee Accelerated Collectively in 2019-2025
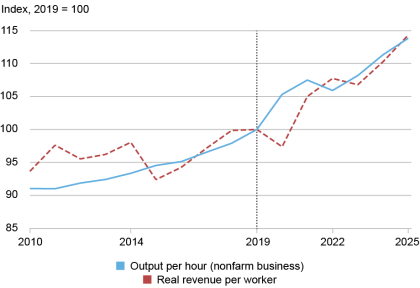
Notes: Labor productiveness, listed to 2019 = 100: Chart exhibits BLS nonfarm-business output per hour and Compustat actual income per employee.
Greater income per employee on the agency stage doesn’t point out who positive aspects from this elevated income. The extra income might go to employees, as corporations compete for labor by larger wages, or accrue to corporations in revenue margins. Agency-level information let me measure how corporations’ revenue margins modified over time. I discover how revenue margins modified between 2019 and 2025 and what agency traits predicted markup positive aspects.
Agency Revenue Margins
A revenue margin is revenue divided by gross sales: the share of every gross sales greenback the agency retains after paying its prices. The gross margin subtracts the direct price of manufacturing (price of products offered), whereas the working margin additionally subtracts overhead (promoting, common, and administrative expense, which in Compustat usually consists of R&D). If productiveness positive aspects have been flowing to corporations’ earnings, margins ought to present it. Via the 2010s margins have been flat: gross margins grew about 0.4 p.c a yr from 2010 to 2019, and working margins have been roughly flat. Each then turned up: on common, gross margins went from about 34 p.c of gross sales in 2019 to 37 p.c in 2025 (1.3 p.c progress per yr), and working margins from 16 p.c to 18 p.c (2.4 p.c progress per yr).
Gross and Working Revenue Margins Elevated in
2019-2025
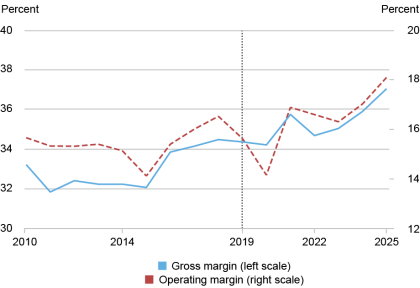
Notes: Compustat gross margin (COGS) and working margin (OPEX), 2010–2025, sales-weighted; gross on the left scale, working on the precise scale.
Which Corporations Noticed the Largest Positive factors?
Lastly, I ask whether or not corporations that spend money on intangibles (e.g., analysis and growth, or R&D) skilled the most important positive aspects. In earlier work, we confirmed that whereas productiveness progress in manufacturing slowed within the 2010s, R&D depth in manufacturing continued to rise. Does R&D depth predict larger revenue margins within the current period?
Corporations that entered the interval with larger R&D expenditure relative to gross sales noticed bigger subsequent positive aspects: corporations with 10 p.c extra R&D expenditure relative to gross sales in 2019 noticed about 0.7 p.c larger operating-markup progress over 2019–2025, and 0.5 p.c over 2022–2025. Corporations with larger capital depth didn’t see such a big sample. This sample is according to returns to intangible depth quite than capital depth. This means a probably vital function for investments in know-how and intangibles in driving markups.
Measured productiveness has risen since 2019 in each mixture and agency information, ending greater than a decade of sluggish progress. A part of the positive aspects surfaced with wider revenue margins: on an affordable baseline, the working margin rose over 2 p.c a yr from 2019 to 2025. R&D depth seems to be an vital predictor of margin progress for corporations, according to the rising returns to high-tech corporations and corporations which have invested in intangibles since COVID. Whether or not these rising margins are returns to vital funding in intangibles or purely a windfall for corporations is a subject to discover in future work.
Jeremy Pearce is a analysis economist within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
How one can cite this submit:
Jeremy Pearce, “Income per Employee Is Up. Are Corporations Getting a Bigger Share?,” Federal Reserve Financial institution of New York Liberty Road Economics, October 15, 2026, https://doi.org/10.59576/lse.20261015
BibTeX: View |
Disclaimer
The views expressed on this submit are these of the creator(s) and don’t essentially replicate the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the creator(s).

