

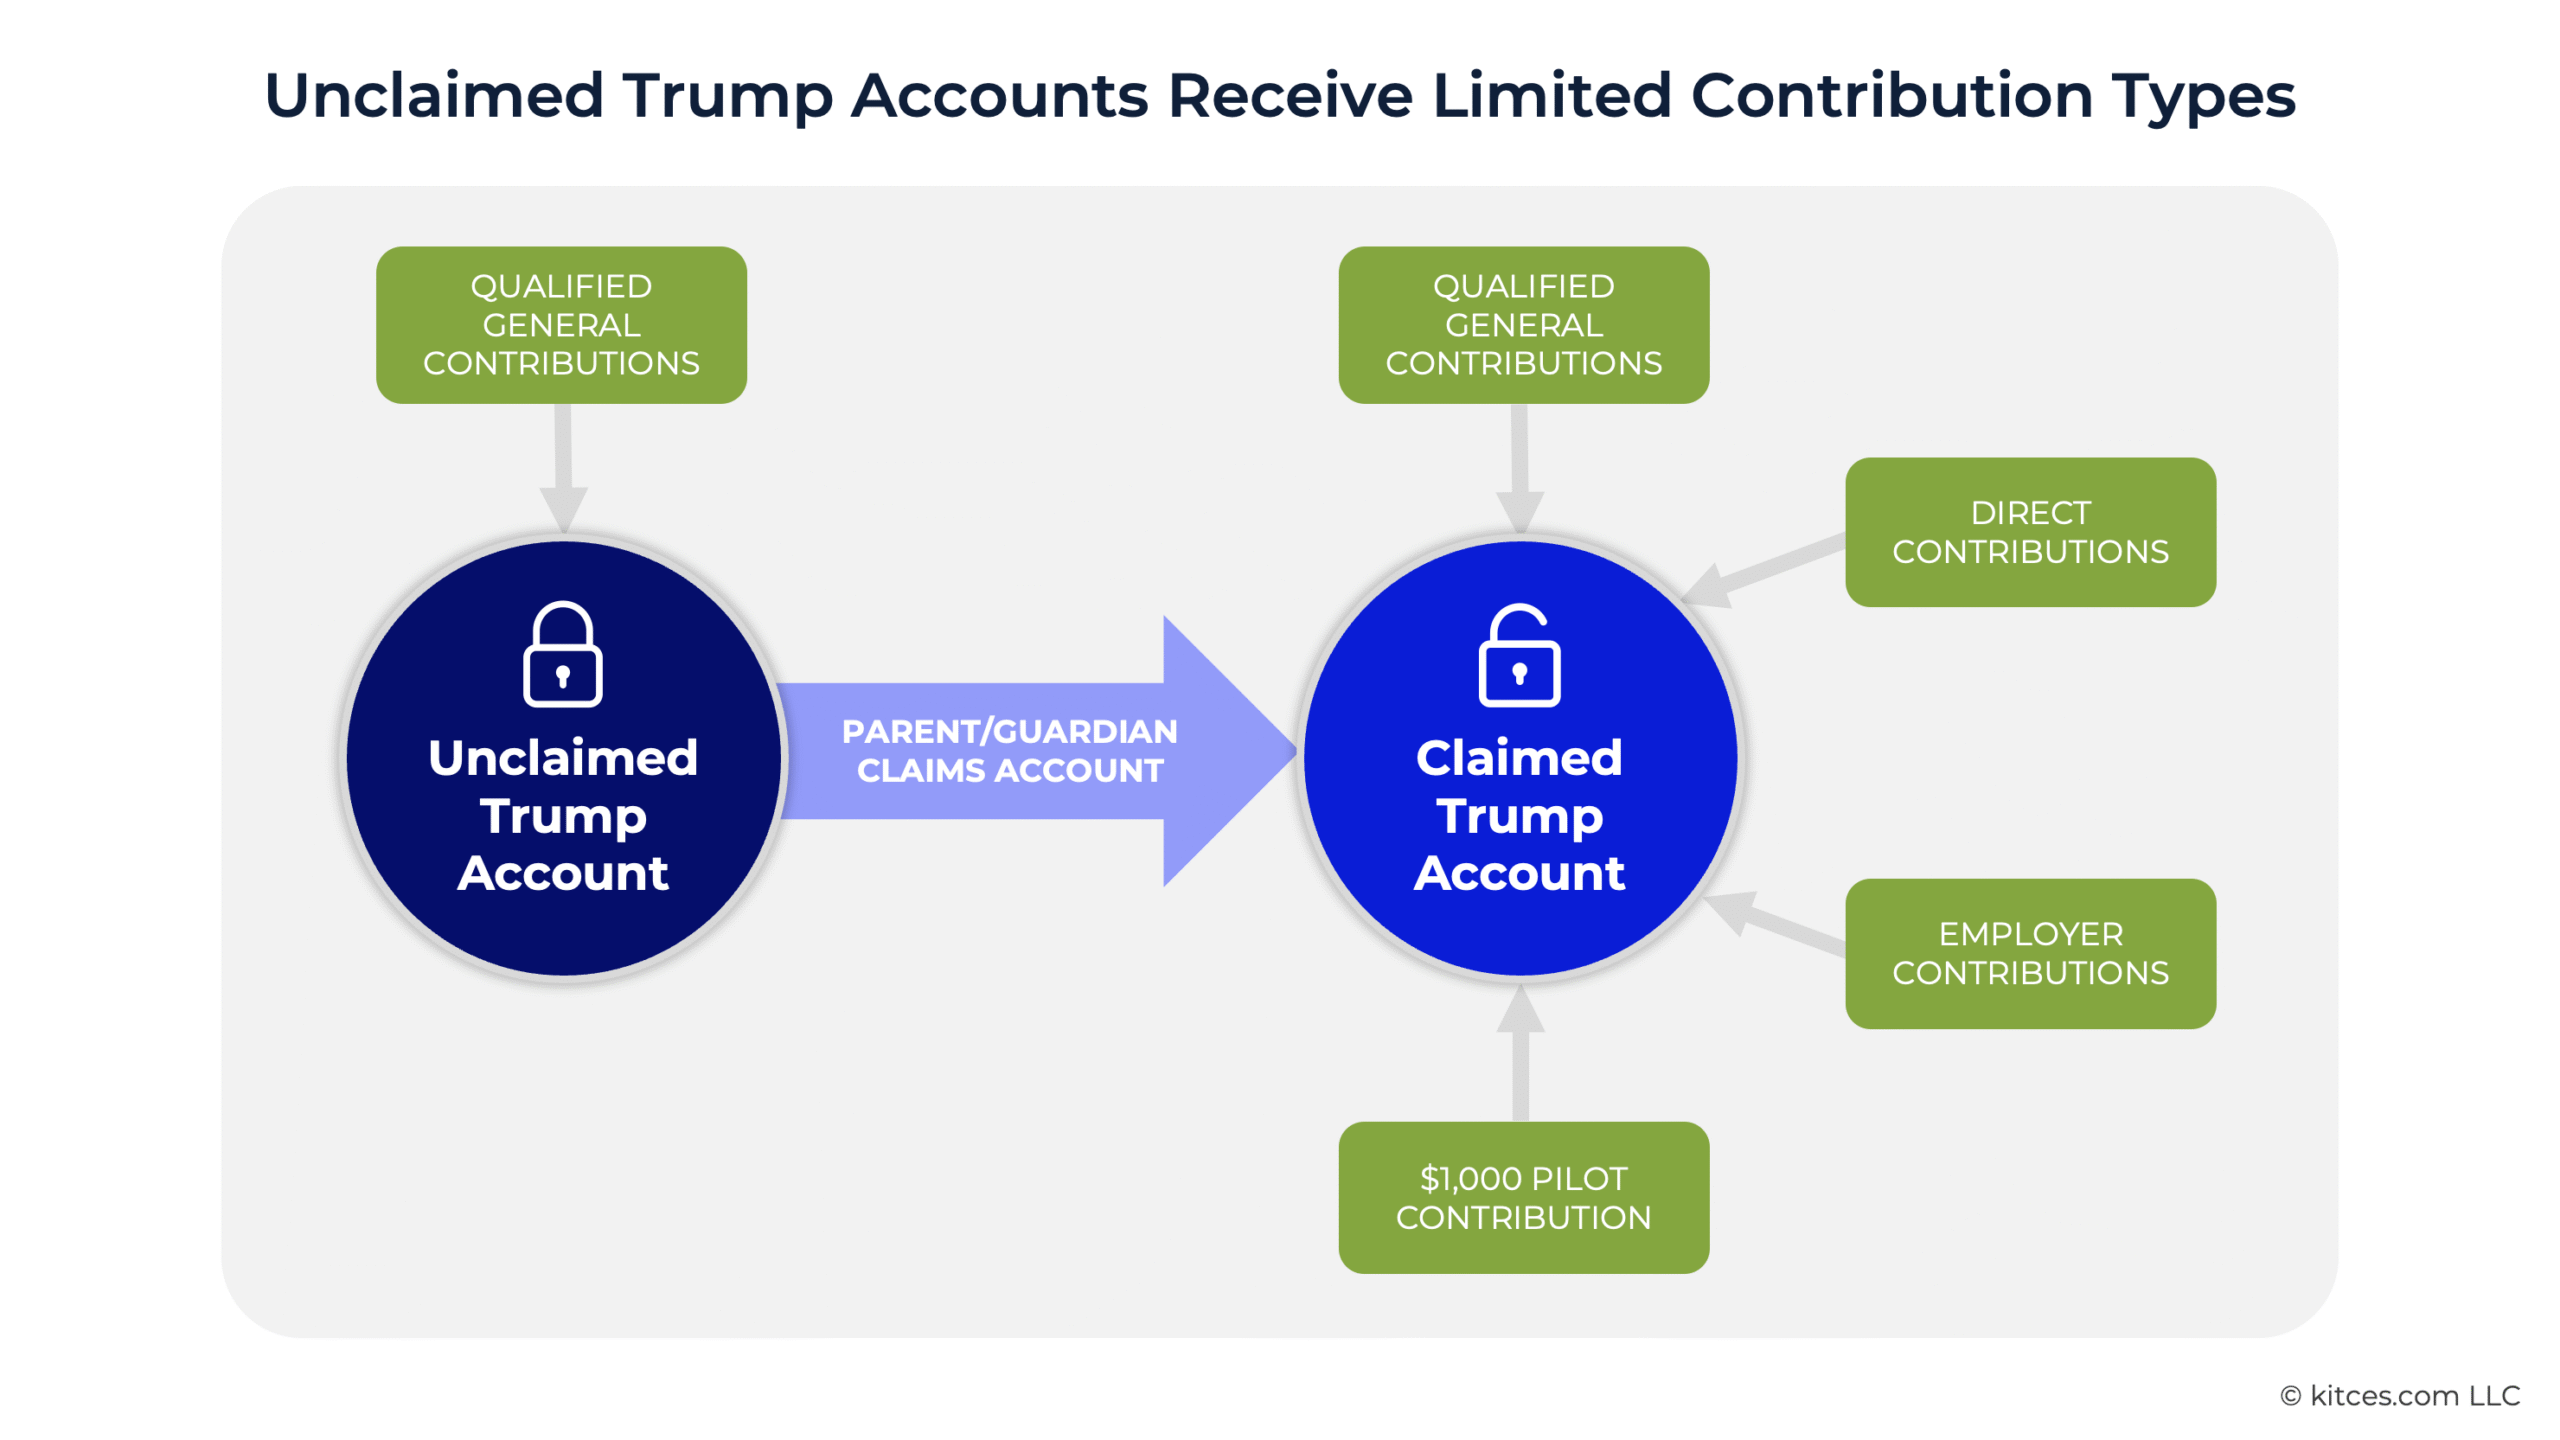
Sec. 530A accounts a.okay.a. Trump Accounts (TAs), the ‘starter’ retirement accounts for youngsters underneath 18 that had been created underneath the One Large Lovely Invoice Act (OBBBA), have been accessible to open and fund since July 4, 2026. And through that point, they’ve gained modest traction: in line with Treasury Division estimates, round 7–8 million kids have had accounts opened on their behalf. This early ‘success’ is due largely to the Federal authorities’s $1,000 ‘pilot’ contribution made to kids born from 2025–2028, in addition to to ‘certified common contributions’ from charitable organizations such because the Dell Basis’s contribution of $250 for youngsters underneath 10 years outdated in ZIP codes with median family incomes underneath $150,000. Nonetheless, there are roughly 70 million U.S. kids underneath 18, that means that till lately even with these incentives solely round 10% of the kids eligible to have had a Trump Account opened on their behalf truly had one.
Underneath new rules issued by the Treasury Division in late September, nonetheless, each U.S. little one who’s eligible for a TA (i.e., who has a Social Safety Quantity and has not but reached the yr that they flip 18) has now had one mechanically opened on their behalf. Because of this all eligible kids will now be capable of obtain common contributions from charitable organizations for which they’re certified, which they would not have gotten in the event that they did not have a TA open of their identify (though these contributions usually have age and geographical restrictions, so not everybody with a TA will truly obtain them).
Apparently, although, even kids who have not obtained any sort of contribution may also have accounts opened on their behalf – even when their mother and father or guardians had already determined to not open one – and there is not any capability to choose out or shut the account if it is not wanted or needed! Nonetheless, mother and father and guardians might want to undergo a technique of ‘claiming’ their kids’s auto-enrolled account and verifying their identification as a way to assume management over it and make extra contributions. Accounts that go unclaimed will both be closed within the yr their beneficiary turns 18 (if there are not any funds in it) or will keep open and be rolled into an IRA when claimed (if it does have funds). Which implies that it is a good suggestion for folks or guardians of youngsters with auto-enrolled accounts to assert the account on their kids’s behalf – even when they do not plan on ever funding it – to keep away from it being improperly claimed by another person in circumstances of identification theft (or just misplaced with potential funds inside that the beneficiary may finally use).
Along with the auto-enrollment guidelines, the brand new Treasury rules additionally create the power for donors of certified common contributions to take action within the type of particular person shares, which might then be held in recipients’ TAs for at least 5 years – regardless of the textual content of the legislation that restricts TAs to holding solely ‘eligible investments’ of low-fee U.S. fairness index mutual funds or ETFs. In different phrases, TAs will not be solely now allowed to personal particular person shares, they’re required to carry them (with no capability to say no the contribution or promote the inventory for 5 years) in the event that they occur to be included in a gaggle of accounts {that a} donor decides to make a certified common contribution to.
Though this new rule would possibly incentivize extra donors to make large-scale in-kind contributions to TAs (because the web price of many rich founders and shareholders consists primarily of firm inventory, which they might be restricted from promoting in massive blocks), it additionally introduces new dangers for TA house owners who will likely be topic to the better volatility of single shares (and who could have no capability to decide on the shares they spend money on, or to promote these they do not need!). Notably, nonetheless, accounts that obtain particular person or employer contributions, in addition to the $1,000 Federal pilot contribution, will nonetheless be required to take a position these contributions into eligible investments, so the results of single-stock certified common contributions will likely be smaller for many who obtain different kinds of contributions to TAs.
The important thing level is that, with the principles and processes round Trump Accounts persevering with to evolve, monetary advisors can present worth by speaking the impression of the brand new guidelines to purchasers with minor kids – notably about the necessity to declare their kid’s auto-enrolled TA. Mother and father could not have a lot alternative now about whether or not to open an account or settle for a single-stock certified common contribution, however advisors can present invaluable steering on learn how to shield and handle the account going ahead!
 |
And if you wish to go deeper on this subject, hear immediately from the writer on the Monetary Advisor Technician podcast. |


