

Geoeconomic danger—the danger that corporations incur valuation losses when international locations deploy financial, commerce, or monetary leverage for geopolitical goals—has turn out to be a first-order concern for traders. On this put up, based mostly on our latest Workers Report, we doc that home U.S. shares expose traders to substantial geoeconomic danger by means of corporations’ world supply-chain relationships, affecting traders’ returns and portfolio allocation. We additionally discover that traders are compensated for bearing geoeconomic danger by means of larger danger premia.
Export Controls as Geoeconomic Shocks
Traders don’t must personal international shares to be uncovered to geoeconomic danger. Home shares can embed international exposures when U.S. corporations promote to abroad clients or depend on world provide chains. These hyperlinks imply {that a} international coverage shock can scale back the worth of U.S.-listed corporations and transmit geoeconomic danger to home portfolios. These world hyperlinks can assist traders diversify their portfolios when shocks are country- or –market-specific, however they provide much less safety when coverage shocks have an effect on the identical worldwide relationships throughout many U.S. corporations. Geoeconomic shocks are due to this fact tough to diversify away as a result of they will have an effect on a number of home shares by means of a typical international publicity.
We research this danger by means of the imposition of U.S. export controls by the Bureau of Business and Safety. This company of the Division of Commerce can limit U.S. corporations from promoting sure applied sciences to particular international entities deemed to be a danger to U.S. nationwide safety. Since 2014, these restrictions have been leveraged incessantly within the U.S.-China technological rivalry, particularly in industries akin to semiconductors, telecommunications, synthetic intelligence, and superior computing. We interpret the addition of a international agency to the export management record as a manifestation of geoeconomic danger for its U.S. suppliers.
This setting lets us hint geoeconomic danger from focused Chinese language corporations to U.S. traders. We hand-collect Chinese language entities added to U.S. export-control lists and use FactSet Revere supply-chain knowledge to determine the U.S. suppliers related to those straight focused Chinese language clients. We then match these affected U.S. suppliers to the holdings of U.S. home fairness mutual funds from the CRSP Mutual Fund Database, overlaying greater than 5,000 funds from 2010 to 2023. We give attention to mutual funds as a result of they’re main traders in U.S. fairness markets: long-term mutual funds held round a fifth of U.S. company fairness in 2025. As well as, because of their month-to-month portfolio holdings, we observe which funds owned U.S. suppliers to newly focused Chinese language corporations when export controls are introduced, and to trace how managers rebalance their portfolios afterward.
Geoeconomic Threat in Home Portfolios
Regardless of their ostensible focus, home fairness funds have vital publicity to the U.S.-China geoeconomic competitors. On common, 20.3 % of fund belongings are invested in U.S. corporations with not less than one Chinese language buyer. The chart beneath reveals that this publicity is very excessive for funding kinds tied to development and know-how. For instance, science and know-how funds make investments 43.3 % of their portfolios in home corporations which can be related to Chinese language clients. Inside these China-connected portfolios, U.S. suppliers to Chinese language clients newly focused by export controls account for 8.4 % of belongings.
Home Funds Differ Broadly in Their Publicity to the U.S.-China Competitors
Development Funds
China publicity (proportion of fund belongings)
Science & Know-how Funds
China publicity (proportion of fund belongings)
Industrial Funds
China publicity (proportion of fund belongings)
Mid/Small – Cap Funds
China publicity (proportion of fund belongings)
Sources: CRSP Mutual Fund Database; FactSet Revere.
Word: This chart reveals the share of U.S. home fairness mutual fund portfolios which can be invested in U.S. corporations with Chinese language clients, by funding type.
Though export controls straight goal Chinese language corporations, in addition they scale back the worth of these corporations’ U.S. suppliers. The chart beneath reveals that, in our knowledge, U.S. suppliers expertise a cumulative irregular inventory return of −3.6 % proper after the announcement that export controls goal a number of of their Chinese language clients, with a lot of the decline occurring throughout the first 5 buying and selling days.
Shares of U.S. Suppliers Fall when Their Chinese language Prospects Are Added to the Export Management Record
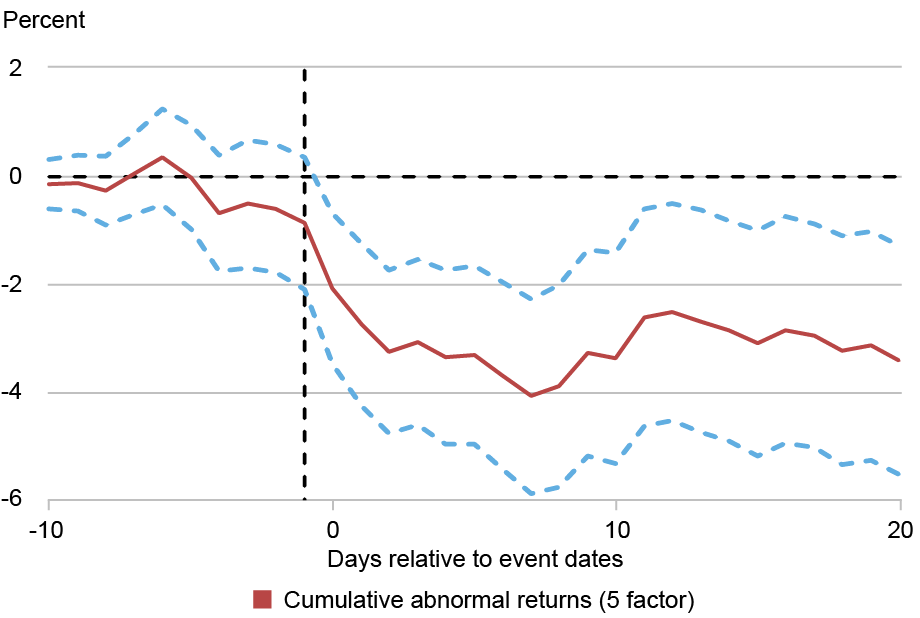
Notes: The chart reveals cumulative irregular returns for shares issued by U.S. corporations that provide straight focused Chinese language clients across the announcement that these clients are added to a U.S. export-control record. The chart relies on the Fama-French five-factor mannequin.
These value actions lengthen to the mutual funds holding these shares. We measure a fund’s publicity to new export controls because the share of its portfolio invested in affected U.S. suppliers in that month. We then evaluate funds with larger and decrease publicity to export controls throughout the identical funding type and month, whereas controlling for fund traits. Funds holding shares of affected U.S. suppliers expertise larger volatility and decrease (uncooked and factor-adjusted) returns following the imposition of export controls. Conditional on an export management occasion, a one commonplace deviation improve in publicity (2.5 %) is related to a 22-basis-point decline in month-to-month returns.
Mutual Funds Reply by Rebalancing Away from Geoeconomic Threat
Energetic managers scale back holdings of affected U.S. suppliers and likewise promote different China-linked U.S. corporations not affected by the present announcement. The promoting of affected U.S. suppliers, nonetheless seen three months after the export controls, means that managers don’t usually deal with the worth decline as a purely non permanent idiosyncratic shock. This broader promoting means that traders be taught that geoeconomic danger could also be embedded in complicated supply-chain hyperlinks that weren’t absolutely priced or understood earlier than the shock. In sum, export controls may function a wake-up name, prompting traders to be taught extra a couple of portfolio’s oblique publicity to China and to the potential for future restrictions.
This portfolio rebalancing is pushed completely by energetic funds, in keeping with passive funds merely monitoring benchmark indices. For a one commonplace deviation improve in publicity, passive funds expertise a 31-basis-point decline in month-to-month returns, in contrast with 22 foundation factors for energetic funds. Within the following month, passive funds additionally expertise outflows equal to about 0.35 % of belongings, whereas the outflows from energetic funds are statistically insignificant.
Energetic managers due to this fact seem to partially insulate fund efficiency from geoeconomic shocks, however this insulation comes with larger risk-taking. Particularly, uncovered energetic funds subsequently maintain extra concentrated portfolios and tilt towards “lottery-like” shares, suggesting that some managers reply to efficiency shortfalls by taking up further danger to restrict future outflows.
Specialist managers and higher-fee funds expertise smaller efficiency declines after export management shocks, whereas conventional market-timing and stock-picking abilities don’t predict higher outcomes. In sum, the administration of geoeconomic danger may require the power to map potential coverage shocks onto corporations’ positions in world worth chains.
Is Geoeconomic Threat Priced In?
Per the portfolio proof, traders appear to require compensation for bearing geoeconomic danger. We kind shares based mostly on prior publicity to export controls and evaluate future returns of high-exposure and low-exposure corporations. A protracted-short portfolio that buys corporations beforehand uncovered to export controls and shorts unexposed corporations earns about 1 % monthly in irregular returns after adjusting for normal danger elements. In different phrases, the market seems to deal with geoeconomic publicity not as a one-time information occasion, however as a priced danger for which traders demand compensation.
Summing Up
As financial coverage turns into extra intently tied to nationwide safety, corporations’ supply-chain hyperlinks can turn out to be a channel by means of which geoeconomic shocks have an effect on traders’ portfolios. For traders, the related query is due to this fact not solely the place a inventory is listed, however the place the agency earns revenues and the way uncovered these relationships are to geopolitical coverage shocks. Diversification throughout home shares might not absolutely mitigate this danger when many corporations share related world exposures. On this surroundings, understanding the worldwide linkages of portfolio corporations turns into more and more vital for understanding portfolio danger.

Matteo Crosignani is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Lina Han is an assistant professor of finance on the College of Massachusetts Amherst.
Marco Macchiavelli is an assistant professor of finance on the College of Massachusetts Amherst.
This put up has been revealed concurrently, with minor adjustments, on VoxEU.org.
The right way to cite this put up:
Matteo Crosignani, Lina Han, and Marco Macchiavelli, “Navigating Geoeconomic Threat within the U.S. Inventory Market,” Federal Reserve Financial institution of New York Liberty Road Economics, October 1, 2026, https://doi.org/10.59576/lse.20261001
BibTeX: View |
Disclaimer
The views expressed on this put up are these of the writer(s) and don’t essentially replicate the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the writer(s).
