

On September 22, 2026, a member of the Financial Coverage Board of the Reserve Financial institution of Australia (RBA) gave a speech – A Wage-price Spiral: What are the Possibilities? – at Melbourne College. The tenor of his presentation was that regardless of the fixed current claims about wages pressures emanating from a labour market that’s too tight and driving the present inflationary episode, there was no proof to assist the claims. That could be a place that I’ve been arguing for during the last a number of years in countering the mainstream narratives. However, curiously, and shockingly, on the identical day, the RBA governor gave a speech to the right-leaning Committee for Financial Growth of Australia (CEDA) – Fireplace Chat on the Committee for Financial Growth of Australia (CEDA) – the place she claimed that unemployment needed to rise in the direction of 5 per cent (from its present degree of 4.5 per cent) as a result of the labour market was too tight and driving enterprise prices and inflation. The extraordinary juxtaposition of those views is one factor. However the governor’s continuous claims that the present inflationary pressures are sourced from the labour market defies the proof and clearly is meant to provide her cowl for additional rate of interest rises.
Background studying
I’ve traced the shifting RBA positions on the underlying causes of the inflationary pressures for a few years now and these weblog posts present a short historical past of my issues overlaying the pressures through the pandemic after which following the Center East fiasco:
1. RBA governor makes one other self-serving public presentation ignoring the dismal actuality she helps to create (July 30, 2026).
2. Apparently the RBA has the pursuits of the unemployed it’s placing out of labor at coronary heart. Not! (June 29, 2026).
3. RBA price hikes – ideology triumphing over proof and motive (Might 7, 2026).
4. Rate of interest hikes won’t get ships shifting by means of the Strait of Hormuz extra rapidly (March 12, 2026).
5. RBA bows to monetary market strain and increase financial institution earnings on the expense of low-income mortgage holders (February 5, 2026).
6. Australia’s unemployment price is nicely above any affordable full employment degree (August 28, 2025).
7. Inflation persevering with to fall in Australia additional exposing the incompetence of our central financial institution (July 30, 2025).
8. Treasurer, please sack the RBA governor and the Financial Coverage Board members – they’ve gone rogue (July 10, 2025).
9. Australia – the inflation spike was transitory however central bankers hiked charges with solely partial data (June 26, 2025).
10. Australian inflation episode nicely and really over – please inform the RBA to cease making an attempt to push unemployment up additional (November 27, 2024).
11. Australian Treasurer refuses to make use of his legislative energy to rein within the rogue RBA (September 25, 2024).
12. The delusional RBA has everybody satisfied that they’re the explanation inflation is falling (June 19. 2024).
13. RBA is now a rogue organisation and the Authorities ought to act to carry it again into test (February 7, 2024).
14. So-called ‘Crew Transitory’ declared victors (January 8, 2024).
15. RBA financial coverage choice represents a terminally damaged coverage mannequin in Australia (November 8, 2023).
16. Mainstream logic ought to conclude the Australian unemployment price is above the NAIRU not under it because the RBA claims (July 24, 2023).
17. RBA needs to destroy the livelihoods of 140,000 Australian staff – a surprising indictment of a failed state (June 22, 2023).
18. RBA governor’s ‘Qu’ils mangent de la brioche’ moments of disdain (June 8, 2023).
19. Australia – inflation nonetheless falling whereas the RBA governor retains inventing ruses to maintain mountain climbing charges (Might 31, 2023).
20. No proof of an imminent wages breakout in Australia regardless of the claims by the RBA to justify their hikes (Might 17, 2023).
21. The present inflationary interval is just not remotely just like the Seventies (March 9, 2023).
22. Inflation has most likely peaked in Australia – sure, it was a transient episode (March 2, 2023).
That choice is adequate (there have been a number of different weblog posts overlaying the subject) to reveal a constant theme.
Not one of the occasions which have occurred inside the interval lined has proven the reasoning in these posts to be invalid.
In actual fact, all of the proof helps the place enunciated.
RBA Governor persists along with her claims that unemployment is simply too low
The Governor has continually claimed that the 2 inflationary episodes since 2020 – the primary arising because of the COVID provide constraints and the second that adopted Trump/Bibi Center East invasion – had been as a result of the unemployment price was too low and wage pressures had been driving up enterprise prices and being handed on to customers.
When it was apparent that the availability constraints arising from the COVID pandemic was driving value pressures, the governor claimed the inflation was as a result of the labour market was too tight and that unemployment was nicely under the so-called Non-Accelerating-Inflation-Charge-of-Unemployment (NAIRU).
The unobserved NAIRU is conceptually the speed of unemployment at which the inflation price stabilises.
It’s unattainable to estimate precisely and during the last a number of years, the RBA has wavered in its claims of what the extent is.
Initially, they claimed it was 4.5 per cent, then they dropped that to a decrease determine and now the Governor is hinting at a price of 5 per cent.
Pure sophistry.
However regardless of the price could be, the info does present us with some clues as to the place the official unemployment price is relative to this ‘conceptual’ degree.
On this weblog submit – Mainstream logic ought to conclude the Australian unemployment price is above the NAIRU not under it because the RBA claims (July 24, 2023) – I demonstrated clearly how, even when we settle for the NAIRU logic, the RBA was operating an incoherent and arbitrary line.
Again through the pandemic, the present RBA governor claimed that:
… the unemployment price should rise … the NAIRU … 4½ most likely seems, we expect, possibly within the ballpark.
The mainstream idea in relation to the NAIRU summarises as:
1. When the unemployment price is above the NAIRU, inflation will decline.
2. When the unemployment price is under the NAIRU, inflation will speed up.
Whereas the NAIRU is unobservable and the estimates are at all times topic to very large customary errors (which make the purpose estimate ineffective for coverage anyway), we are able to observe the official unemployment price and the inflation price.
What did we observe?
1. From Might 2022, the Australia official unemployment price turned very secure round 3.5 per cent.
2. The inflation price rose through the worst of the pandemic because of the large provide impediments that COVID created exacerbated by the Ukraine state of affairs and OPEC+.
3. The inflation price peaked in September 2022, after which it declined steadily despite the fact that the unemployment price has remained very secure all through the rise and fall interval.
Making use of that mainstream logic would counsel the NAIRU, if it existed, have to be under an unemployment price of three.5 per cent on condition that secure degree of unemployment had been related to a declining inflation price since round September 2022.
The RBA by no means addressed that flaw of their logic and even right this moment maintain batting on in regards to the NAIRU and the necessity for price hikes.
Her most up-to-date entreaty got here at a presentation to CEDA in Sydney on September 22, 2026 – hyperlink is within the introduction.
She was requested “What’s the tolerable degree of unemployment to get to the place we must be on inflation?” to which she replied (partially):
What can we tolerate? The best way it form of works technically is that, and I don’t like to speak about this NAIRU, however there may be sure ranges of unemployment that should you go under that degree of unemployment, it introduces quite a lot of strain within the labor market, and that may put upward strain on wages and costs as a result of it places strain on prices for companies, that finds its method into costs.
So it’s not that I can say I’ll solely tolerate an unemployment price of, say, 4.5 per cent in the intervening time. For the time being, we expect that’s a bit tight. So the query actually is just not what can I tolerate or what can the Board tolerate, however what degree of unemployment eases the strain on the availability aspect of the financial system? So that basically is the essence of the reply. There’s no explicit degree at which I feel we are able to get to. I feel between 4.5 and 5 will most likely take sufficient warmth out of the labor market that it’ll ease strain on inflation. However the entire level about inflation being too excessive in the intervening time is it’s reflecting the truth that the demand aspect of the financial system is outstripping the power of the financial system to produce the products and companies, and one proof of that’s that the labor market seems tight.
Unemployment began rising in July 2022 – after reaching a low of three.5 per cent or 487.5 thousand (seasonally adjusted).
The official price is now (August 2026) 4.6 per cent or 722.9 thousand individuals.
That’s 235.5 thousand individuals have misplaced their jobs or have been unable to get work if they’re new entrants to the labour power.
A 5 per cent unemployment price scaled towards the present labour power dimension would require unemployment rise to 778 thousand, an additional 55 thousand staff with out jobs.
At present the proportion of accessible staff not working in a method or one other (unemployed or underemployed) is 10.8 per cent.
That’s some 722,900 individuals who’re formally unemployed and 962,900 individuals who’re underemployed.
In what parallel universe does that signify a ‘tight’ labour market?
Additional, the newest wages knowledge launched on August 19, 2026, reveals that wages development is in decline and under the inflation price by 0.5 factors.
The information confirms that total actual wages development total has been unfavourable for the final three quarters and unfavourable following the ten quarters of cuts within the Covid inflation interval.
There isn’t any wages drawback in Australia that’s driving the present inflationary pressures.
The RBA is simply making this up.
I’ll return to that time later.
As an apart, when adjusted for inflation and in contrast towards the Wage Value Index (WPI), which is the overall measure of wages in Australia, it turns into clear that the RBA Governor’s wage has grown a lot sooner than common Australian wages.
Whereas advocating actual wage cuts for the remainder of the workforce, the present RBA governor’s personal wage has been insulated from the cost-of-living pressures.
In 2024-25, her wage rose by 5.78 per cent whereas the inflation price was round 2.1 per cent.
In 2025-26, her wage was reported to be listed to develop by 3.49 per cent, which is about equal to the inflation price over that interval.
Inflationary expectations
It was attention-grabbing that she did handle the problem that central banks face when the inflationary pressures are predominantly pushed by supply-shocks.
She claimed that:
… shocks to the availability aspect of the financial system are very tough for financial coverage to cope with. Financial coverage can cope with demand shocks, as a result of it may be utilized in a cyclical sense to lift or decrease demand by elevating and reducing rates of interest …
However when you have got a sequence of provide shocks like we’ve had, and inflation simply will increase after which it drops again and will increase once more, the priority that we now have is that it would get embedded in inflation expectations of households and companies, and due to this fact it would turn into self-fulfilling.
So the RBA is now claiming it’s mountain climbing charges to stifle inflationary expectations.
The next graph reveals three measures of anticipated inflation expectations produced by the RBA – Inflation Expectations – G3 – from the June-quarter 2005 to the June-quarter 2021.
The three measures are:
1. Market economists’ inflation expectations – 1-year forward.
2. Market economists’ inflation expectations – 2-year forward – so what they suppose inflation shall be in 2 years time.
3. Break-even 10-year inflation price – The common annual inflation price implied by the distinction between 10-year nominal bond yield and 10-year inflation listed bond yield. It is a measure of the market sentiment to inflation danger.
However the systematic errors within the forecasts, the value expectations (as measured by these sequence) have been flat if not falling during the last 2 years.
Probably the most dependable measure – the Break-even 10-year inflation price – is now in decline, falling 0.2 factors to 2.3 per cent and inside the RBA targetting vary.
This measure is an effective indicator of long-term inflation expectations.
There was some short-term rise in near-term expectations through the restriction interval of COVID however the longer expectations had been secure as a result of most individuals understood the transitory nature of that episode.
And even after the Center East provide shock and the accompanying RBA concern mongering about uncontrolled inflation, there has barely been a shift in these sequence.
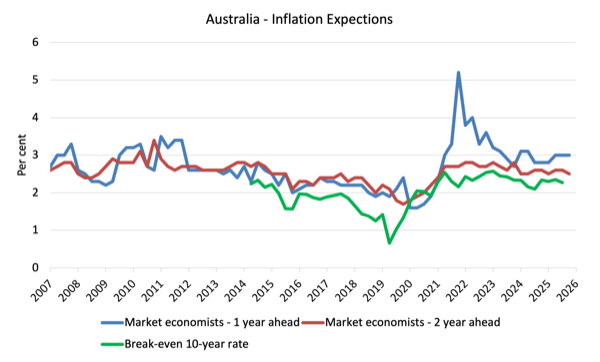
On this foundation, there isn’t any factual foundation for mountain climbing charges to quell ‘self-fulfilling’ inflation.
The inflation is provide pushed and rate of interest hikes can do nothing to arrest that.
All of the hikes will obtain is to kill demand in different areas of the financial system, drive up unemployment and transfer the financial system in the direction of and into recession.
After which when the availability pressures abate, we’re left with an pointless financial disaster to cope with.
An alternate view from the RBA Financial Coverage Board
On the identical day, in Melbourne, a Financial Coverage Board member Iain Ross gave a presentation on the College of Melbourne entitled – A Wage-price Spiral: What are the Possibilities?
He explicitly advised the viewers that he was speaking as a member of that Board however not representing the views of the Board.
His stated:
I need to speak about wage-price spirals. The ‘risk’ of rising wages has been a persistent theme within the monetary press since inflation started rising sharply from mid-2021. A lot of media commentators have raised the danger of a wage-price spiral – pointing to the Seventies when the oil value shock collided with massive pay rises flowing by means of the financial system.
I take a special view.
As background, Iain Ross was a a previous president of the Truthful Work Fee, the wage setting authority in Australia and a former choose within the Federal and State programs.
He was additionally a former senior official on the Australian Council of Commerce Unions (ACTU).
He mentioned previous historical past – particularly the Seventies when commerce unions represented over 50 per cent of the workforce – now right down to round 13 per cent.
He stated:
My central level is that the labour market framework of right this moment could be very totally different to that of the Seventies and Nineteen Eighties.
The general thesis is that there isn’t any proof of the emergence of a wage-price spiral within the current circumstances and up to date knowledge counsel such an final result is unlikely.
Which is a direct contradiction of the road that the RBA governor was operating in Sydney on the identical day at her presentation.
He in contrast the wage local weather within the Seventies – robust unions, much less legislative impediments to industrial motion, comparative wage justice (the place one group’s wage rises are unfold to all by means of wage setting establishments), a deal with indexation preparations, and many others – to now the place all these parts are lacking.
He identified that the present enterprise bargaining practices imply that wages are fastened for prolonged durations with rare changes, which makes it unattainable for them to regulate to transitory inflationary pressures.
In that context he argued that:
One other key distinction from the Seventies is that inflation expectations are higher anchored, and fewer prone to change in response to a short lived inflationary shock … This issues as a result of it reduces the chance {that a} non permanent rise in inflation will turn into embedded in wage and price-setting choices and develop right into a self-sustaining course of. Along with adjustments within the institutional and bargaining setting, these variations have considerably decreased the chance of a wage-price spiral in Australia.
It could be attention-grabbing to be a ‘fly on the wall’ on the subsequent MP Board assembly given this divergence in views.
Apart – poorly chosen language
The Governor additionally used some very poorly chosen language when discussing the alleged productiveness increase which may come from AI:
So I feel, sure, it’s the nice white hope. AI is the nice white hope to enhance productiveness.
The time period – nice white hope – has its basis in racial battle and white supremacy.
Its origin seems to emerge from the domination of boxing by the black American – Jack Johnson – who received the world championship in 1908.
Historical past information that there was a large racist response to his victory and white promoters on the time sought excessive and low for a white boxer to revive what had been the standard racial hierarchy in world boxing.
In 1910, they pulled a white boxer – James J. Jeffries – out of retirement and the journalist Jack London “coined the phrase ‘Nice White Hope’ to explain Jeffries in his try to win the heavyweight crown from African-American world champion Jack Johnson”.
He misplaced.
Over time, the time period has generalised to seek advice from conditions the place white persons are anticipated to imagine dominance over individuals of color.
A central financial institution governor ought to by no means use such lax and biased language.
Conclusion
There are predictions that the RBA will hike rates of interest twice extra, beginning subsequent week.
It could be a significant demonstration of how ideology has triumphed over motive and the 35 or so per cent of Australians who maintain mortgages will carry the direct burden, whereas many others should endure the oblique impacts (lack of jobs by means of demand suppression).
That’s sufficient for right this moment!
(c) Copyright 2026 William Mitchell. All Rights Reserved.
