

Repo markets play a significant function within the U.S. monetary system. On this three-part sequence, we look at who participates in these markets, what trade-offs affect how completely different repo segments are structured, and why repos matter for financial coverage. Immediately’s submit introduces repo transactions, specializing in the most important private-sector contributors and why they have interaction in these markets.
What’s a Repo?
A repurchase settlement or repo is a monetary transaction through which one social gathering sells a safety in change for money, with the dedication to repurchase the identical (or a intently associated) safety for a prespecified value on a future date. (From the attitude of the social gathering shopping for the safety and later reselling it, this transaction is named a reverse repo.) Repos are a vital part of the U.S. monetary system, performing each as a supply of funding and short-term funding for a lot of monetary establishments, in addition to a market for acquiring particular securities. Latest estimates assess the each day quantity of excellent agreements within the U.S. at round $13.5 trillion or 40 % of U.S. GDP (see OFR 2026).
The time between the preliminary sale and the repurchase, together with the worth distinction, determines the rate of interest, referred to as the repo charge. Repo charges differ relying on a wide range of components, most notably the kind of collateral accepted (the securities bought), maturity (the size of time between the preliminary sale and repurchase), counterparty, the dimensions of the haircut (the distinction between the worth of the securities bought and money delivered), and clearing (the method between the execution and last settlement of a transaction). Round 70 % of repos are collateralized by U.S. Treasury securities and most have an in a single day maturity. By way of clearing, round 60 % of repos are cleared by means of a central counterparty (35 %) or by means of a 3rd social gathering (25 %), whereas 40 % are immediately cleared between the client and vendor (OFR 2025).
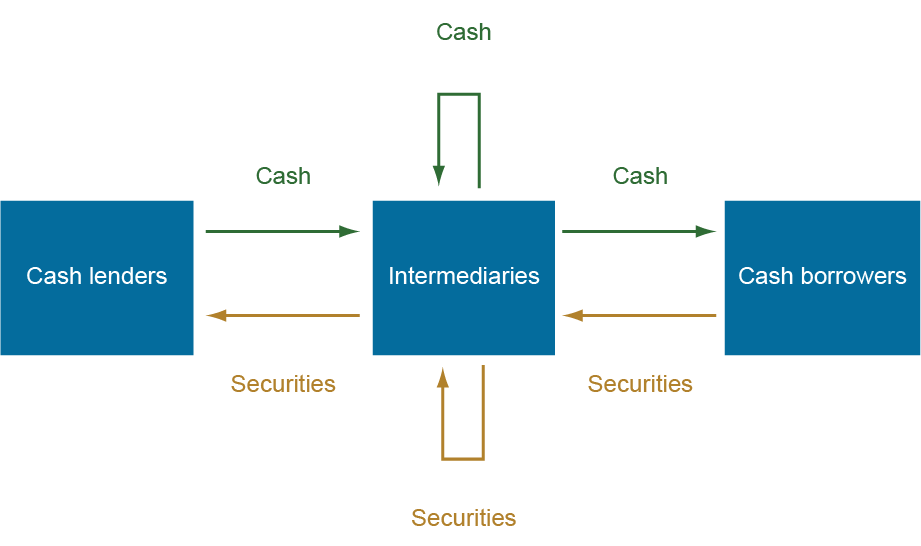
As an illustration, the diagram under reveals a stylized illustration of a repo market. Many several types of transactions happen in repo markets. For instance, a seller—performing as an middleman—can buy securities from levered traders like hedge funds (a reverse repo from the seller’s perspective), and in addition enter right into a repo with different sellers or with money lenders comparable to cash market funds (MMFs) to promote the securities, thus finally channeling funds from money lenders to money debtors. In tomorrow’s submit, we delve deeper into the microstructure of varied segments of repo markets.
A Stylized Illustration of a Repo Market
Repos could be traced again to the early twentieth century. Repo market measurement and contracting conventions modified markedly within the Eighties following the failure of a number of sellers, amid a rising degree and volatility of rates of interest and rising provide of Treasury debt (see Garbade 2006). An necessary conference that has contributed to the liquidity and development of repo markets is that repos involving Treasury and federal company securities are exempt from the computerized keep below the U.S. Chapter Code that, because the title suggests, comes into impact when an organization recordsdata for chapter and stays collectors from taking sure actions on account of their claims towards the corporate. Which means that if the money borrower defaults through the lifetime of the repo, the money lender can usually terminate its repo contracts with the defaulting counterparty, promote the securities promptly, and keep away from the delay and uncertainty of the chapter course of.
What Are Repos Used for?
In a repo, the social gathering promoting the safety is interested by borrowing money. The counterparty, nevertheless, might enter the repo transaction for certainly one of two causes: to take a position money and earn a return, or to acquire a particular safety. The primary motive makes a repo economically just like different short-term cash market devices comparable to federal funds, Eurodollars, or industrial paper. In contrast to in these markets, the transaction is collateralized: from the attitude of the money lender, the securities scale back the chance of the commerce.
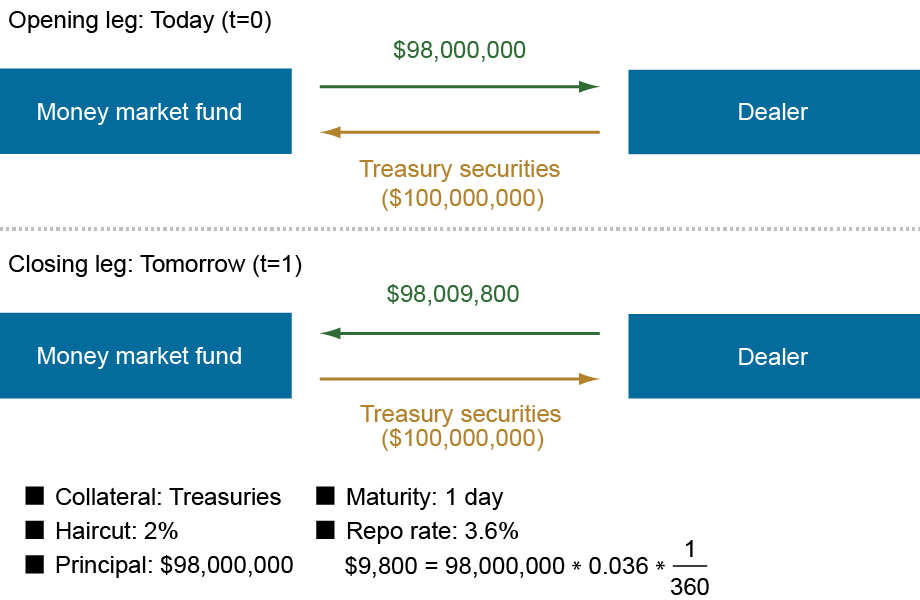
A “normal collateral repo” (or GC repo) is an efficient instance of a repo transaction through which the money lender will not be within the particular securities it receives. In GC repo, the money lender agrees to obtain any safety that meets a specified standards (for instance, Treasury securities with lower than ten years to maturity) relatively than a particular safety. This makes GC repo a funding market each for money debtors searching for to finance a basket of securities and for money lenders trying to make investments money at a aggressive charge. The diagram under reveals an illustration of a repo used as a funding instrument. On this instance, a MMF is trying to make investments $98 million in money in a single day and lends to a repo seller towards a basket of Treasury securities together with a haircut of two %. The next day, the MMF receives $98,009,800 (at a return of three.6 % in annual phrases) and returns the securities.
An Instance of a Repo Transaction
Contributors might also have interaction in repo to accumulate a particular safety. Within the particular situation market, the securities used to settle the transaction are recognized on the outset of the commerce. When a specific safety is in excessive demand relative to obtainable provide, it has shortage worth and is named a “particular,” and sometimes trades at a decrease charge relative to the prevailing GC charge: the money lender, searching for to acquire a particular, scarce asset is keen to forgo some return (Duffie 1996). From this angle, repos are like a safety lending transaction towards money collateral relatively than a collateralized mortgage. There are two necessary variations: first, repo primarily makes use of fixed-income devices as collateral and, second, repo sometimes doesn’t grant the lender the precise of early recall of the securities.
Repos additionally play a key function in financial coverage implementation. In at this time’s submit we give attention to personal repos, returning to their use in central banks’ toolkits within the third submit of this sequence.
Who Participates in Repo Markets?
Relative to the federal funds and Eurodollar and chosen deposits markets, the panorama of personal repo contributors is extra advanced for 2 most important causes. First, there’s a broader and extra numerous set of final debtors and lenders. Second, sellers are instrumental intermediaries in repo markets. Within the the rest of this submit, we make clear the primary class, describing the important thing function of sellers in tomorrow’s submit.
The Debtors
The highest money debtors in personal repo markets are hedge funds. Hedge funds depend on repo markets for leverage to spice up their returns. An instance of a hedge fund technique that makes use of repo is the so-called “Treasury cash-futures foundation commerce.” On this technique, a hedge fund purchases a Treasury safety and sells a Treasury futures contract, which permits it to revenue from the worth differential. To amplify the return on the premise commerce, hedge funds finance the acquisition of the Treasury securities with money borrowed in a repo that makes use of these securities as collateral. Because the chart under reveals, hedge fund borrowing in repo markets tripled over 2013-23, from $400 billion to $1.5 trillion; after which it doubled once more within the following two years, reaching $3 trillion in late 2025.
Hedge Funds Are the Essential Money Debtors in Non-public Repo Markets
Notes: The chart reveals personal repo money borrowing quantity by numerous participant sorts. FBOs are U.S. branches and companies of international banks, HFs are hedge funds, USDIs are U.S. depository establishments, and REITs are actual property funding trusts.
The subsequent three largest debtors in repo markets at this time are U.S. branches and companies of international banks (FBOs), U.S. depository establishments (USDIs), and actual property funding trusts (REITs). Collectively, their excellent borrowing in repo has ranged between $800 billion and $1.3 trillion since 2013.
The Lenders
The primary money lenders in repo are MMFs. As the subsequent chart reveals, between January 2013 and January 2021, MMF lending elevated by 90 %, from below $600 billion to $1 trillion. Within the following 5 years, MMF lending virtually tripled, reaching $3 trillion in January 2026. Repo markets supply MMFs a short-term funding that meets their regulatory necessities on maturity and asset composition whereas offering flexibility to assist handle investor redemptions.
The second largest lenders in repo are hedge funds. Though hedge funds are internet money debtors in repo, in addition they lend to handle money and liquidity and for collateral transformation. In late 2025, hedge funds lent round $1.3 trillion, a gentle improve from $350 billion in early 2013. The subsequent three largest lenders—government-sponsored enterprises (GSEs), U.S. branches and companies of international banks, and U.S. depository establishments—are key gamers within the federal funds, Eurodollar, and chosen deposits markets, and collectively lent $0.6-$1.5 trillion in repo over the 2013-25 interval.
MMFs Are the Essential Money Lenders in Repo Markets
Notes: The chart reveals personal repo money lending quantity by numerous participant sorts. FBOs are U.S. branches and companies of international banks, HFs are hedge funds, USDIs are U.S. depository establishments, GSEs are government-sponsored enterprises, and MMFs are cash market funds.
In Sum
Repo markets are the venue the place monetary establishments lend and borrow cash in a collateralized method, normally quick time period. Whereas debtors on this market get hold of money, lenders might search short-term investments or a particular safety of curiosity. As a market within the trillions of {dollars}, repo markets host all kinds of contributors. Within the subsequent posts on this sequence, we are going to look at the microstructure of varied segments of this market, and the market’s significance for financial coverage implementation.
Gara Afonso is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Jun-Davinci Choi is a analysis analyst within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Gonzalo Cisternas is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Will Riordan is a capital markets buying and selling advisor within the Federal Reserve Financial institution of New York’s Markets Group.
How you can cite this submit:
Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan, “Who’s Borrowing and Lending in Repo Markets?,” Federal Reserve Financial institution of New York Liberty Road Economics, September 28, 2026, https://doi.org/10.59576/lse.20260928
BibTeX: View |
Disclaimer
The views expressed on this submit are these of the creator(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the creator(s).
