

In previous work, we confirmed that buying and selling in U.S. Treasury securities is changing into more and more targeting the final buying and selling day of every month. On this put up, we present that buying and selling can also be changing into extra concentrated across the designated pricing, or “strike,” occasions for fixed-income indexes. The focus is particularly pronounced on month-end buying and selling days. We additionally doc a marked shift in buying and selling exercise from round 3 p.m. (ET) to round 4 p.m. after a significant fixed-income index supplier moved its strike time from 3 p.m. to 4 p.m. in January 2021.
Finish-of-Month Buying and selling, Index Rebalancing, and Index Strike Instances
In an earlier LSE put up, we discovered that general Treasury safety buying and selling quantity is about 58 % increased on the final buying and selling day of the month than on different days. We confirmed in a associated put up that this focus of exercise has elevated sharply over the previous decade or so and is related to improved market liquidity. We conjecture that the elevated focus of exercise might mirror the expansion of property managed relative to fixed-income indexes, a lot of that are rebalanced at month-end.
Not like the fairness market, the Treasury market is over-the-counter and has no exchange-mandated closing time. As a substitute, index suppliers have discretion as to what time of day to set their closing costs. Traditionally, 3 p.m. was the business customary (amongst different causes, open-outcry buying and selling for Treasury futures ended at 3 p.m. and the three p.m. strike time allowed for a lead time earlier than mutual funds’ internet asset worth manufacturing time of 4 p.m.). On January 14, 2021, Bloomberg Barclays—one of many largest suppliers of fixed-income indexes (and now known as Bloomberg Fastened Earnings Indices)—modified the strike time for its U.S. dollar-denominated indexes from 3 p.m. to 4 p.m. Some stories counsel that one purpose for the change was to scale back monitoring error for funds which are required to cost portfolios utilizing 4 p.m. costs.
Empirical Strategy
We measure the share of every day’s buying and selling quantity executed within the ten-minute home windows across the 3 p.m. and 4 p.m. index strikes and monitor these shares over time. We do that for all days as a gaggle and for end-of-month days when fixed-income indexes are rebalanced. We additionally evaluate intraday buying and selling patterns earlier than and after Bloomberg modified its strike time. Our evaluation covers buying and selling exercise in probably the most lately auctioned (that’s, on-the-run) notes and bonds within the interdealer market.
Buying and selling More and more Concentrates on the Shut
The chart beneath exhibits that the share of each day buying and selling quantity within the ten minutes round 3 p.m. elevated from a median of two.3 % in 2016 to three.4 % in 2020. When Bloomberg’s strike time modified from 3 p.m. to 4 p.m. in January 2021, the share of exercise round 3 p.m. plunged, and the share of exercise round 4 p.m. (which had additionally been growing from 2016 to 2020) surged. The share of exercise round 4 p.m. has since elevated from a median of two.5 % in 2021 to three.5 % in 2025.
Buying and selling Now Concentrates Across the 4 P.M. Closing Strike
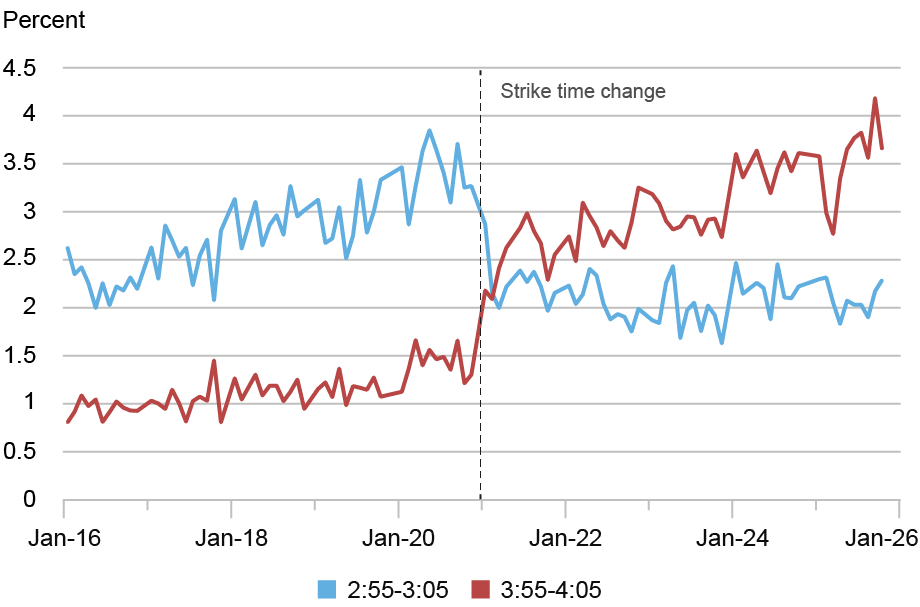
Observe: The chart plots the common share of each day buying and selling quantity in probably the most lately auctioned Treasury notes and bonds from 2:55-3:05 p.m. and from 3:55-4:05 p.m. for every month from January 2016 to December 2025 (excluding days with an early market shut and months during which the final buying and selling day has an early shut).
Results Extra Pronounced on the Final Day of the Month
As proven within the subsequent chart, buying and selling quantity is much more concentrated across the day-end strike occasions on the final buying and selling day of every month, when indexes are rebalanced. The share of exercise round 3 p.m. on such days elevated from a median of 8.1 % in 2016 to 12.1 % in 2020. When Bloomberg’s strike time modified in January 2021, the share of exercise round 3 p.m. plunged, and the share of exercise round 4 p.m. (which had additionally been growing from 2016 to 2020) surged. The share of exercise round 4 p.m. has since elevated from a median of 11.6 % in 2021 to twenty.4 % in 2025.
Finish-of-Day Buying and selling Is Extra Pronounced on the Final Day of the Month
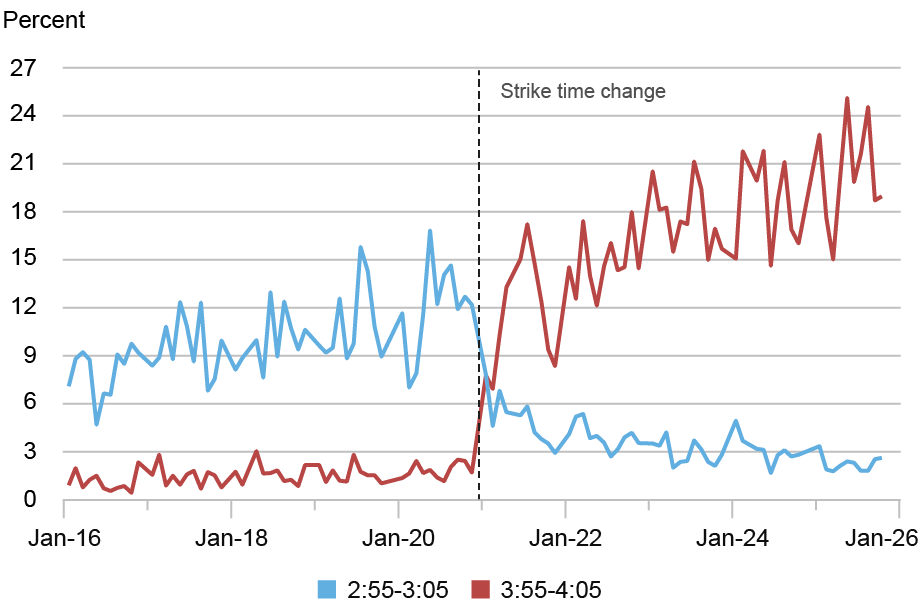
Observe: The chart plots the share of each day buying and selling quantity in probably the most lately auctioned Treasury notes and bonds from 2:55-3:05 p.m. and from 3:55-4:05 p.m. on the final buying and selling day of every month from January 2016 to December 2025 (excluding days with an early market shut).
Results Are Altering the Intraday Sample of Exercise
The growing share of day-end buying and selling and the elevated significance of the 4 p.m. strike time are mirrored in adjustments within the intraday sample of buying and selling exercise. The subsequent chart plots the common share of each day buying and selling quantity in every five-minute interval from 7 a.m. to five:30 p.m. in 2016 and 2025. In 2016, buying and selling quantity spiked on the 8:30 and 10 a.m. launch occasions of macroeconomic bulletins, when public sale outcomes have been launched shortly after 1 p.m., and across the 3 p.m. strike time. There have been a lot smaller spikes round 4 p.m. and 5 p.m.
Buying and selling Exercise Spikes on the Day-Finish Strike Instances
Notes: The chart plots the common share of each day buying and selling quantity in probably the most lately auctioned Treasury notes and bonds for every five-minute interval from 7 a.m. to five:30 p.m. in 2016 and 2025 (excluding days with an early market shut). Grey bars denote overlap in shares between 2016 (blue) and 2025 (gold). Instances point out interval beginning occasions.
In 2025, the sample is usually comparable, however the 4 p.m. spike is rather more pronounced. Curiously, the three p.m. spike is of comparable magnitude throughout the 2 years, however quantity shares are then increased in 2025 for each interval from 3:10 p.m. to five:05 p.m., and particularly within the ten minutes round 4 p.m.
Our final chart compares the intraday patterns on month-end days in 2016 and 2025. We discover a lot bigger day-end spikes on nowadays, particularly in 2025, according to our earlier outcomes. The half-hour interval between 3:45 and 4:15 p.m. thus accounts for multiple quarter of whole each day exercise on month-end days in 2025, on common, with about half of that between 3:55 and 4:00 p.m. alone. These are unusually excessive buying and selling quantity days to start with, as defined earlier.
Finish-of-Day Buying and selling Exercise Spikes A lot Extra on the Final Day of the Month
Notes: The chart plots the common share of each day buying and selling quantity in probably the most lately auctioned Treasury notes and bonds for every five-minute interval from 7 a.m. to five:30 p.m. on the final buying and selling day of every month in 2016 and 2025 (excluding days with an early market shut). Grey bars denote overlap in shares between 2016 (blue) and 2025 (gold). Instances point out interval beginning occasions.
A basic notice about our intraday evaluation is that there’s round the clock buying and selling available in the market—as mentioned in this text. We select to plot the patterns for 7 a.m. – 5:30 p.m. solely as a result of such hours account for the overwhelming share of each day buying and selling quantity and since U.S. macroeconomic bulletins and different vital occasions (together with U.S. Treasury auctions and end-of-day strike occasions) happen throughout these hours.
Summing Up
We discover that buying and selling exercise within the U.S. Treasury market is more and more concentrated across the end-of-day index strike occasions. That is very true on the final buying and selling day of every month when indexes are rebalanced, complementing our earlier findings of sharply elevated buying and selling on these days extra usually. We additional discover a marked redistribution of buying and selling exercise from round 3 p.m. to round 4 p.m. when a significant fixed-income index supplier moved its strike time from 3 p.m. to 4 p.m. These outcomes present sturdy proof that index pricing conventions materially form when Treasury buying and selling happens.
Henry Dyer, a former analysis analyst within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group, is pursuing a grasp’s in finance on the MIT Sloan Faculty of Administration.
Michael J. Fleming is head of Capital Markets within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Or Shachar is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
How you can cite this put up:
Henry Dyer, Michael J. Fleming, and Or Shachar, “Treasury Buying and selling on the Shut,” Federal Reserve Financial institution of New York Liberty Avenue Economics, September 22, 2026, https://doi.org/10.59576/lse.20260922
BibTeX: View |
Disclaimer
The views expressed on this put up are these of the creator(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the creator(s).
