

Whereas monetary advisors typically have discretionary management over a shopper’s whole funding portfolio, typically new purchasers enter an advisory relationship with massive, ‘legacy’ positions that they are not looking for (or aren’t in a position) to liquidate. For example, the shopper may personal a major variety of shares in a carefully held enterprise, maintain a big place in firm inventory topic to a lock-up interval, or have inherited shares of inventory from a cherished one which maintain emotional worth. Whereas an advisor is perhaps tempted to view such positions as peripheral (significantly if the agency is not charging a charge on these property), they are often topic to regulatory and civil litigation dangers if the agency would not have a transparent course of for advising on (or round) them – together with thorough documentation and constant disclosure of advisable actions to purchasers.
On this visitor put up, Wealthy Chen, the founding father of Brightstar Legislation Group, discusses how RIAs’ fiduciary obligations apply to legacy positions, frequent eventualities (and traps) when coping with them, billing issues for corporations, and greatest practices for advisors in managing legacy property.
Below the Funding Advisers Act of 1940, funding advisers, whether or not or not they’re registered with the SEC, owe purchasers a Federally-defined fiduciary responsibility comprised of two distinct obligations: an obligation of care and an obligation of loyalty. Notably, each duties apply to legacy property; whereas the scope of an advisor’s fiduciary obligations could also be formed by settlement between the shopper and advisor, the responsibility can’t be waived utterly.
There are a number of ‘traps’ advisors can fall into when managing legacy property, from assuming that restricted buying and selling authority means restricted duty (when it doesn’t), over-reliance on verbal understandings which might be by no means documented (and {that a} shopper may bear in mind in another way years later), inconsistency throughout paperwork (e.g., an advisory settlement saying one factor and billing statements implying one other), and preparations that have been affordable when established however have change into more and more problematic as a shopper’s circumstances have modified. Presenting options (to persevering with to personal the legacy place) to the shopper – and documenting this communication – is the advisor’s greatest protection towards regulatory examination and civil litigation.
Billing on legacy property presents one other problem, as regulators will wish to make sure that the advisor’s charges are affordable given the extent of service they’re offering. Companies have a number of choices for dealing with billing round legacy investments, together with excluding legacy property from billing fully, persevering with to invoice on these property whereas documenting client-imposed restrictions, and adopting different charge constructions (e.g., charging a flat planning charge plus an asset-based charge on managed property) designed to raised align compensation with companies rendered. Importantly, there isn’t any one ‘proper’ method; a agency may select a selected method primarily based by itself service mannequin and the distinctive circumstances of its purchasers.
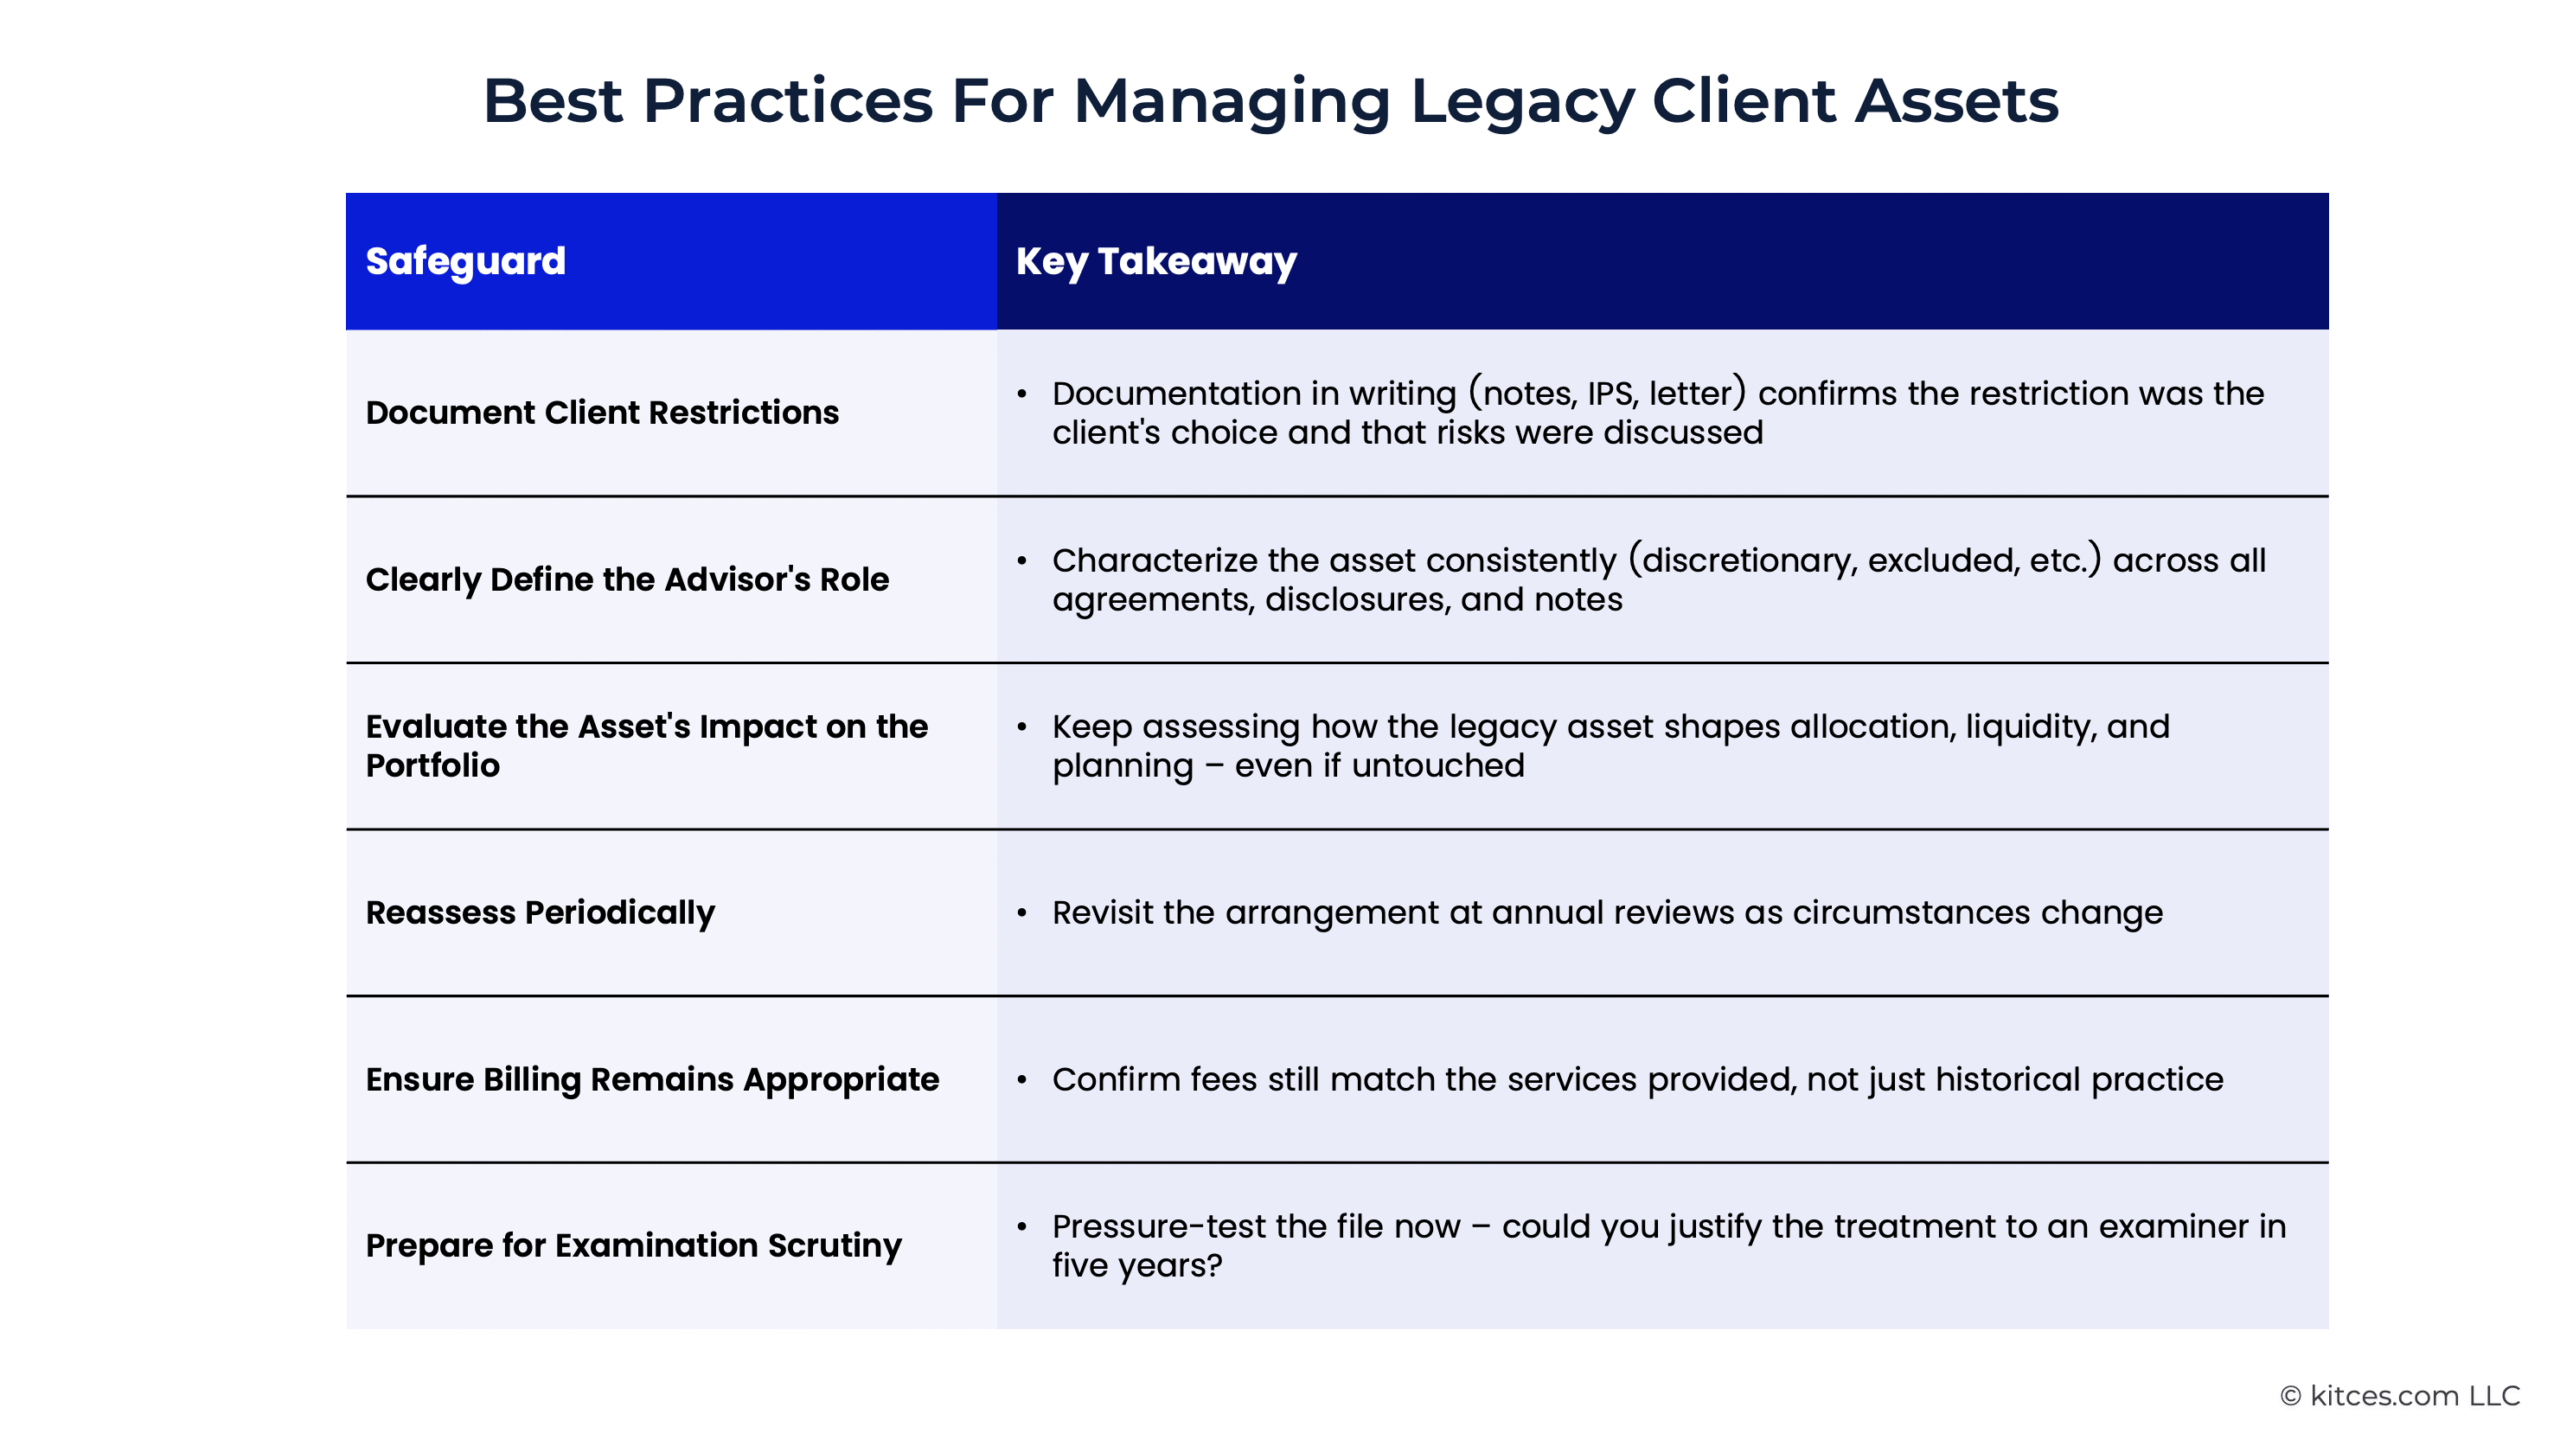
Amidst this backdrop, a number of greatest practices emerge for working with shopper property to stop misunderstandings and mitigate the chance of civil litigation and/or regulatory actions, together with documenting shopper restrictions, clearly defining the advisor’s function, evaluating the asset’s influence on the general portfolio, reassessing legacy asset preparations periodically, guaranteeing billing practices stay applicable, and making ready for examination scrutiny prematurely. In sum, the simplest corporations acknowledge that legacy property require extra course of than advisor-managed property, not much less, as a result of the advisor’s restricted authority makes documentation and communication all of the extra vital.
Finally, the important thing level is that as a result of there isn’t any common rule regarding dealing with legacy funding positions, corporations can greatest serve their purchasers’ pursuits (and defend themselves) by constructing a repeatable, constant framework to deploy when working with a shopper with such a place!
 |
And if you wish to go deeper on this subject, hear straight from the creator on the Monetary Advisor Technician podcast. |


